

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Test & Burn-in Sockets Market to Reach USD 2.15 Billion in 2026 (6.05% CAGR)

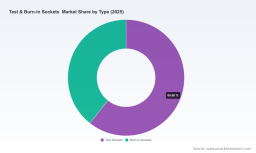
Test & Burn-in Sockets: Strategic Imperatives for 2026 Decision-Makers
Executive summary
The Test & Burn-in Sockets market stands at a strategic crossroad. After half a decade of steady recovery and modernization, PW Consulting’s new market study finds the global market size at roughly USD 2.06 billion in 2025 and forecasts expansion to about USD 2.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 6.05% across the 2026–2032 forecast window. Market concentration remains meaningful (CR3 ~48.6%, CR5 ~62.5%), yet pockets of specialization, technology differentiation, and regional manufacturing dynamics create fertile ground for both established suppliers and agile entrants.
Test & Burn-in Sockets Market
Why this study matters for 2026 strategic decisions
-
Time‑sensitive capital allocation. Memory and advanced compute cycles, testing capital refresh, and qualification programs will force OEMs and test houses to prioritize investments in socket technologies and supporting fixtures over the next 12–24 months. Strategic procurement and capex decisions made in 2026 will lock in costs and supplier relationships for the next five years; our study quantifies the market trajectory and provides the scenario analysis needed to de‑risk those choices.
Test & Burn-in Sockets Market -
Product roadmaps and packaging transitions. The rapid adoption of advanced packaging (chiplet integration, CPO, heterogeneous integration) is changing mechanical, thermal, and signal‑integrity requirements for sockets. The report synthesizes how these technology transitions map to test and burn‑in hardware requirements—critical intelligence for product management, validation teams, and test engineering leaders.
Test & Burn-in Sockets Market -
Supply‑chain and manufacturing resilience. The market’s mid‑to‑high concentration suggests supplier power in selected niches. For procurement and operations teams, the report’s supplier risk matrix and contingency scenarios are tactical tools to ensure continuity of high-volume burn‑in and test runs, especially under surges in demand for AI/HPC and memory modules.
Market trajectory: what the numbers imply (without giving every split)
The headline growth path—from roughly USD 2.06 billion in 2025 to about USD 2.8 billion by 2032 at ~6.05% CAGR—encapsulates three overlapping demand vectors:
-
Volume expansion from next‑generation memory and AI accelerator stacks that require high‑reliability burn‑in and high‑pin‑count test solutions.
-
Higher per‑unit content driven by advanced socket engineering (thermal control, fine‑pitch contact technology, multi‑site modular fixtures) that increase average selling prices and test complexity.
-
Replacement and lifecycle expenditure as qualification cycles tighten and the cost of field failures rises for cloud and edge providers, elevating burn‑in program spend.
While regional and application breakdowns drive tactical supplier selection, the macro picture is clear: incremental growth is real and predictable, but compound risks from packaging shifts and silicon performance requirements demand active strategic management.
Dynamics and technology inflection points
-
Advanced packaging as a disruptor: Industry fora from 2026 (e.g., TestConX sessions) have framed the testing challenge as “Burn‑In at the Inflection Point,” focusing on the interaction between chiplets, CPO, and production test. The upshot: sockets must evolve from passive carriers to active enablers of thermal control, signal integrity, and efficient multi‑site throughput.
-
Mechanical and thermal validation is now mainstream: Presentations at recent conferences emphasized methods for characterizing socket housing deflection and validating mechanical robustness at scale—topics that elevate supplier selection from “does it fit” to “does it preserve yield, SI, and lifetime.”
-
Materials and contact technologies: Elastomeric, pogo‑pin, and SPEC contact approaches coexist; choice depends on frequency, pitch, lifetime, and thermal cycling. Test houses will increasingly prioritize modular systems that allow rapid swap‑outs as device I/O geometries evolve.
-
High‑temperature and high‑current requirements: Defense, aerospace, and certain compute workloads continue to demand rugged, high‑temperature burn‑in solutions—an area where specialized suppliers remain differentiated.
Competitive landscape: reading the supplier map
Buyers face a diverse set of suppliers, ranging from global OEMs with broad portfolios to niche specialists. The market’s CR3/CR5 concentration statistics indicate that while a few suppliers command significant share, there remains enough fragmentation to enable targeted selection based on engineering fit and commercial terms.
-
Yamaichi Electronics (Tokyo) remains a go‑to for high‑density BGA/LGA and custom sockets, leveraging SPEC contact technology to serve AI/HPC and advanced packaging customers that demand signal integrity and high reliability.
-
Enplas (Nagano) is well positioned for high‑volume precision molded solutions—favored by memory and logic manufacturers that prioritize repeatability and injection‑molded cavity performance for throughput economies.
-
Smiths Interconnect (Plastronics) (London) offers modular, high‑temperature, high‑current designs and is often the supplier of choice for defense/aerospace and other sectors where environmental endurance is paramount.
-
Loranger International and Robson Technologies (both California) bring deep custom‑SKU portfolios and turnkey board integration services—valuable for test houses seeking quick time‑to‑market with bespoke QFN and board integration needs.
-
Regional specialists (e.g., LEENO , ISC , WinWay , Yokowo ) deliver optimized sockets for memory and high‑pin‑count packages emerging from East Asia’s manufacturing clusters—an important factor for procurement teams sourcing near fabs.
-
Electronics and materials conglomerates ( 3M , Eaton , Sensata ) bring scale, integrated thermal solutions, and robust contact technologies—options for customers seeking integrated thermal management or established supply reliability.
-
Spring probe and contact specialists ( Rika Denshi , Ironwood , Okins , Johnstech , Aries ) occupy critical niches where contact lifetime and high‑frequency performance are non‑negotiable.
For board‑level integrators and OEM test engineering groups, the choice of supplier will typically hinge on three axes: (1) mechanical and thermal validation capability, (2) contact technology and expected lifetime, and (3) speed of customization and supply continuity. Our report provides supplier scorecards and a matchup framework that lets buyers map those axes to their product portfolios and volume commitments.
Recent market signals and trade‑show intelligence
-
Trade shows in early to mid‑2026 have reinforced the narrative: companies such as Seiken, LSG, and Smiths Interconnect used TestConX and SWTest to highlight burn‑in and socket innovations, interposers, and probe solutions. These public signals point to suppliers prioritizing modularity, SI validation, and thermal control in their product roadmaps.
-
Conference sessions focused on “next‑generation test socket evaluation” and methods for characterizing large housing deflection indicate that cross‑industry testing standards and performance benchmarks are coalescing—an important trend for buyers planning multi‑vendor deployments or seeking to shorten qualification cycles.
What the PW Consulting report contains (high‑value, action‑oriented deliverables)
-
Market model and scenario forecasts (2020–2032) with base‑year calibration and three demand scenarios to support capex planning and procurement negotiation strategies.
-
Supplier scorecards and a capability matrix covering mechanical, thermal, SI, contact technology, customization lead times, and supply‑chain resilience—designed for rapid shortlisting.
-
Technical annexes: test methodologies, qualification protocols, and validation checklists for mechanical deflection, thermal cycling, and signal‑integrity acceptance criteria.
-
Commercial playbook: pricing benchmarks, total cost of test (TCoT) models, and procurement negotiation levers that reflect lifecycle, yield impact, and replacement cadence.
-
Strategic scenarios: implications of packaging shifts (chiplet/CPO), multi‑site burn‑in scaling strategies, and supplier consolidation or partnership playbooks.
-
M&A and investment heatmap: pockets of attractive consolidation, capability acquisition targets, and licensing considerations for contact and interposer IP.
Strategic implications and immediate actions for 2026
-
Reassess supplier qualification gates: tighten mechanical and thermal acceptance criteria in RFPs and include modularity and interchangeability clauses to mitigate rework when device form factors change.
-
Lock in multi‑year agreements for capacity where supplier exposure is constrained, but keep options for rapid technology swaps—use the report’s supplier risk scoring to prioritize partners.
-
Invest in in‑house validation capability for SI and thermal characterization to shorten qualification loops and reduce dependence on external labs during packaging inflection events.
-
Run a TCoT assessment across the product portfolio this year: higher per‑unit socket costs can be justified if they materially reduce field failure risk and improve throughput; our models show the breakpoints across common packaging scenarios.
Call to action
The 2026 decision window is narrow: procurement cycles, capital planning, and product qualification schedules converge this year for many semiconductor OEMs and test providers. PW Consulting’s full Test & Burn‑in Sockets Market report equips leaders with the market modeling, supplier evaluations, and technical frameworks necessary to make defensible, value‑creating choices. For the full segmented forecasts, supplier scorecards, and the technical annexes that underpin the strategic recommendations summarized here, please consult the complete report on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Test & Burn-in Sockets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com