

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Inkjet Printer Head Market to Reach USD 148.3M by 2032, 4.1% CAGR

Inkjet Printer Head Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
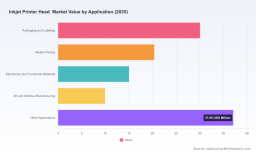
The inkjet printer head market is at an inflection point. After a steady recovery through the early 2020s, the global market — measured on a USD million revenue basis — expanded from roughly USD 93 million in 2020 to about USD 112.5 million in the 2025 base year used for this research. Our forecasting horizon through 2032 projects a compound annual growth rate (CAGR) of 4.1%, with the market continuing to evolve in complexity and commercial opportunity as industrial, packaging, electronics and additive-manufacturing applications deepen their reliance on high-performance printheads.
Inkjet Printer Head Market
This preview is designed to orient senior executives, product leaders and corporate strategists to the forces that will determine winners and losers in 2026. It highlights directional market dynamics, technology inflection points, competitive positioning and the practical, decision-focused deliverables included in the full PW Consulting study — while intentionally withholding the granular, proprietary segment breakdowns that are only available in the complete report.
Inkjet Printer Head Market
Why 2026 matters
-
Operational cadence: Investment cycles and capex plans locked down in 2026 will shape manufacturing throughput and materials sourcing into the early 2030s. With the market already above the USD 100‑million mark in recent years and a predictable mid-single‑digit CAGR, 2026 is the last full year for many firms to align roadmaps with forecasted demand curves.
Inkjet Printer Head Market -
Technology convergence: Advances in thin‑film piezoelectric fabrication, MEMS-based silicon actuators and recirculation architectures are lowering barriers to higher-viscosity fluids and multi-color heads. These technical advances create opportunities to displace incumbent solutions in established verticals and to address adjacent industrial deposition markets.
-
Regulatory and sustainability inflection: Tighter environmental rules and circular‑economy initiatives — particularly in Europe — are accelerating adoption of monitoring-enabled printheads and sustainable materials strategies. Compliance with standards such as RoHS variants, flame retardancy benchmarks and PCB material safety protocols is increasingly non-negotiable for OEMs and end users.
Market trajectory and what it implies
The market’s trajectory over 2020–2025 demonstrates resilience despite episodic demand swings. The transition into 2026 is best described as measured growth rather than runaway expansion: the sector is maturing. For executives this means strategy should shift from “land-grab” expansion to focused value capture — optimizing unit economics, reducing total cost of ownership for buyers and extracting services revenue tied to predictive maintenance and nozzle-health analytics.
Consolidation dynamics are visible. The market concentration metrics indicate that a small set of global OEMs controls a meaningful share of revenue and technology supply — creating an environment where partnerships, selective M&A and component-level differentiation are effective levers for middle-tier players to scale rapidly. For large incumbents, the imperative is to defend platform positions while accelerating adjacent capabilities (e.g., electronics, ink chemistry partnerships, and embedded diagnostics).
Technology and supply‑chain realities
-
PZT and thin‑film piezo technology remain a performance backbone. Sputtered PZT actuators and fine ceramics piezoelectric stacks enable trillions of actuations in modern heads, delivering both durability and cost‑efficiency at scale. These materials and processes are central to long‑lived industrial heads used in high-throughput packaging and textile machines.
-
Recirculation, multi‑color heads and high‑viscosity capabilities are moving from niche to mainstream. Vendors are addressing reliability and clogging through mechanical and software controls rather than purely chemical fixes — a shift that elevates the role of electronics and embedded diagnostics in product roadmaps.
-
PCB and materials compliance has become a functional differentiator. Printhead modules and their PCBs increasingly must meet flammability and hazardous‑substance standards, a requirement that affects supplier selection, certification timelines and aftermarket liability.
Competitive landscape — who to watch
The competitive set is technologically heterogeneous but strategically aligned around high-resolution, industrial-grade printheads and systems integration. Leading OEMs are leveraging proprietary actuator technologies, platformized mechanical designs and service ecosystems to sustain margins.
-
Konica Minolta (Tokyo) — A leader in thin‑film piezo platforms and high-resolution industrial heads. Recent launches in late 2025 showcased multi‑color jetting capability from a single head and new KM1800i variants designed for demanding PCB and deposition uses. These product moves underscore a strategy of enabling higher throughput applications while ensuring regulatory compliance across PCB and material standards.
-
Xaar plc (Cambridge, UK) — Known for industrial drop‑on‑demand piezo heads and modular printbars, Xaar’s engineering emphasis on ceramics and high-viscosity fluid handling positions it strongly in packaging and industrial graphics, where robustness and throughput are prioritized.
-
FUJIFILM Dimatix (Lebanon, NH) — Their VersaDrop and sputtered PZT actuator technology underpins strong performance in materials deposition and specialized industrial applications. Their technology depth makes them a frequent partner for companies trialing functional inks or electronic deposition use cases.
-
Meteor Inkjet (Cambridge, UK) — A critical ecosystem player rather than a head manufacturer, Meteor differentiates through electronics, software and nozzle‑health monitoring that enable third‑party heads to be run at optimal performance. Their recent support announcements for new Ricoh hardware illustrate the rising importance of electronic and software compatibility layers.
-
Ricoh (Tokyo) — A major force in MEMS and thin‑film piezo-based heads with designs emphasizing recirculation and high-speed coding/packaging use. Ricoh’s product families are commonly selected where industrial uptime and long maintenance intervals are required.
-
Seiko Instruments (SII Printek, Matsudo) — Offers heads with isolated channel architectures and a strong presence in wide‑format and coding applications. Their differentiated fluidic architectures reduce cross‑talk and maintenance overhead in demanding environments.
-
Kyocera (Kyoto) — Focuses on fine‑ceramics actuators for high-speed, high‑image‑quality needs and has recently introduced hardware aimed at high‑viscosity materials, signaling intent to capture share in materials‑heavy industrial markets.
Across the competitive set, recent product activity (late‑2025 to mid‑2026) shows a clear emphasis on multi‑color capability, high‑viscosity material handling and enhanced electronics/software support. These trends reflect buyers’ priorities: higher throughput, lower downtime, and more rapid integration into industrial production lines.
Regulation, sustainability and operational risk
-
Compliance is now table stakes. Leading vendors publicly ensure compliance with flammability standards, RoHS variants and industry PCB protocols — a necessary condition for participation in regulated supply chains.
-
Environmental and circular‑economy initiatives in key markets are driving demand for monitoring-enabled heads and reduced consumable consumption. Buyers are increasingly procuring systems that provide measurable ink‑use efficiencies and defect-reduction telemetry.
-
Materials availability — especially for specialized piezo ceramics and thin‑film deposition inputs — remains a strategic procurement risk. Buyers and OEMs that lock in multi‑year supply agreements or vertically integrate thin-film processing gain a durable advantage.
What PW Consulting’s full report delivers
The full study is built for action. For executives evaluating investments in 2026, the report provides:
-
Proprietary market sizing and scenario forecasts through 2032, including demand drivers by vertical and technology pathway (note: detailed segment tables and proprietary model outputs are reserved for the full report).
-
Technology benchmarking: comparative analysis of actuator types, fluidic architectures, and electronics/software stacks with recommended adoption roadmaps by use case.
-
Buy‑side playbooks: total cost of ownership (TCO) templates, procurement negotiation anchors, and integration checklists for OEMs and end users.
-
Supply chain and materials heatmap: critical input risk assessments, supplier scorecards and mitigation options (including capex scenarios for in‑house thin‑film capability).
-
Competitive intelligence dossiers on leading vendors, with product roadmaps, go‑to‑market strategies and potential M&A targets aligned to 2026 strategic windows.
-
Regulatory and compliance compendium: practical guidance for meeting flammability, hazardous‑substance and circular‑economy requirements across major markets.
-
Operational and service design templates: nozzle‑health analytics, predictive maintenance architectures, and aftermarket monetization models.
How to use these insights in 2026
-
Product strategy — prioritize platform architectures that support modular upgrades (electronic and fluidic) to protect R&D investments against rapid technology shifts.
-
Partnerships — seek alliances with electronics/software specialists to deliver differentiated uptime and telemetry; consider commercial models that bundle hardware with predictive‑maintenance services.
-
Procurement — secure multi‑year supply agreements for critical thin‑film and piezo materials; build flexibility clauses that allow for rapid scaling as forecasted demand materializes.
-
M&A and investment — target companies that add nozzle‑health, software, or specialized materials capabilities; prioritize assets that accelerate time‑to‑market for high‑viscosity and multi‑color heads.
-
Regulatory readiness — embed compliance validation early in product development cycles to avoid costly rework and to access regulated buyers sooner.
Final note — a preview, not the whole story
This introduction synthesizes the strategic contours that will define winning plays in the inkjet printer head market across 2026 and beyond. It intentionally abstracts away the granular segment tables, regional splits and proprietary model outputs that are required to translate insight into executable plans. For organizations planning procurement cycles, product roadmaps or acquisition screens in 2026, the full PW Consulting report provides the detailed, actionable intelligence and model access necessary to move from strategy to execution.
Contact PW Consulting to request the full market study, access the model workbook and schedule a bespoke briefing for your leadership team.
For detailed analysis of this topic, please visit the official page: Inkjet Printer Head Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com