

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Consumer IoT Market to Soar to USD 549.6 Billion by 2032, Driven by a 14.85% CAGR
By pmarketresearch, 2026-07-13
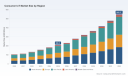
Consumer IoT Market 2026: A Strategic Preview — Why PW Consulting’s New Report Is Mission-Critical for Executive Decision-Making
As consumer IoT accelerates from novelty to necessity, 2026 will be a pivot year for companies building products, platforms, and ecosystems. PW Consulting’s forthcoming Consumer IoT Market report synthesizes five years of historical evidence and robust forecasting to translate market momentum into executable corporate strategy. This preview summarizes the report’s macro posture, competitive takeaways, regulatory inflection points, and the concrete actions senior leaders should prioritize when allocating capital, shaping partnerships, and designing product roadmaps for 2026.
Consumer Iot Market
Macro view: growth trajectory and market structure
The consumer IoT market has moved from early expansion into rapid scale. Our model — which uses 2020–2025 as the historical baseline, takes 2025 as the base year, and projects through 2026–2032 — shows continued strong expansion at a compound annual growth rate (CAGR) of 14.85%. This pace positions the market to more than double over the forecast window, underscoring a structural shift in consumer behavior, device affordability, and network capability.
Consumer Iot Market
Equally important to growth is market structure. Market concentration metrics indicate a market that is neither monopolized nor atomized: the three-largest players account for a meaningful but not dominant share, and the top five consolidate under 50% of market revenue. In practice, this means incumbents retain strong influence through platform and distribution advantages, while a broad field of innovators can still win share through differentiated product features, pricing, and vertical specialization.
Consumer Iot Market
What the report delivers — practical, transaction-ready intelligence
- Proprietary demand model calibrated to real-world shipments and channel data, delivering topline forecasts and scenario sensitivities for 2026 planning cycles.
- Executive dashboards and KPI trackers tailored for product, corporate development, and regulatory teams (including unit economics, TAM/SAM estimates, and scenario-driven revenue paths).
- Vendor benchmarking and ecosystem maps that show platform interdependencies, interoperability readiness, and partner adjacency opportunities.
- Go-to-market playbooks with tested channel strategies for direct-to-consumer, retail, carrier bundles, and subscription conversions.
- Regulatory compliance checklists and impact assessments tied to major jurisdictions and upcoming mandates.
- M&A and partnership scorecards with shortlists of high-value targets by capability (edge AI, low-power connectivity, secure provisioning, and cloud orchestration).
- Supply-chain stress-tests and component-cost sensitivity analyses to model margin compression or restoration under different chipset and logistics scenarios.
Each section combines quantitative modeling with practitioner-focused recommendations — not academic theory. The intent is to arm leadership with both the numbers and the operational playbook to make swift, defensible decisions in 2026.
Competitive landscape: leaders, challengers, and what matters in 2026
The consumer IoT competitive map is shaped by platform control, brand trust, retail reach, and cost-to-serve. Ten companies in particular illustrate strategic archetypes executives should study:
- Amazon — Continues to leverage Alexa and retail scale to convert device ownership into recurring services. Recent wearable launches demonstrate a push to embed voice and ambient intelligence across consumer touchpoints. Strategic implication: incumbents should assess voice-as-a-service agreements and distribution partnerships to remain competitive on convenience and recurring revenue.
- Google — Focused on platform interoperability and ecosystem coherence; its rollout of Matter 1.3 support underscores a tactical emphasis on reducing friction for cross-vendor experiences. Strategic implication: prioritize Matter certification and compatibility investments to avoid being left out of bundled smart-home offers.
- Apple — Maintains a premium, privacy-centric approach. Expansion of HomeKit integrations signals a dual strategy: protect the walled garden while selectively enabling third-party experiences. Strategic implication: firms targeting premium segments must demonstrate privacy-first data handling to partner with or compete against Apple-led experiences.
- Samsung — Plays the ecosystem aggregator role — appliances to wearables — and recent certification moves for next-gen Wi‑Fi show readiness for higher-throughput, lower-latency use cases. Strategic implication: look for partnership opportunities around appliance integration and connectivity upgrades.
- Philips (Signify) , Sonos , and other appliance/audio incumbents — Hold product leadership in specific verticals; their ability to integrate with platform leaders will determine growth in bundled home solutions.
- iRobot — Product-led differentiation via advanced onboard AI and navigation is extending lifecycle value and aftermarket services; robotics remains a bellwether for consumer willingness to pay for autonomy.
- Arlo, Wyze, TP‑Link — Represent competing strategies across premium-to-value: Arlo emphasizes advanced features and cloud services; Wyze competes on price and accessibility; TP‑Link focuses on distribution and connectivity bundles. Strategic implication: companies should map where they want to play on the value-performance axis and design channel & support economics accordingly.
Taken together, these players show that future winners will combine platform reach, certification/standards compliance, and a flexible monetization mix (one-time device revenue, subscriptions, services). The report provides a vendor-by-vendor heatmap that ranks opportunity windows and partnership value.
Regulatory and standards landscape — immediate priorities
Regulation and standards will materially shape product roadmaps and GTM strategies in 2026:
- EU cybersecurity requirements for connected devices introduce compliance timelines that will affect product certification cost and time-to-market. Companies selling into Europe must bake compliance into 2026 roadmaps.
- US federal procurement standards and state-level security laws (e.g., unique default password requirements and vulnerability disclosure mandates) create baseline expectations that are increasingly global de facto norms.
- Broad industry adoption of the Matter protocol and accelerated certification counts mean interoperability is becoming table stakes for consumer IoT kits sold through mainstream channels.
- Connectivity evolution (Wi‑Fi 6E/7 and advanced low-power chipsets) is changing hardware BOM dynamics; marginal increases in chipset cost must be weighed against user experience and long-term ARPU upside.
Our report includes a jurisdictional impact matrix and a compliance-cost model to help legal, product, and operations teams budget and sequence remediation work through 2026.
Strategic implications — a prioritized 2026 action list for executives
- Hardwire interoperability and certification: Make Matter and dominant platform compatibility non-negotiable for new SKUs. Prioritize cross-certification paths that reduce integration friction for retail and carrier bundles.
- Design for regulatory resilience: Integrate security-by-design with clear supply-chain traceability and a prioritized certification roadmap to avoid market access delays in key regions.
- Re-evaluate monetization mixes: Test hybrid models that combine device sales with subscription services tied to value-add AI features and cloud orchestration. Use cohort-level economics from our report to model CAC payback under different scenarios.
- Optimize BOM vs. experience tradeoffs: Use component-cost sensitivity outputs to determine when higher-cost connectivity chips (e.g., Wi‑Fi 6E/7) materially improve retention and ARPU, and when they simply erode margins.
- Pursue tactical M&A and partnerships: Target edge-AI, secure provisioning, and subscription-enablement assets that accelerate time-to-market and reduce integration risk; our acquisition scorecards identify the capability gaps most impactful for 2026 scale-up.
- Strengthen aftermarket and services: Invest in warranty, predictive maintenance, and upgrade paths to convert device buyers into long-term subscribers — the revenue mix that supports higher valuations.
- Prepare channels for scale: Build retail merchandising and carrier-inclusive offers now to capitalize on the expected consumer upgrade cycle; the right channel economics will determine 2026 traction.
Methodology and evidence confidence
The report’s forecasts are built on a transparent methodology: historical shipments and revenue (2020–2025), a base-year calibration (2025 denominated in USD, revenue unit: Billion), and an explicit forecast period covering 2026–2032. We triangulate multiple data sources — primary interviews, device shipment data, component-cost intelligence, and proprietary demand elasticity models — to produce both point forecasts and scenario ranges. Key macro outputs are underpinned by the 14.85% CAGR noted above and a detailed sensitivity analysis you can use for budget stress-testing.
Why this matters for 2026 planning
Decisions made in 2026 will lock in platform positions, channel relationships, and regulatory compliance postures for the next business cycle. The combination of rapid market growth, moderate concentration, and tightening regulation creates a strategic window for companies that can move quickly on interoperability, secure their supply chains, and convert hardware into recurring value.
PW Consulting’s Consumer IoT Market report is designed to be operational: it not only explains where the market is headed, but shows what to do next — product specs to prioritize, partnership archetypes to pursue, regulatory milestones to budget for, and acquisition targets that close capability gaps.
Next steps
This article is a strategic preview. For the full dataset, granular segment breakouts, vendor scorecards, and downloadable executive decks that operationalize the recommendations above, access the complete report on the PW Consulting website. The full report contains the detailed tables, appendices, and modeling templates your teams will need to convert insight into 2026 action plans.
For detailed analysis of this topic, please visit the official page: Consumer Iot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 7.5% CAGR for At‑Home Laser Hair Removal Market Through 2032
By pmarketresearch, 2026-07-13
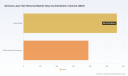
At Home Laser Hair Removal Market: Strategic Imperatives for 2026 — PW Consulting Deep Industry Brief
PW Consulting’s latest market research on the At Home Laser Hair Removal market provides a decision-grade roadmap for executives preparing strategies in 2026. Built on a base year of 2025 and a historical analysis spanning 2020–2025, the study combines rigorous market sizing, competitive diagnostics, regulatory risk-mapping and go-to-market playbooks that translate macro trends into executable options. The report quantifies market momentum (USD million basis) and delivers forward-looking scenarios across the 2026–2032 forecast window at a steady compound annual growth rate (CAGR) of 7.5% — a trajectory that reshapes choices for product development, channel deployment and M&A prioritization.
At Home Laser Hair Removal Market
Market trajectory: high-growth, durable demand
The at-home hair removal market has accelerated through 2023–2025, expanding from USD 821.5 Million in 2023 to USD 950.0 Million in 2025. Our modelling anticipates continued, above-market consumer adoption and incremental upgrades in device capability: the market is projected to surpass USD 1,021 Million in 2026 and reach roughly USD 1,576 Million by 2032 under the base-case scenario (USD, Million units). This expansion is being driven by a mix of consumer demand for clinical-grade results at lower total cost of ownership, product innovation in energy modalities and safety features, and the maturing of online-first distribution and bundled service models.
At Home Laser Hair Removal Market
Why 2026 is a strategic inflection point
- Regulatory clarity is tightening. Devices for at-home IPL and laser hair removal are regulated as Class II medical devices in the U.S., and the 510(k) clearance pathway remains the de facto market-access benchmark. Firms that align product claims, labeling and post-market surveillance with these expectations will avoid costly enforcement and protect brand equity.
- Consumer expectations have hardened. Across geographies, buyers increasingly prefer devices with proven safety layers — skin-tone sensing, cooling systems and energy-limiting profiles — and expect to see measurable hair reduction within a defined treatment window. Products that underdeliver or appear unsafe face rapid reputational damage amplified by social platforms.
- Channel economics are under pressure. As online retail dominates discovery and price transparency, margin recovery depends on service differentiation (extended warranties, subscription consumables, clinic tie-ups) and disciplined unit economics for paid-acquisition funnels.
- Technology and IP differentiation matter. Higher-energy diode lasers, elōs (combined modalities), and innovations in user experience (sensing, cooling, personalization algorithms) are becoming meaningful purchase drivers. Firms that can pair differentiated hardware with software-enabled care will widen competitive moats.
Competitive landscape: players, positioning and playbooks
The market structure is characterized by several established consumer-electronics and beauty-tech players alongside challenger brands. Competition mixes legacy consumer-electronics incumbents who leverage distribution and brand (e.g., European and global household names), specialist laser firms with clinical IP, and digitally-native Asian challengers optimizing price-performance and rapid product refresh cycles. Market concentration is moderate: leading players hold a meaningful share but no single company fully dominates — creating space for both scale-driven consolidation and focused innovation plays.
At Home Laser Hair Removal Market
Key companies profiled in the report include:
- Tria Beauty — San Leandro, California, USA — https://www.trialaser.com Offers the Tria 4X, a consumer-marketed diode laser cleared for at-home permanent hair reduction. Tria’s value proposition is higher per-flash energy and a clinical-strength performance narrative aimed at users seeking professional-grade outcomes.
- Philips — Amsterdam, Netherlands — https://www.philips.com Markets the Lumea IPL series with SenseIQ sensing and modular attachments. Philips leverages brand trust, broad distribution and consistent UX design to target mass premium buyers seeking ease-of-use across face and body.
- Braun (Procter & Gamble) — Kronberg im Taunus, Germany (P&G global operations) — https://us.braun.com Provides Silk-expert Pro and Skin i-expert devices, emphasizing rapid treatment cycles and adaptive skin-toning technology. Braun’s strength is in blending fast cycle times with P&G-grade global go-to-market capabilities.
- Ulike — Hangzhou, China (global ops with Seoul R&D) — https://www.ulike.com Focuses on comfort-driven innovation (e.g., ice-cooling) and portfolio breadth for diverse consumer segments, including male-targeted devices. Ulike exemplifies the fast-iterate challenger that pairs aggressive pricing with targeted product features.
- Cyden (SmoothSkin) — Swansea, Wales, UK — https://smoothskin.com Manufactures high-flash-count IPL devices with precision heads for face and body. SmoothSkin targets frequent users who value long device lifetimes and low per-treatment cost.
- Iluminage Beauty — Hong Kong / Shenzhen operations — https://www.iluminagebeauty.com Uses elōs technology (IPL + RF), with claims addressing broader skin tone safety. Iluminage is positioned at the intersection of professional-tech and consumer convenience.
Recent industry moves (covered in-depth in the report) include a new at-home IPL device introduced by a clinical laser OEM in January 2026 boasting high flash counts and skin-tone sensing, and product showcases by leading challengers throughout 2025 that demonstrate rapid feature cycles. These developments highlight two tactical realities for 2026: the hardware race continues, but incremental wins increasingly accrue to brands that package safety, clear regulatory positioning and a robust digital ownership experience.
Regulatory and safety dynamics: risk to revenue (and how to manage it)
Regulation is not a background factor — it is a strategic constraint. In the U.S., at-home IPL and laser devices meet Class II medical device definitions and commonly require 510(k) clearance for marketing claims of permanent hair reduction. Non-compliant or poorly labeled devices have faced enforcement actions and product recalls. Additionally, safety standards demand clear contraindications (skin phototypes, recent sun exposure, certain medical conditions) and energy limits appropriate for consumer use.
For 2026 planning, companies should prioritize:
- Regulatory-first product development: integrate 510(k)-grade verification into design cycles to avoid retrofit delays.
- Validated safety UX: skin-sensing, automated energy attenuation, and thermal mitigation technologies reduce liability and improve perceived value.
- Post-market surveillance and complaint handling frameworks aligned with FDA expectations — a differentiator for brand trust in digital-first channels.
Commercial levers: how to win distribution and loyalty in 2026
Winning in 2026 requires unpacking where value is created beyond the unit sale. Our analysis highlights three high-leverage commercial plays:
- Convert trial into recurring revenue. Bundle consumables, subscription-guided treatment programs, or clinic-upgrade pathways to extract lifetime value beyond the device purchase.
- Own post-purchase care. Digital coaching, remote troubleshooting, and outcome tracking increase retention and create defensibility against low-price competitors.
- Hybrid channel orchestration. Leverage direct-to-consumer channels for NMV and data capture while preserving strategic retail partnerships for reach. Use data to allocate marketing spend dynamically to acquisition cohorts with the highest long-term value.
What the PW Consulting report delivers (practical, non-obvious outputs)
This is not a pure-market-number exercise. The report synthesizes market sizing (USD Million, base year 2025; historical 2020–2025; forecast 2026–2032 at a 7.5% CAGR) with actionable deliverables:
- Executive playbooks for incumbents and challengers — go-to-market options mapped to resource profiles and desired speed of scale;
- Regulatory roadmap with template labeling, risk mitigations and a decision tree for claims versus 510(k) requirements;
- Product feature scorecards and prioritized R&D investment areas (energy modality, sensing, cooling, UX and consumable economics);
- Channel economics models with CAC/LTV sensitivity scenarios and recommended bundle structures to improve unit economics;
- M&A and partnership heatmaps — target characteristics, valuation heuristics and integration risk checklists;
- Risk and scenario planning — downside scenarios for regulatory shock, price erosion, and supply-chain disruption with contingency measures;
- Competitive dossiers on major players with strategic moves and tactical recommendations to neutralize threats or accelerate partnerships.
How to use this research in your 2026 planning cycle
For product leaders: prioritize validation paths that align with regulatory clearance expectations while designing for the in-home safety-first UX consumers now demand.
For commercial leaders: deploy hybrid channel pilots with retention-first economics and test subscription bundles that improve payback curves within 12–18 months.
For corporate development teams: scan for M&A targets that bring differentiated energy modalities, IP or high-value consumables rather than pure distribution plays — those assets deliver defensible margin expansion.
Conclusion — an invitation, not a full reveal
The at-home laser hair removal market is moving from early-adoption novelty toward a durable consumer health-and-beauty category. With a base of USD 950.0 Million in 2025 and a forecast path that grows at ~7.5% CAGR across 2026–2032, the sector presents both opportunity and regulatory complexity. PW Consulting’s report equips leaders to convert that macro momentum into defensible market positions. We intentionally provide strategic depth in this brief while retaining detailed segment-level analytics, company-level financials and tactical templates for subscribing clients — the proprietary core that materially shortens time-to-decision.
To access the full report and the downloadable executive toolkit (including scenario models, competitive dossiers and regulatory checklists), please visit the official report page or contact your PW Consulting industry lead for a tailored briefing.
For detailed analysis of this topic, please visit the official page: At Home Laser Hair Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Phenolic Resin Market Reaches USD 7,411.35 Million in 2025, Forecast to Expand at 5.01% CAGR Through 2026–2032
By pmarketresearch, 2026-07-13
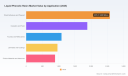
Liquid Phenolic Resin Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The global liquid phenolic resin market is entering 2026 from a position of steady expansion and strategic complexity. After reaching USD 7,411.35 Million in 2025, our market model projects growth to approximately USD 10,435.47 Million by 2032 — an expected compound annual growth rate (CAGR) of 5.01% across the 2026–2032 forecast window. The 2026 inflection year matters: supply‑chain shocks, regulatory tightening, and accelerating sustainability requirements will force executives to make investment and sourcing decisions now that will determine competitiveness through the end of the decade.
Liquid Phenolic Resin Market
Why this market matters to 2026 decision-makers
-
Cross‑sector exposure. Phenolic resins underpin products across wood adhesives, insulation, foundry binders, laminates and friction materials. Executive choices in procurement, product development and capacity planning ripple across multiple value chains.
Liquid Phenolic Resin Market -
Feedstock and price sensitivity. Phenol — the principal upstream feedstock — has shown renewed volatility, with Northeast Asia spot pricing signaling tighter market balance in early 2026. These moves materially affect margins for resin manufacturers and their customers.
Liquid Phenolic Resin Market -
Regulatory and sustainability pressure. Stricter formaldehyde emission standards and chemical bans introduced in recent years raise compliance costs, while certification regimes (e.g., ISCC PLUS) are already influencing buyer preferences in Europe and other advanced markets.
-
Consolidation and concentration. Market concentration metrics show that the leading firms capture a meaningful, but not overwhelming, share of the market, leaving room for regional champions, specialized toll manufacturers and consolidation-driven M&A.
Recent market signals to act on in 2026
-
Upstream cost pressure: Northeast Asia phenol spot prices reached about USD 1.01/kg in March 2026, reflecting maintenance outages and firmer resin demand. In China, local phenol pricing also moved materially higher in early 2026 — a near‑term signal for rising operating costs across the supply chain.
-
Regulatory tightening: Updates to formaldehyde emission standards and post‑2025 chemical restriction regimes (including bans impacting sensitive food‑contact uses) increase compliance spending and accelerate demand for lower‑emission resin chemistries.
-
Certification and differentiation: Leading producers are seeking sustainability certifications and circular feedstock pathways, with recent ISCC PLUS achievements demonstrating a commercial route to premium positioning in Europe.
-
Trade and tariff risks: Tariff measures introduced in 2025 continue to affect transpacific flows and sourcing economics, with duty exposure on some chemical and engineered-product imports reaching materially high levels in some jurisdictions.
Competitive landscape — what the leading players signal
The industry is characterized by a mix of global chemical majors, regional specialists and custom/toll producers. The competitive field includes vertically integrated producers capable of leveraging chemical integration and scale, European specialists with dense regional manufacturing footprints, and agile contract manufacturers that serve niche adhesive and composite needs.
-
Global integrated players (examples): Large chemical firms with broad downstream portfolios use feedstock scale and product breadth to defend volume and margin. Their competitive advantages include raw‑material hedging, integrated logistics and the ability to fund decarbonization investments at scale.
-
Europe‑focused specialists: Companies focused in Europe leverage regulatory experience, faster product approval cycles for low‑emission formulations, and deep relationships in construction and insulation value chains.
-
Asian capacity and cost players: Manufacturers with strong Asian production footprints benefit from lower operating costs and proximity to high‑growth end markets, but they are increasingly exposed to tariff and raw‑material price tailwinds.
-
Custom/toll and performance resin houses: These players serve formulation‑sensitive customers, offering ISO‑driven quality, small‑batch capabilities and rapid development cycles — attractive to downstream customers pursuing differentiation or rapid qualification timelines.
For buyers and investors, understanding the strategic posture of each competitor — from sustainability credentials to toll‑manufacturing flexibility and geographic exposure — is the basis for evaluating partnership, J‑V or acquisition targets in 2026.
Report highlights — what PW Consulting provides (practical content)
Our full Liquid Phenolic Resin Market report combines quantitative forecasting with hands‑on strategic tools tailored for 2026 decisions. Key deliverables include:
-
A validated market model and topline forecasts through 2032, including scenario runs to stress‑test demand under alternative macro and regulatory environments.
-
Feedstock sensitivity analysis that translates phenol and energy price moves into margin and pricing impacts for producers and large buyers.
-
Regulatory impact assessment quantifying compliance cost ranges and the commercial premium for low‑emission, certified products across major regulatory regimes.
-
Supplier scorecards and a commercial playbook for procurement: capability matrices, qualification timelines, and negotiation levers for captive vs. toll supply strategies.
-
M&A and partnership framework: target archetypes, value‑creation levers, and integration risk checklists mapped to typical deal structures in resin and adjacent value chains.
-
Go‑to‑market strategies for resin formulators and downstream OEMs to monetize sustainability claims, capture retrofit demand in building materials, and commercialize low‑emission resin grades.
Strategic recommendations for 2026
-
Lock in flexible feedstock arrangements: Negotiate contracts with indexed pricing bands, capacity release options and shared upside mechanisms to mitigate short‑term phenol volatility.
-
Prioritize regulatory‑ready product development: Accelerate low‑emission and formaldehyde‑reduced formulations; secure third‑party certifications where they materially influence procurement decisions.
-
Expand toll and contract manufacturing partnerships: For companies seeking agility without heavy capital outlays, toll arrangements offer speed to market and capacity buffering versus outright greenfield expansion.
-
Use tariffs and trade dynamics to rationalize regional footprints: Revisit plant location strategies and dual‑sourcing to minimize tariff exposure and reduce lead‑time risk in critical markets.
-
Targeted M&A: For buyers seeking scale or technology, look for regional champions with strong customer relationships and specialty product portfolios that can be scaled globally.
-
Deploy financial hedges and margin protection: Consider commodity hedges and commercial instruments to stabilize margins while pursuing premium product positioning.
Risk map — what to monitor through 2026
-
Upstream shocks: Maintenance outages or supply disruptions at phenol producers can rapidly tighten margins; procurement teams must build early warning indicators into S&OP processes.
-
Regulatory shifts: Sudden regulatory updates or enforcement actions on formaldehyde and related chemicals can create near‑term compliance costs and product relabeling burdens.
-
Trade policy volatility: Rapid tariff changes will continue to influence regional economics and require adaptive sourcing strategies.
-
Technology and substitution: Advances in alternative binders or bio‑based chemistries could accelerate premium erosion for conventional phenolic grades if incumbent firms are late to respond.
How PW Consulting’s report supports immediate action
For boards, strategy teams and commercial leaders preparing 2026 budgets and capex plans, the report provides the tactical inputs needed to close the gap between signal and action. Clients will receive downloadable datasets, supplier scorecards, scenario tools and a prioritized roadmap that translates market projections and regulatory scenarios into executable decisions with time‑bound milestones.
Final note — trailer
This preview outlines the strategic forces reshaping the liquid phenolic resin market as firms position for 2026 and beyond. The full PW Consulting report contains the granular segmentation, regional flows, application breakouts and actionable models you need to translate these trends into winning commercial and investment decisions. Request the comprehensive dossier to access the proprietary datasets, detailed supplier analyses and the recommended 90‑day action plan tailored to your company profile.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TV ODM Market Reaches USD 42,500 Million in 2025, Poised for Continued Growth
By pmarketresearch, 2026-07-13
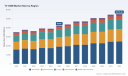
TV ODM Market 2026: Strategic Imperatives for C-Suites, Procurement Heads and Product Leaders
Executive snapshot
PW Consulting’s Tv ODM Market report establishes a forward-looking framework to guide enterprise decision-making through 2026 and beyond. Anchored on a 2025 base year and a clear forecast window to 2032, the study quantifies a steady industry expansion at a compounded annual growth rate (CAGR) of 3.8% and maps the structural forces reshaping TV original design manufacturing. By combining hard market-sizing, supplier capability mapping, and scenario-driven risk analysis, this report is designed as an executable playbook for executives who must balance cost, speed-to-market and technological differentiation in a market that remains capital- and supply-chain intensive.
Tv Odm Market
Market trajectory and implications for 2026
-
The global TV ODM market reached a robust scale in 2025 (base-year) and, under our baseline assumptions, is set to expand into the mid-to-late 2030s, growing from the 2025 base toward an expected total market significantly larger by 2032. This growth—while moderate in percentage terms—translates into meaningful absolute volume and revenue shifts for OEMs, ODMs and component suppliers alike.
Tv Odm Market -
Importantly, the market’s 3.8% CAGR masks heterogeneity in technology adoption, regional manufacturing shifts and channel dynamics. For corporate strategists, that means prioritizing flexibility: the companies that can reconfigure supply commitments, diversify sources, and accelerate integration of emerging display technologies will capture disproportionate share gains.
Tv Odm Market -
Market concentration metrics indicate a market neither fully fragmented nor monopolistic—leading-tier ODMs command meaningful share but there remains room for challenger models and contract manufacturers to scale quickly when they combine factory capacity with software/platform partnerships.
Why this report matters to decision-makers in 2026
-
Capital allocation and capacity planning: Our analysis converts macro growth into actionable manufacturing demand scenarios so CFOs and operations leaders can time investment in new lines or short-term capacity leasing.
-
Procurement and supplier strategy: With panel costs and IC prices volatile in early 2026, sourcing teams need granular supplier scorecards, hedging options and contract templates to prevent margin erosion.
-
Product roadmap and commercialization: R&D and product leaders will benefit from our adoption maps showing where premium display formats and smart-TV platform partnerships deliver the greatest price/feature elasticity.
-
Regulatory and geopolitics playbook: The study contains trade-policy scenario analyses—critical as governments revisit tariffs and onshoring incentives that could re-route manufacturing economics within 12–36 months.
What the report contains — an operationally focused index
-
Robust market sizing (historical 2020–2025) and demand-driven forecasts (2026–2032), with base-case, upside and downside scenarios informed by component-price shocks and policy interventions.
-
Technology adoption pathways (LED variants, emissive displays and incremental backlight innovations), with implications for BOM composition and margin sensitivity.
-
Comprehensive supplier ecosystem maps: factory footprints, scalable capacity options, licensing and platform partnerships, and time-to-market estimates by region.
-
Cost structure decomposition and supplier negotiation playbooks that quantify panel, IC and assembly exposure—plus practical contract clauses to manage lead times and warranty risk.
-
Go-to-market and channel strategies for brands and retailers, including private-label and licensed-brand models optimized for omnichannel distribution.
-
M&A and partnership screening tools: target prioritization matrices built on industrial economics, capacity synergies and IP/firm capabilities.
-
Regulatory and trade-risk module with mitigation plans (nearshoring, dual-sourcing, bonded-warehouse strategies).
Competitive landscape — profiles and strategic moves
The TV ODM market’s competitive map blends traditional electronics contract manufacturers, panel makers that offer ODM services, and specialist TV-focused OEMs. Leading players combine scale production, platform partnerships and multi-region footprints to serve global brand customers. Key incumbents and strategic characteristics covered in the report include:
-
MOKA (TCL MOKA) — A turnkey TV ODM with a proven track record in large-volume shipments and full-service solutions tied to the broader TCL supply chain. Recent platform partnerships have expanded its addressable pipeline for licensed brands and white-label customers.
-
AMTC — A China-headquartered ODM increasingly focused on export markets, with substantial capacity expansion outside China to serve North America and other key markets.
-
HKC — A vertically integrated supplier with multi-factory scale and recent capacity additions that materially alter regional supply dynamics; its footprint supports both OEM and ODM route-to-market strategies.
-
Express Luck — A rapidly scaling player transitioning from coastal park manufacturing to larger annual ODM throughput, representing the archetype of operators ready to capitalize on shifting orders.
-
TPV Technology, BOE VT, Foxconn, Innolux, KTC, JPE and several agile regional specialists — These firms span the gamut from large EMS/ODM OEMs to display-first suppliers offering integrated display + assembly solutions. Their strategic differences—platform partnerships, licensing relationships and in-region capacity—are explored in depth.
Notable developments tracked in the report include recent turnkey platform tie-ups that accelerate time-to-market for license holders, large greenfield factory commissioning that shifts capacity balance, and active trade-show participation that signals customer acquisition campaigns for global distribution.
Supply-chain stressors and policy risk
-
Component-cost volatility: Display panels remain the largest single cost component in TV manufacturing, and early-2026 inflationary pressure on panels, integrated circuits and memory has already pushed pricing assumptions. Buyers and manufacturers must recalibrate BOM and margin models accordingly.
-
Tariff and geopolitical headwinds: Policy proposals to restrict reliance on particular supply bases are creating a re-evaluation of sourcing geographies. For many brands and providers, this is accelerating investment in alternative assembly locations and contingency inventory models.
-
Capacity versus demand timing: Several large-scale factory ramp-ups and capacity shifts are changing lead-time dynamics; firms that can lock favorable supply terms early will enjoy a procurement advantage in 2026.
Strategic recommendations for 2026 (prioritized, actionable)
-
Immediate (0–6 months): Establish a supplier stress test across panel and IC exposure; negotiate short-term price collars or volume-flex clauses; identify two alternate OEM/ODM suppliers for critical SKUs.
-
Near term (6–18 months): Reassess capacity commitments and consider hybrid models (captive lines + contract capacity) to manage demand swings; accelerate platform-level integrations with select ODM partners to reduce software/hardware integration risk.
-
Medium term (18–36 months): Evaluate capex or strategic partnership to secure prioritized component supply (e.g., local panel agreements or equity stakes in upstream suppliers); incorporate trade-policy scenarios into sourcing and price pass-through clauses.
-
Competitive positioning: For brands: prioritize differentiated UX and platform partnerships over marginal hardware feature races. For ODMs: pursue services-led differentiation (turnkey software, logistics and after-sales) to escape pure price competition.
How to use the report
This report is structured as a decision-support tool rather than a descriptive catalog. Each chapter concludes with “playbooks” that translate insight into specific next steps (procurement templates, scenario inputs for financial models, risk-mitigation checklists). Executives will find checklists tailored to capital planning, supplier negotiations and product roadmap prioritization—intended to accelerate time-to-decision without redoing foundational analysis.
Closing — the strategic value proposition
As enterprises prepare budgets, capacity plans and go-to-market programs for the 2026 planning cycle, PW Consulting’s Tv ODM Market report delivers the macro context, competitive intelligence and operating levers necessary to make high-conviction decisions. The combination of a clear CAGR-based forecast, scenario-driven risk matrices and practical implementation templates positions this study as a single reference for teams aligning procurement, manufacturing and commercial strategy.
For senior leaders who must convert market signals into executable plans—and for teams who require the underlying segmentation, factory-level capacity schedules and supplier scorecards—our full report provides the data and the templates you need. Visit the PW Consulting Tv ODM Market report page to access the complete intelligence package, including downloadable models and supplier diligence kits.
For detailed analysis of this topic, please visit the official page: Tv Odm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Animal Monoclonal Antibodies Market Poised for 8.2% CAGR Through 2032
By pmarketresearch, 2026-07-13
Monoclonal Antibodies in Animals Market 2026: Strategic Imperatives for Executive Decision‑Making
PW Consulting today publishes its definitive industry briefing, Monoclonal Antibodies in Animals Market — Strategic Outlook (base year 2025). The report synthesizes five years of historical performance and a seven‑year forecast horizon (2026–2032), showing the veterinary monoclonal antibody sector moving from a firmly established specialty market toward broader commercialization. At a global level the market passes an important commercialization milestone in 2026 and continues on a sustained growth trajectory with a compound annual growth rate (CAGR) of 8.2% through 2032.
Monoclonal Antibodies In Animals Market
Why 2026 is an inflection point for corporate strategy
-
Regulatory momentum and new pathways: Over the past 18 months regulators in major jurisdictions have signaled practical shifts that accelerate time‑to‑market while increasing expectations for post‑approval evidence. Examples include recent conditional approvals and guidance changes that de‑risk earlier commercialization for lead candidates, plus regulatory moves to modernize non‑clinical testing approaches.
Monoclonal Antibodies In Animals Market -
Commercial validation: Several high‑profile product approvals and licensing deals reported through 2025–2026 have shifted the market from proof‑of‑concept to commercial scale. These events validate veterinary monoclonal antibodies as investable assets and catalyze follow‑on programs across companion and production animals.
Monoclonal Antibodies In Animals Market -
Concentration and competition: The market shows high concentration at the top — a small group of incumbents controls a substantial share of commercially available assets — creating both competitive barriers and strategic acquisition opportunities. Our market concentration analysis registers a CR3 of 65.4% and a CR5 of 78.2%.
-
Unit economics pressure: Production cost remains a structural constraint that will shape pricing, adoption and route‑to‑market decisions; companies that achieve meaningful cost reductions or differentiated value propositions will capture disproportionate returns.
Recent industry developments that matter for 2026 plans
-
Regulatory approvals and conditional pathways: Conditional approvals for veterinary monoclonal products have become an operational reality, providing first‑mover advantages for brands that couple accelerated market entry with robust post‑market evidence generation.
-
Notable commercial and licensing moves: Several licensing transactions and acquisitions in 2024–2025 demonstrate an active market for platform technologies and specialty assets, highlighting opportunities for biologics developers and animal health majors to expand via M&A or collaborations.
-
Policy and testing innovation: Regulatory agencies have announced plans to modernize non‑clinical testing approaches for biologics, which can shorten development timelines and reduce animal use when companies adapt early to new methodologies.
What PW Consulting’s report delivers — practical intelligence for 2026 decisions
This report is built for executives who need actionable choices rather than academic descriptions. It contains:
-
A top‑line market sizing and growth trajectory calibrated to the 2025 base year and extended through 2032, reflecting a clear CAGR of 8.2% under the base scenario.
-
Scenario modelling (base, upside, downside) with trigger points and sensitivity analyses that translate macro market moves into investment thresholds and go/no‑go criteria for new programs.
-
Competitive intelligence dossiers for the leading players and biotech licensors, including commercial positioning, regulatory strategy, channel models and partnership histories.
-
A regulatory playbook that maps expedited and conditional approval routes across major jurisdictions and specifies the post‑approval evidence plans necessary to convert conditional to full licensure.
-
Manufacturing and cost‑of‑goods (COGS) diagnostics, including a CMO landscape, capacity risk matrix and technology levers (expression systems, formulation innovations) that materially affect margins.
-
Commercial launch blueprints: field force design, veterinary channel segmentation, pricing and reimbursement decision trees, and early adopter engagement templates for specialty clinics and referral centers.
-
M&A and partnership playbooks: target screening criteria, valuation frameworks for platform technologies, and integration checklists for rapid scale‑up.
-
Practical appendices: primary interview excerpts, data‑model overview and methodology, and a redacted workbook that can be licensed for scenario re‑runs.
Competitive landscape — strategic takeaways for incumbents and entrants
-
Major animal health companies are leveraging existing clinical channels and brand trust to convert biologics into repeatable revenue streams. Leaders with approved canine and feline mAbs have set commercial playbooks that others will emulate; incumbents should accelerate channel partnerships and bundle services (diagnostics + biologic therapy) to protect share.
-
Conditional approvals (recent examples in 2025–2026) have become a tactical route for capturing clinical precedence. Firms that design development programs to meet conditional criteria — and allocate resources for mandated post‑market studies — can obtain market access ahead of full licensure rivals.
-
Licensing and boutique biotech activity has intensified: platform specialists and regional developers are now attractive acquisition or collaboration targets for companies seeking differentiated pipelines or novel delivery formats (for example, orally delivered antibodies for production animals).
-
Strategically, there are two dominant playbooks: (1) scale & defend — deploy capital to broaden indication coverage and clinical evidence to maintain leadership; (2) specialize & monetize — focus on platform strengths (e.g., oral mAbs, rapid passive immunity) and monetize through licensing and co‑development.
Five strategic moves to prioritize in 2026
-
Adopt an approval‑first commercialization cadence: target conditional or accelerated pathways where feasible, and build a resourced post‑market evidence plan to convert early entrants into enduring incumbents.
-
Lock in manufacturing flexibility: secure CMO capacity and invest in cost reduction technologies now to protect margins as volumes scale; dual‑sourcing and modular capacity reduce single‑point supply risk.
-
Design value‑based pricing tied to measurable clinical outcomes: given production costs, reimbursement models that tie price to effectiveness and dosing intervals will drive payer and clinician acceptance.
-
Build partnerships with diagnostic and specialty clinic networks to accelerate adoption and create bundled care propositions that capture higher lifetime value per patient.
-
Execute a targeted M&A/ alliance program: prioritize platform licensors, formulation specialists, and regionally dominant developers who can shorten time to market or broaden therapeutic scope with minimal integration risk.
Scenario planning — watchlist and decision triggers
The report provides three scenarios aligned to strategic planning cycles. The base scenario aligns with the market’s 8.2% CAGR and assumes steady adoption and timely regulatory conversions. Upside assumes faster adoption driven by price erosion and large‑scale production efficiencies; downside reflects delayed approvals, reimbursement pushback, or manufacturing bottlenecks. We recommend executive teams monitor four primary triggers: regulatory policy updates, major approval outcomes, announced capacity expansions or CMO failures, and significant pricing or reimbursement decisions by large procurement channels.
How to put the report to work in your 2026 planning cycle
-
Investment committees: use the model to size potential returns across launch timelines and acquisition targets.
-
R&D and regulatory teams: adopt the regulatory playbook to re‑sequence trials for conditional pathways and set post‑market study budgets.
-
Commercial leadership: apply the launch blueprints to adapt field coverage and pricing strategies to local clinic economics.
-
Corporate development: leverage the partner scoring and valuation tools to prioritize licensing and acquisition targets that close capability gaps.
What we are intentionally withholding (and why)
Consistent with the “trailer” approach of this release, this briefing demonstrates the strategic insights and analyses contained in the full PW Consulting report while withholding the granular region‑by‑region and application‑level revenue tables and line‑by‑line forecasts that are central to tactical deployment. Those detailed splits and proprietary forecast workbooks are gated in the full report to preserve client value and enable confidential scenario re‑runs tailored to your organization’s portfolio and risk tolerance.
Next steps
Executives looking to convert this intelligence into 2026 decisions can license the full report and model package, commission a bespoke competitive deep‑dive, or schedule a strategy session with PW Consulting’s Animal Health practice. Our client work focuses on translating market growth (as captured in our base CAGR of 8.2% through 2032) into specific investment, R&D and commercialization actions that materially change outcomes.
PW Consulting — Strategy for the bio‑enabled animal health economy. For report access and engagement inquiries, please visit PW Consulting’s report page or contact our Animal Health practice leadership to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Monoclonal Antibodies In Animals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Phased Array Coil Market to Expand at a 6.32% CAGR Through 2032
By pmarketresearch, 2026-07-13
Phased Array Coil Market Outlook 2026: Strategic Priorities for the Next Wave of MRI Innovation
PW Consulting’s latest Phased Array Coil Market report positions industry leaders and investors to make informed, high-conviction decisions in 2026. Our analysis shows the global phased array coil market expanding from an estimated USD 827.5 million in 2025 to roughly USD 1.27 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.32% across the 2026–2032 forecast window. For executives deciding where to allocate R&D, M&A, and commercial resources this year, the report crystallizes the practical levers that separate winning strategies from marginal plays.
Phased Array Coil Market
Why 2026 is a Pivotal Planning Year
Medical imaging OEMs, contract manufacturers, and specialty coil innovators face converging pressures in 2026: accelerating clinical demand for higher-resolution, faster throughput MRI; tightening regulatory pathways that emphasize cross-vendor compatibility and safety; and margin pressure from the emergence of third‑party and refurbished coil supply. Our research finds that these forces create asymmetric opportunities for organizations that pair technical differentiation (high-channel arrays, flexible form factors, multi-nuclear capability) with disciplined commercialization — including validated OEM integrations, regulatory preparedness, and targeted reimbursement strategies.
Phased Array Coil Market
Core market dynamics and strategic implications
-
Structural growth, underpinned by clinical adoption. The market’s mid-single-digit CAGR signals steady, sustainable demand rather than a hype-driven spike. That supports multi-year investments in product families (e.g., high-density head & neck, large-bore body arrays) but cautions against one-off, capital-intensive gambits without clear upgrade or service revenue models.
Phased Array Coil Market -
Differentiation through ergonomics and workflow. Flexible, lightweight designs that improve patient comfort and reduce setup time are proving to be as commercially decisive as marginal SNR gains. In 2026, buyers will increasingly prize total-cost-of-ownership calculations that include throughput and technician efficiency.
-
Regulatory and compatibility as market access gates. Class II device classification, IEC safety standards, and OEM compatibility validation are non-negotiable. Companies with mature regulatory dossiers and cross-platform compatibility programs will secure preferred-supplier status in hospital systems and consolidated imaging networks.
-
Service & refurbishment as margin anchors. Contract manufacturing and repair/refurbishment services continue to compress hardware margins but create predictable aftermarket revenue. Integrating refurbishment and service into commercial offers can materially improve lifetime value.
Competitive landscape: incumbents, specialists, and new entrants
The market remains populated by a mix of large OEMs, dedicated coil specialists, contract manufacturers, and agile start-ups. Each cohort brings a distinct strategic play:
-
Established OEMs (e.g., Siemens Healthineers, GE HealthCare, Philips, Canon). These players couple integrated coil portfolios with platform-level advantages (pulse sequence optimization, reconstruction pipelines). Their strength lies in bundled upgrades, field service networks, and channel reach; however, their product roadmaps are constrained by broader system development cycles.
-
Specialty coil innovators (e.g., RAPID Biomedical, NORAS, InkSpace Imaging, Magnetica). These companies move fast on technical differentiation — dual-tuned arrays, ultra-light flexible designs, and research-grade high-channel count coils — and increasingly secure regulatory clearances that open clinical markets. Their agility allows them to capture niche clinical use-cases and to partner with academic centers to validate performance.
-
OEM-aligned challengers and integrated Chinese suppliers (e.g., United Imaging). Combining scale manufacturing with aggressive product portfolios, these entrants are accelerating price/performance competition in certain markets and expanding channel options globally.
-
Contract manufacturers and refurbishers (e.g., ScanMed). Offering ISO-certified production and 510(k)-capable manufacturing, these firms are essential partners for both OEMs and independents aiming to optimize cost structures and accelerate time-to-market.
Recent product and regulatory developments underscore market momentum. Notable examples include new flexible pediatric arrays and lightweight high-channel clinical coils that obtained regulatory clearances in 2025–2026, as well as dual‑tuned and non-proton arrays that broaden clinical and research applications. These developments create tactical opportunities for partnerships, label-expansion plays, and platform co-development.
Regulatory, reimbursement, and safety considerations
-
Regulatory framework. Phased array coils fall under established medical device frameworks (notably 510(k) pathways in the U.S.) and must conform to MRI safety standards (IEC 60601 series). Manufacturers should anticipate increasing scrutiny around interoperability, labeling for parallel imaging use, and SAR management in high‑channel configurations.
-
Reimbursement influence on adoption. Regions with reimbursement policies favoring high-resolution MRI procedures consistently show materially higher adoption rates of multi-channel phased array technology. Market entry strategies must therefore align clinical evidence generation with payor engagement, particularly for high-cost specialty coils.
-
OEM compatibility validation. Third-party coils without validated OEM compatibility face adoption friction, even when offering superior economics. Investment in cross-platform validation and formal OEM partnerships is a strategic gating item for scale.
What the PW Consulting report delivers — practical, operational intelligence
Our report is designed for executives who must act in 2026 and beyond. It includes:
-
Market sizing and forecast to 2032 with scenario analyses calibrated to technology adoption curves and reimbursement sensitivity.
-
Tactical go‑to‑market playbooks for OEMs, independents, and contract manufacturers covering channel strategies, service bundling, and pricing models.
-
Regulatory readiness checklists and timelines for common 510(k) and CE pathways, including recommendations for clinical validation trials tailored to specialty and high-channel arrays.
-
Supplier due diligence frameworks focusing on manufacturing quality (ISO/IEC compliance), repair/refurbishment throughput, and supply‑chain resilience.
-
Competitive profiles and capability matrices for the leading manufacturers, innovators, and contract producers — identifying white space, consolidation targets, and partnership candidates.
-
Integration blueprints for embedding phased array coil strategies into broader MRI system roadmaps, including parallel imaging algorithms and acquisition workflows.
Actionable recommendations for 2026 decision-makers
-
Prioritize platform-agnostic flexible arrays. Invest in flexible, lightweight coil families that can be validated across multiple major scanner platforms to capture the broadest clinical demand without being locked into OEM upgrade cycles.
-
Tie product development to throughput economics. Build commercial value propositions that quantify time-savings and throughput improvements for imaging centers — these metrics often beat raw SNR improvements in purchasing decisions.
-
Make regulatory readiness a market-entry condition. Allocate resources to secure clearances and compatibility validations before large-scale commercial launches; regulatory lag undermines early commercial advantage.
-
Use M&A selectively to buy capabilities, not just revenues. Target acquisitions that add unique coil architecture IP (e.g., multi-nuclear tuning, ultra-high channel designs) or that bring validated manufacturing capacity to shorten lead times.
-
Monetize aftermarket services. Create service contracts and certified refurbishment programs to stabilize revenue and increase customer lock-in.
How PW Consulting’s insight delivers strategic edge
We combine quantitative forecasting with hands-on checklists and commercial templates so clients can move from insight to execution within 90–180 days. The report’s combination of market sizing, regulatory pathway mapping, supplier scorecards, and go-to-market playbooks is intended to reduce execution risk and shorten time-to-revenue for new coil launches and partnership negotiations.
Next steps and how to access the full intelligence
This briefing is a strategic preview designed to highlight the decision points that will matter in 2026. The full PW Consulting Phased Array Coil Market report contains the underlying datasets, regional and application-level revenue tables, detailed vendor scorecards, and turnkey implementation templates that boards and corporate strategy teams use to authorize investment. For organizations preparing capital allocation, M&A mandates, or product roadmaps this year, the full report is the operational intelligence you need to move decisively.
Contact PW Consulting to request the full report, custom benchmarking, or a tailored executive briefing workshop to translate these insights into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Phased Array Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roller Reconditioning Repair Services Market to Reach USD 400.0 Million by 2032, Expanding at a 5.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Roller Reconditioning Repair Services Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research — base year 2025, forecasting 2026–2032 — delivers the actionable intelligence senior executives need to set strategy for the coming planning cycle. The roller reconditioning repair services market has expanded meaningfully over the past half-decade, growing from an estimated USD 178.5 million in 2020 to USD 268.5 million in 2025, and PW Consulting’s modeling projects continued expansion through 2032 (our scenario set tops a USD 400.0 million market under the central case). The forecast period is underpinned by a compound annual growth rate of 5.85% (2026–2032), reflecting structural demand for lifecycle extension, regulatory shifts that favor repair over replacement, and ongoing operational pressures in heavy industrial and converting sectors.
Roller Reconditioning Repair Services Market
Why this preview matters for 2026 strategic planning
-
Capital allocation: As private equity and strategic buyers evaluate industrial aftermarket targets, the market’s steady growth trajectory and resilient services margin pool make roller reconditioning an attractive adjunct to broader industrial maintenance platforms. Our report translates aggregate growth into high-conviction investment themes without exposing proprietary subsegment tables in this preview.
Roller Reconditioning Repair Services Market -
Operations and cost engineering: Manufacturers and MRO service providers face pressure to reduce downtime and material spend. Reconditioning options for rollers now present measurable TCO advantages versus replacement; the report quantifies the operating cost delta and downtime value at stake for multiple operating profiles.
Roller Reconditioning Repair Services Market -
Regulatory and sustainability positioning: Right-to-repair developments in the EU and US in 2025 accelerate demand for services that extend asset life. Firms that align service offerings with circular-economy narratives can convert compliance into commercial differentiation.
-
Supply-chain resilience: Elastomer compound availability and input-cost volatility influence service pricing and margins. Our analysis highlights where vertically integrated sourcing or strategic supplier partnerships materially reduce execution risk.
What the full report contains — practical modules for executives
-
Market sizing and forecast model (historical 2020–2025; forecast 2026–2032) with downloadable, ready-to-use scenario spreadsheets that let teams re-run forecasts under custom assumptions (price inflation, utilization, service-cycle frequency).
-
Segment architecture mapped by service type, end-user application and region — each segment contains demand drivers, margin dynamics, sensitivity to raw-material cost, and break-even points for reconditioning vs replacement. (Note: this preview omits the detailed subsegment tables; full access requires the report.)
-
Value-chain and unit-economics playbook — labor, machining, coating, testing, logistics and one-way vs returnable core flows with practical benchmarks for shop productivity and utilization targets.
-
Commercial models & service propositions — same-day regrind, mobile field service, preventative rather than reactive contracts, bundled managed-service offers that combine inspection, reconditioning and spare-core logistics.
-
Regulatory impact assessment — how right-to-repair and circular-economy policies change total addressable serviceable markets and compliance-led procurement flows.
-
Competitive landscape and company playbooks — deep profiles, capability maps, recent M&A and expansion activity, and defensive/offensive options for incumbents and new entrants.
-
M&A screen and valuation sensitivities — practical guidance for deal teams including likely synergies, integration risks and three illustrative bolt-on archetypes.
-
Operational readiness checklist — capital equipment, workforce skills, quality controls and test protocols required to scale reconditioning capacity while protecting margin and uptime guarantees.
-
Client-ready slide packs, supplier scorecards and a one-page executive summary for board-level briefings.
Competitive landscape — concise strategic read on core providers
The market remains fragmented with a mix of specialized independents and regional consolidators. The following executive snapshots (included in full in the report) summarize the strategic positioning we see across the provider set and indicate where near-term competitive action is most likely.
-
American Roller Company (Union Grove, WI) — Acquisition-driven expansion is central to their strategy. Recent moves through 2024 and 2025 have extended both capacity and sector coverage, with integration of multiple plants enabling broader service footprints and cross-selling into graphic-arts and converting customers. Their playbook is consolidation plus standardized operating procedures across sites to capture scale benefits.
-
Harwood Rubber Products, Inc. (Cuyahoga Falls, OH) — A specialist in rubber roller manufacturing and rapid-turn reconditioning, Harwood competes on same-day capability and breadth of resurfacing options for larger diameters. Their focus on speed and custom elastomer formulations is a defensive moat in time-sensitive converting and packaging segments.
-
Electro-Coatings (Berkeley, CA) — Differentiates through engineering-first services: design-to-original-spec manufacturing, testing and coatings. Their value proposition suits OEMs and precision end-users that require documented replication of original surface properties.
-
B&D Rollers (Sioux Falls, SD) — Positions as a heavy-equipment reconditioning specialist offering end-to-end shop services including precision balancing, grinding and grooving. Their emphasis on heavy-duty applications makes them a choice partner in steel and metal-processing accounts.
-
Rol-Tec, Inc. (Green Bay, WI) and AELM Roller Company — Both bring deep in-house capabilities on covering and remanufacture with strengths in custom coverings and precision machining respectively; suited for customers that prioritize long service life and documented quality assurance.
-
Roll Technology Corporation — Focused on metal core repair and shaft restoration, they fill a critical niche where mechanical integrity of cores and bearings is the limiting factor to reconditioning economics.
-
Mid American Rubber, Pinnacle Roller, Provient Industrial — These regional specialists emphasize regrinding, recovered roller programs and rapid-shop turnarounds, often serving as local partners to larger OEMs and converters.
Recent industry developments reinforce consolidation and capability-extension themes. Notably, American Roller Company’s multiyear acquisition and plant-expansion program and operational integrations through 2024–2025 have accelerated geographic reach and capability breadth across converting and graphic arts. Independents continue to compete on speed, niche engineering capabilities, or locally optimized service propositions.
Key strategic actions for 2026
-
Prioritize service-model experiments with measurable KPIs: Pilot mobile field teams, subscription inspection programs, and bundled managed-service contracts. Measure conversion rates from inspection to paid reconditioning and set unit-economics thresholds before scale-up.
-
Use M&A selectively to acquire capability gaps: Target acquisitions that provide rapid access to engineered elastomer knowledge, mobile-service fleets, or specialty machining capacity. Focus on bolt-ons that improve geographic reach or shorten lead times.
-
Secure elastomer and coating supply chains: Negotiate partnership agreements or dual-source strategies for high-performance compounds to protect margins from commodity shocks.
-
Invest in digital asset-management: Implement basic IoT and inspection-data capture across key customer sites to create demand pipelines for proactive reconditioning and to justify premium service contracts.
-
Align with sustainability and compliance narratives: Incorporate right-to-repair messaging into go-to-market collateral and pursue certifications or reporting that demonstrate life-extension impact for customers’ sustainability targets.
-
Hard-wire integration playbooks post-acquisition: Standardize quality, testing and logistics protocols to retain customer relationships and realize projected synergies quickly.
-
Prepare for workforce and training investments: Skilled technicians remain the bottleneck. Establish apprenticeship models or partnerships with technical schools to create a steady pipeline.
How to use this preview with your 2026 planning cycle
-
For corporate development teams: Use the report’s M&A screen and valuation sensitivities to size acquisition targets and model integration scenarios across three synergy cases.
-
For operations leaders: Apply the unit-economics playbook and shop-benchmark metrics to identify efficiency projects that pay back within 12–24 months.
-
For product and commercial teams: Leverage our go-to-market templates to pilot subscription and preventative-reconditioning offers, and test price architecture informed by documented downtime costs in the report.
This briefing is intentionally high-level: it demonstrates the depth and practical focus of PW Consulting’s Roller Reconditioning Repair Services Market report while preserving the detailed segment tables, company-level revenue splits and regional breakdowns for the full publication. The complete report contains the granular subsegment figures, downloadable models, supplier scorecards and client-ready slide content you will need to operationalize these insights.
To access the full dataset, company profiles, scenario models and our bespoke advisory offers that help implement the recommendations above, visit PW Consulting’s report page or contact our industrial aftermarket practice for a tailored briefing. Our team is available to run a workshop that applies the forecast scenarios directly to your asset base and service strategy for 2026.
For detailed analysis of this topic, please visit the official page: Roller Reconditioning Repair Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Multi-Turn Potentiometer Market Set to Expand at a 3.4% CAGR Through 2032
By pmarketresearch, 2026-07-13
Multi Turn Potentiometer Market — Strategic Outlook for 2026: PW Consulting Industry Brief
As supply-chain volatility and application-specific reliability requirements reshape component sourcing strategies, PW Consulting’s latest Multi Turn Potentiometer Market study provides an executive-grade roadmap for 2026 decision-makers. Anchored on a 2025 base year and a forward-looking 2026–2032 forecast horizon, the report combines granular supplier intelligence, scenario-driven financial modeling, and executable commercial playbooks designed to convert market turbulence into sustainable advantage.
Multi Turn Potentiometer Market
Why this market matters to your 2026 strategy
-
Defensive purchasing and margin protection: The multi turn potentiometer market — measured in USD Million — not only returned to growth after pandemic-era fluctuations but is projected to expand through the coming planning cycle at a compound annual growth rate (CAGR) of 3.4% (2026–2032). This moderate but persistent growth trajectory means procurement and product teams must balance cost discipline with ongoing demand from high-reliability verticals.
Multi Turn Potentiometer Market -
Technology choice drives downstream outcomes: Product choices among wirewound, hybrid and conductive-plastic technologies determine lifecycle costs, failure modes, and qualification timelines for customers in industrial control, medical, and aerospace segments. Engineering trade-offs made in 2026 will affect field reliability and service economics for several years.
Multi Turn Potentiometer Market -
Supply-side risk is evolving into strategic risk: Raw-material pressure — notably on copper and precious metals used in resistive elements and contact plating — has become a recurring earnings headwind for manufacturers and OEMs alike, with material-price shocks altering supplier cost curves and lead-time behavior.
Macro snapshot (what the numbers tell us)
PW Consulting’s topline market sizing shows the sector passing the USD 200 Million mark in the mid-2020s, with the market size in 2025 serving as the analytical baseline for forward scenarios. Our deterministic forecast points to continued expansion in 2026 and beyond, reaching a higher absolute level by 2032 under the base case. The 3.4% CAGR embedded in the model reflects a market that is mature, end-market-driven, and sensitive to component substitution and manufacturing cost dynamics.
Immediate industry dynamics to watch in 2026
-
Raw-material inflation: Independent datasets show copper prices surged to record levels in early 2026, with intraday spikes and sustained increases that materially affect resistive-wire and contact-plating costs. Precious-metal prices used in plated contacts have also trended higher. Meanwhile, raw-material price indices for passive electronic components recorded notable year-over-year increases through late 2025. These inputs should be treated as persistent cost drivers rather than temporary blips in 2026 budgeting exercises.
-
Supply concentration and supplier behavior: The market exhibits moderate concentration at the top, with the combined presence of multiple global legacy players and specialty regional vendors. This structure creates bargaining asymmetries during raw-material shocks and leads to differentiated service levels across geographies.
-
Demand composition is bifurcating: High-reliability, low-volume segments (medical, aerospace/defense) continue to prize precision and qualification pedigree, while certain industrial and test applications show sensitivity to unit costs and miniaturization. The diverging needs create opportunities for differential product strategies and pricing segmentation.
What PW Consulting’s report contains — operational, not ornamental
-
Market models and validated forecasts: Dynamic 2020–2032 datasets, with base-year calibration, sensitivity testing against raw-material shocks, and three scenario forks (base, downside, upside) to stress-test capital allocation decisions.
-
Supplier heatmaps and scorecards: Comparative matrices that rate vendors on reliability, lead time, vertical integration, pricing flexibility, and qualification support — intended for procurement negotiation playbooks.
-
Cost-to-serve and margin impact tools: Line-item cost models linking copper/precious-metal inputs to finished-goods pricing and gross-margin outcomes under alternate hedging and pass-through strategies.
-
Product and engineering playbooks: Guidance on material substitution (where feasible), hybrid vs. conductive-plastic trade-offs, miniaturization pathways, and qualification time reductions for medical and aerospace approvals.
-
M&A and partnership screens: A prioritized list of acquisition targets and JV profiles based on technology fit, geographic fill-ins, and route-to-market synergies — built to accelerate inorganic consolidation or diversify supply exposure without overpaying.
-
Go-to-market and commercial tactics: Segmented pricing frameworks, inventory strategy options (JIT vs. safety-stock overlays), and after-sales/service propositions that protect ASPs in price-competitive verticals.
-
Regulatory and procurement checklist: Action items for OEMs subject to defense and medical certifications, including recommended test protocols and supplier audit scopes to compress time-to-field while maintaining compliance.
Competitive landscape — what leading vendors are doing (and what to expect)
The market’s competitive set blends global component incumbents with specialized regional vendors. Several themes emerged from our benchmarking:
-
Bourns Inc. (Riverside, CA) — breadth and customization: Bourns’ extensive product roster across multiple element technologies and turn configurations positions it as a go-to for OEMs needing rapid qualification variants and custom engineering. Expect continued emphasis on configurable modules and expanded support for high-reliability medical and industrial programs.
-
Vishay Intertechnology / Spectrol (Malvern, PA) — precision in harsh environments: Spectrol’s wirewound precision lines and high-linearity claims make it a preferred supplier where environmental robustness matters. Their value proposition will center on certified, off-the-shelf precision devices for demanding control systems.
-
TT Electronics (Woking, UK) — hybrid solutions and aerospace alignment: TT Electronics has invested in hybrid-technology potentiometers and 10-turn designs used in heavy-duty industrial and aerospace programs. Expect TT to continue leveraging defense and aerospace certifications as entry barriers for competitors.
-
ETI Systems (Carlsbad, CA) and Sensor Systems LLC (USA) — niche precision and customization: These players highlight the persistent demand for bespoke solutions and small-batch, high-reliability manufacturing. Their agility makes them attractive partners for OEMs with specialized servo, valve actuator, or military programs.
-
MEGATRON (Germany), SENTOP (Shanghai) and Althen (Netherlands) — regional strengths and miniaturization: European and Asia-based vendors continue to push miniaturized and cost-optimized designs, serving localized industrial markets and price-sensitive OEM programs. Althen’s claims around ultra-compact 10-turn devices suggest product innovation at the part-level remains a competitive lever.
-
Honeywell — systems-level leverage: As a diversified systems supplier, Honeywell’s multi-turn offerings are often bundled into broader position-sensing and control platforms, creating stickiness with large OEMs and system integrators.
From a corporate-strategy lens, the top-tier players concentrate on reliability, product breadth, and certification-led differentiation, while smaller vendors compete on agility, customization, and cost. This mix supports a market in which the top few firms control a meaningful share but mid-tier and regional specialists retain influence in niche applications.
Strategic implications and recommended actions for 2026
-
Procurement: Implement a two-track supplier strategy — secure long-term, partially hedged contracts with primary suppliers for critical products while qualifying agile regional suppliers as secondary sources. Model the financial impact of copper-price thresholds that would trigger alternative sourcing or price renegotiations.
-
Product management: Prioritize design reviews for material-intense variants and accelerate substitution where reliability trade-offs are acceptable. For medical/aerospace programs, invest in co-engineering to shorten qualification cycles and justify price premiums.
-
Operations: Reassess inventory policies to protect production continuity against raw-material spikes — targeted safety-stock or forward-buying of high-impact inputs can be cheaper than repeated line stoppages.
-
Corporate development: Use targeted M&A to acquire manufacturing scale or specialized capabilities (miniaturization, hybrid technology, custom resistive elements) to buffer margin exposure and expand served markets.
-
Commercial: Rework pricing playbooks to include material surcharge clauses, tiered service SLAs, and validated quality metrics that justify premium pricing in reliability-sensitive channels.
What you won’t find in this brief — and why
To preserve the strategic value of our primary research, granular regional/application split tables, product-type revenue breakdowns, and contract-level supplier pricing models are reserved for the full PW Consulting report. This “teaser” is designed to give you the actionable macro view and the decision checklist you need to start 2026 planning today; the comprehensive datasets and scenario files are available on the report landing page for clients who require the full analytical stack.
Next steps
For procurement heads, product chiefs, and corporate development teams seeking to translate the market outlook into executable plans this year, PW Consulting can deliver a tailored briefing package: customized supplier scorecards, a copper-price stress test calibrated to your BOM, or a 90-day supplier risk remediation plan. Contact PW Consulting to schedule a strategy workshop and obtain the full report with downloadable datasets, supplier benchmarking deliverables, and the scenario-sensitivity models that underpin our 2026 recommendations.
For detailed analysis of this topic, please visit the official page: Multi Turn Potentiometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com