

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Phased Array Coil Market to Expand at a 6.32% CAGR Through 2032

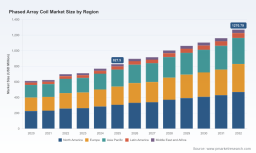
Phased Array Coil Market Outlook 2026: Strategic Priorities for the Next Wave of MRI Innovation
PW Consulting’s latest Phased Array Coil Market report positions industry leaders and investors to make informed, high-conviction decisions in 2026. Our analysis shows the global phased array coil market expanding from an estimated USD 827.5 million in 2025 to roughly USD 1.27 billion by 2032, reflecting a compound annual growth rate (CAGR) of 6.32% across the 2026–2032 forecast window. For executives deciding where to allocate R&D, M&A, and commercial resources this year, the report crystallizes the practical levers that separate winning strategies from marginal plays.
Phased Array Coil Market
Why 2026 is a Pivotal Planning Year
Medical imaging OEMs, contract manufacturers, and specialty coil innovators face converging pressures in 2026: accelerating clinical demand for higher-resolution, faster throughput MRI; tightening regulatory pathways that emphasize cross-vendor compatibility and safety; and margin pressure from the emergence of third‑party and refurbished coil supply. Our research finds that these forces create asymmetric opportunities for organizations that pair technical differentiation (high-channel arrays, flexible form factors, multi-nuclear capability) with disciplined commercialization — including validated OEM integrations, regulatory preparedness, and targeted reimbursement strategies.
Phased Array Coil Market
Core market dynamics and strategic implications
-
Structural growth, underpinned by clinical adoption. The market’s mid-single-digit CAGR signals steady, sustainable demand rather than a hype-driven spike. That supports multi-year investments in product families (e.g., high-density head & neck, large-bore body arrays) but cautions against one-off, capital-intensive gambits without clear upgrade or service revenue models.
Phased Array Coil Market -
Differentiation through ergonomics and workflow. Flexible, lightweight designs that improve patient comfort and reduce setup time are proving to be as commercially decisive as marginal SNR gains. In 2026, buyers will increasingly prize total-cost-of-ownership calculations that include throughput and technician efficiency.
-
Regulatory and compatibility as market access gates. Class II device classification, IEC safety standards, and OEM compatibility validation are non-negotiable. Companies with mature regulatory dossiers and cross-platform compatibility programs will secure preferred-supplier status in hospital systems and consolidated imaging networks.
-
Service & refurbishment as margin anchors. Contract manufacturing and repair/refurbishment services continue to compress hardware margins but create predictable aftermarket revenue. Integrating refurbishment and service into commercial offers can materially improve lifetime value.
Competitive landscape: incumbents, specialists, and new entrants
The market remains populated by a mix of large OEMs, dedicated coil specialists, contract manufacturers, and agile start-ups. Each cohort brings a distinct strategic play:
-
Established OEMs (e.g., Siemens Healthineers, GE HealthCare, Philips, Canon). These players couple integrated coil portfolios with platform-level advantages (pulse sequence optimization, reconstruction pipelines). Their strength lies in bundled upgrades, field service networks, and channel reach; however, their product roadmaps are constrained by broader system development cycles.
-
Specialty coil innovators (e.g., RAPID Biomedical, NORAS, InkSpace Imaging, Magnetica). These companies move fast on technical differentiation — dual-tuned arrays, ultra-light flexible designs, and research-grade high-channel count coils — and increasingly secure regulatory clearances that open clinical markets. Their agility allows them to capture niche clinical use-cases and to partner with academic centers to validate performance.
-
OEM-aligned challengers and integrated Chinese suppliers (e.g., United Imaging). Combining scale manufacturing with aggressive product portfolios, these entrants are accelerating price/performance competition in certain markets and expanding channel options globally.
-
Contract manufacturers and refurbishers (e.g., ScanMed). Offering ISO-certified production and 510(k)-capable manufacturing, these firms are essential partners for both OEMs and independents aiming to optimize cost structures and accelerate time-to-market.
Recent product and regulatory developments underscore market momentum. Notable examples include new flexible pediatric arrays and lightweight high-channel clinical coils that obtained regulatory clearances in 2025–2026, as well as dual‑tuned and non-proton arrays that broaden clinical and research applications. These developments create tactical opportunities for partnerships, label-expansion plays, and platform co-development.
Regulatory, reimbursement, and safety considerations
-
Regulatory framework. Phased array coils fall under established medical device frameworks (notably 510(k) pathways in the U.S.) and must conform to MRI safety standards (IEC 60601 series). Manufacturers should anticipate increasing scrutiny around interoperability, labeling for parallel imaging use, and SAR management in high‑channel configurations.
-
Reimbursement influence on adoption. Regions with reimbursement policies favoring high-resolution MRI procedures consistently show materially higher adoption rates of multi-channel phased array technology. Market entry strategies must therefore align clinical evidence generation with payor engagement, particularly for high-cost specialty coils.
-
OEM compatibility validation. Third-party coils without validated OEM compatibility face adoption friction, even when offering superior economics. Investment in cross-platform validation and formal OEM partnerships is a strategic gating item for scale.
What the PW Consulting report delivers — practical, operational intelligence
Our report is designed for executives who must act in 2026 and beyond. It includes:
-
Market sizing and forecast to 2032 with scenario analyses calibrated to technology adoption curves and reimbursement sensitivity.
-
Tactical go‑to‑market playbooks for OEMs, independents, and contract manufacturers covering channel strategies, service bundling, and pricing models.
-
Regulatory readiness checklists and timelines for common 510(k) and CE pathways, including recommendations for clinical validation trials tailored to specialty and high-channel arrays.
-
Supplier due diligence frameworks focusing on manufacturing quality (ISO/IEC compliance), repair/refurbishment throughput, and supply‑chain resilience.
-
Competitive profiles and capability matrices for the leading manufacturers, innovators, and contract producers — identifying white space, consolidation targets, and partnership candidates.
-
Integration blueprints for embedding phased array coil strategies into broader MRI system roadmaps, including parallel imaging algorithms and acquisition workflows.
Actionable recommendations for 2026 decision-makers
-
Prioritize platform-agnostic flexible arrays. Invest in flexible, lightweight coil families that can be validated across multiple major scanner platforms to capture the broadest clinical demand without being locked into OEM upgrade cycles.
-
Tie product development to throughput economics. Build commercial value propositions that quantify time-savings and throughput improvements for imaging centers — these metrics often beat raw SNR improvements in purchasing decisions.
-
Make regulatory readiness a market-entry condition. Allocate resources to secure clearances and compatibility validations before large-scale commercial launches; regulatory lag undermines early commercial advantage.
-
Use M&A selectively to buy capabilities, not just revenues. Target acquisitions that add unique coil architecture IP (e.g., multi-nuclear tuning, ultra-high channel designs) or that bring validated manufacturing capacity to shorten lead times.
-
Monetize aftermarket services. Create service contracts and certified refurbishment programs to stabilize revenue and increase customer lock-in.
How PW Consulting’s insight delivers strategic edge
We combine quantitative forecasting with hands-on checklists and commercial templates so clients can move from insight to execution within 90–180 days. The report’s combination of market sizing, regulatory pathway mapping, supplier scorecards, and go-to-market playbooks is intended to reduce execution risk and shorten time-to-revenue for new coil launches and partnership negotiations.
Next steps and how to access the full intelligence
This briefing is a strategic preview designed to highlight the decision points that will matter in 2026. The full PW Consulting Phased Array Coil Market report contains the underlying datasets, regional and application-level revenue tables, detailed vendor scorecards, and turnkey implementation templates that boards and corporate strategy teams use to authorize investment. For organizations preparing capital allocation, M&A mandates, or product roadmaps this year, the full report is the operational intelligence you need to move decisively.
Contact PW Consulting to request the full report, custom benchmarking, or a tailored executive briefing workshop to translate these insights into a 90‑day action plan.
For detailed analysis of this topic, please visit the official page: Phased Array Coil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com