

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Liquid Phenolic Resin Market Reaches USD 7,411.35 Million in 2025, Forecast to Expand at 5.01% CAGR Through 2026–2032

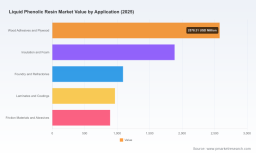
Liquid Phenolic Resin Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive snapshot
The global liquid phenolic resin market is entering 2026 from a position of steady expansion and strategic complexity. After reaching USD 7,411.35 Million in 2025, our market model projects growth to approximately USD 10,435.47 Million by 2032 — an expected compound annual growth rate (CAGR) of 5.01% across the 2026–2032 forecast window. The 2026 inflection year matters: supply‑chain shocks, regulatory tightening, and accelerating sustainability requirements will force executives to make investment and sourcing decisions now that will determine competitiveness through the end of the decade.
Liquid Phenolic Resin Market
Why this market matters to 2026 decision-makers
-
Cross‑sector exposure. Phenolic resins underpin products across wood adhesives, insulation, foundry binders, laminates and friction materials. Executive choices in procurement, product development and capacity planning ripple across multiple value chains.
Liquid Phenolic Resin Market -
Feedstock and price sensitivity. Phenol — the principal upstream feedstock — has shown renewed volatility, with Northeast Asia spot pricing signaling tighter market balance in early 2026. These moves materially affect margins for resin manufacturers and their customers.
Liquid Phenolic Resin Market -
Regulatory and sustainability pressure. Stricter formaldehyde emission standards and chemical bans introduced in recent years raise compliance costs, while certification regimes (e.g., ISCC PLUS) are already influencing buyer preferences in Europe and other advanced markets.
-
Consolidation and concentration. Market concentration metrics show that the leading firms capture a meaningful, but not overwhelming, share of the market, leaving room for regional champions, specialized toll manufacturers and consolidation-driven M&A.
Recent market signals to act on in 2026
-
Upstream cost pressure: Northeast Asia phenol spot prices reached about USD 1.01/kg in March 2026, reflecting maintenance outages and firmer resin demand. In China, local phenol pricing also moved materially higher in early 2026 — a near‑term signal for rising operating costs across the supply chain.
-
Regulatory tightening: Updates to formaldehyde emission standards and post‑2025 chemical restriction regimes (including bans impacting sensitive food‑contact uses) increase compliance spending and accelerate demand for lower‑emission resin chemistries.
-
Certification and differentiation: Leading producers are seeking sustainability certifications and circular feedstock pathways, with recent ISCC PLUS achievements demonstrating a commercial route to premium positioning in Europe.
-
Trade and tariff risks: Tariff measures introduced in 2025 continue to affect transpacific flows and sourcing economics, with duty exposure on some chemical and engineered-product imports reaching materially high levels in some jurisdictions.
Competitive landscape — what the leading players signal
The industry is characterized by a mix of global chemical majors, regional specialists and custom/toll producers. The competitive field includes vertically integrated producers capable of leveraging chemical integration and scale, European specialists with dense regional manufacturing footprints, and agile contract manufacturers that serve niche adhesive and composite needs.
-
Global integrated players (examples): Large chemical firms with broad downstream portfolios use feedstock scale and product breadth to defend volume and margin. Their competitive advantages include raw‑material hedging, integrated logistics and the ability to fund decarbonization investments at scale.
-
Europe‑focused specialists: Companies focused in Europe leverage regulatory experience, faster product approval cycles for low‑emission formulations, and deep relationships in construction and insulation value chains.
-
Asian capacity and cost players: Manufacturers with strong Asian production footprints benefit from lower operating costs and proximity to high‑growth end markets, but they are increasingly exposed to tariff and raw‑material price tailwinds.
-
Custom/toll and performance resin houses: These players serve formulation‑sensitive customers, offering ISO‑driven quality, small‑batch capabilities and rapid development cycles — attractive to downstream customers pursuing differentiation or rapid qualification timelines.
For buyers and investors, understanding the strategic posture of each competitor — from sustainability credentials to toll‑manufacturing flexibility and geographic exposure — is the basis for evaluating partnership, J‑V or acquisition targets in 2026.
Report highlights — what PW Consulting provides (practical content)
Our full Liquid Phenolic Resin Market report combines quantitative forecasting with hands‑on strategic tools tailored for 2026 decisions. Key deliverables include:
-
A validated market model and topline forecasts through 2032, including scenario runs to stress‑test demand under alternative macro and regulatory environments.
-
Feedstock sensitivity analysis that translates phenol and energy price moves into margin and pricing impacts for producers and large buyers.
-
Regulatory impact assessment quantifying compliance cost ranges and the commercial premium for low‑emission, certified products across major regulatory regimes.
-
Supplier scorecards and a commercial playbook for procurement: capability matrices, qualification timelines, and negotiation levers for captive vs. toll supply strategies.
-
M&A and partnership framework: target archetypes, value‑creation levers, and integration risk checklists mapped to typical deal structures in resin and adjacent value chains.
-
Go‑to‑market strategies for resin formulators and downstream OEMs to monetize sustainability claims, capture retrofit demand in building materials, and commercialize low‑emission resin grades.
Strategic recommendations for 2026
-
Lock in flexible feedstock arrangements: Negotiate contracts with indexed pricing bands, capacity release options and shared upside mechanisms to mitigate short‑term phenol volatility.
-
Prioritize regulatory‑ready product development: Accelerate low‑emission and formaldehyde‑reduced formulations; secure third‑party certifications where they materially influence procurement decisions.
-
Expand toll and contract manufacturing partnerships: For companies seeking agility without heavy capital outlays, toll arrangements offer speed to market and capacity buffering versus outright greenfield expansion.
-
Use tariffs and trade dynamics to rationalize regional footprints: Revisit plant location strategies and dual‑sourcing to minimize tariff exposure and reduce lead‑time risk in critical markets.
-
Targeted M&A: For buyers seeking scale or technology, look for regional champions with strong customer relationships and specialty product portfolios that can be scaled globally.
-
Deploy financial hedges and margin protection: Consider commodity hedges and commercial instruments to stabilize margins while pursuing premium product positioning.
Risk map — what to monitor through 2026
-
Upstream shocks: Maintenance outages or supply disruptions at phenol producers can rapidly tighten margins; procurement teams must build early warning indicators into S&OP processes.
-
Regulatory shifts: Sudden regulatory updates or enforcement actions on formaldehyde and related chemicals can create near‑term compliance costs and product relabeling burdens.
-
Trade policy volatility: Rapid tariff changes will continue to influence regional economics and require adaptive sourcing strategies.
-
Technology and substitution: Advances in alternative binders or bio‑based chemistries could accelerate premium erosion for conventional phenolic grades if incumbent firms are late to respond.
How PW Consulting’s report supports immediate action
For boards, strategy teams and commercial leaders preparing 2026 budgets and capex plans, the report provides the tactical inputs needed to close the gap between signal and action. Clients will receive downloadable datasets, supplier scorecards, scenario tools and a prioritized roadmap that translates market projections and regulatory scenarios into executable decisions with time‑bound milestones.
Final note — trailer
This preview outlines the strategic forces reshaping the liquid phenolic resin market as firms position for 2026 and beyond. The full PW Consulting report contains the granular segmentation, regional flows, application breakouts and actionable models you need to translate these trends into winning commercial and investment decisions. Request the comprehensive dossier to access the proprietary datasets, detailed supplier analyses and the recommended 90‑day action plan tailored to your company profile.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com