

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Multi-Turn Potentiometer Market Set to Expand at a 3.4% CAGR Through 2032

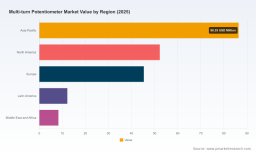
Multi Turn Potentiometer Market — Strategic Outlook for 2026: PW Consulting Industry Brief
As supply-chain volatility and application-specific reliability requirements reshape component sourcing strategies, PW Consulting’s latest Multi Turn Potentiometer Market study provides an executive-grade roadmap for 2026 decision-makers. Anchored on a 2025 base year and a forward-looking 2026–2032 forecast horizon, the report combines granular supplier intelligence, scenario-driven financial modeling, and executable commercial playbooks designed to convert market turbulence into sustainable advantage.
Multi Turn Potentiometer Market
Why this market matters to your 2026 strategy
-
Defensive purchasing and margin protection: The multi turn potentiometer market — measured in USD Million — not only returned to growth after pandemic-era fluctuations but is projected to expand through the coming planning cycle at a compound annual growth rate (CAGR) of 3.4% (2026–2032). This moderate but persistent growth trajectory means procurement and product teams must balance cost discipline with ongoing demand from high-reliability verticals.
Multi Turn Potentiometer Market -
Technology choice drives downstream outcomes: Product choices among wirewound, hybrid and conductive-plastic technologies determine lifecycle costs, failure modes, and qualification timelines for customers in industrial control, medical, and aerospace segments. Engineering trade-offs made in 2026 will affect field reliability and service economics for several years.
Multi Turn Potentiometer Market -
Supply-side risk is evolving into strategic risk: Raw-material pressure — notably on copper and precious metals used in resistive elements and contact plating — has become a recurring earnings headwind for manufacturers and OEMs alike, with material-price shocks altering supplier cost curves and lead-time behavior.
Macro snapshot (what the numbers tell us)
PW Consulting’s topline market sizing shows the sector passing the USD 200 Million mark in the mid-2020s, with the market size in 2025 serving as the analytical baseline for forward scenarios. Our deterministic forecast points to continued expansion in 2026 and beyond, reaching a higher absolute level by 2032 under the base case. The 3.4% CAGR embedded in the model reflects a market that is mature, end-market-driven, and sensitive to component substitution and manufacturing cost dynamics.
Immediate industry dynamics to watch in 2026
-
Raw-material inflation: Independent datasets show copper prices surged to record levels in early 2026, with intraday spikes and sustained increases that materially affect resistive-wire and contact-plating costs. Precious-metal prices used in plated contacts have also trended higher. Meanwhile, raw-material price indices for passive electronic components recorded notable year-over-year increases through late 2025. These inputs should be treated as persistent cost drivers rather than temporary blips in 2026 budgeting exercises.
-
Supply concentration and supplier behavior: The market exhibits moderate concentration at the top, with the combined presence of multiple global legacy players and specialty regional vendors. This structure creates bargaining asymmetries during raw-material shocks and leads to differentiated service levels across geographies.
-
Demand composition is bifurcating: High-reliability, low-volume segments (medical, aerospace/defense) continue to prize precision and qualification pedigree, while certain industrial and test applications show sensitivity to unit costs and miniaturization. The diverging needs create opportunities for differential product strategies and pricing segmentation.
What PW Consulting’s report contains — operational, not ornamental
-
Market models and validated forecasts: Dynamic 2020–2032 datasets, with base-year calibration, sensitivity testing against raw-material shocks, and three scenario forks (base, downside, upside) to stress-test capital allocation decisions.
-
Supplier heatmaps and scorecards: Comparative matrices that rate vendors on reliability, lead time, vertical integration, pricing flexibility, and qualification support — intended for procurement negotiation playbooks.
-
Cost-to-serve and margin impact tools: Line-item cost models linking copper/precious-metal inputs to finished-goods pricing and gross-margin outcomes under alternate hedging and pass-through strategies.
-
Product and engineering playbooks: Guidance on material substitution (where feasible), hybrid vs. conductive-plastic trade-offs, miniaturization pathways, and qualification time reductions for medical and aerospace approvals.
-
M&A and partnership screens: A prioritized list of acquisition targets and JV profiles based on technology fit, geographic fill-ins, and route-to-market synergies — built to accelerate inorganic consolidation or diversify supply exposure without overpaying.
-
Go-to-market and commercial tactics: Segmented pricing frameworks, inventory strategy options (JIT vs. safety-stock overlays), and after-sales/service propositions that protect ASPs in price-competitive verticals.
-
Regulatory and procurement checklist: Action items for OEMs subject to defense and medical certifications, including recommended test protocols and supplier audit scopes to compress time-to-field while maintaining compliance.
Competitive landscape — what leading vendors are doing (and what to expect)
The market’s competitive set blends global component incumbents with specialized regional vendors. Several themes emerged from our benchmarking:
-
Bourns Inc. (Riverside, CA) — breadth and customization: Bourns’ extensive product roster across multiple element technologies and turn configurations positions it as a go-to for OEMs needing rapid qualification variants and custom engineering. Expect continued emphasis on configurable modules and expanded support for high-reliability medical and industrial programs.
-
Vishay Intertechnology / Spectrol (Malvern, PA) — precision in harsh environments: Spectrol’s wirewound precision lines and high-linearity claims make it a preferred supplier where environmental robustness matters. Their value proposition will center on certified, off-the-shelf precision devices for demanding control systems.
-
TT Electronics (Woking, UK) — hybrid solutions and aerospace alignment: TT Electronics has invested in hybrid-technology potentiometers and 10-turn designs used in heavy-duty industrial and aerospace programs. Expect TT to continue leveraging defense and aerospace certifications as entry barriers for competitors.
-
ETI Systems (Carlsbad, CA) and Sensor Systems LLC (USA) — niche precision and customization: These players highlight the persistent demand for bespoke solutions and small-batch, high-reliability manufacturing. Their agility makes them attractive partners for OEMs with specialized servo, valve actuator, or military programs.
-
MEGATRON (Germany), SENTOP (Shanghai) and Althen (Netherlands) — regional strengths and miniaturization: European and Asia-based vendors continue to push miniaturized and cost-optimized designs, serving localized industrial markets and price-sensitive OEM programs. Althen’s claims around ultra-compact 10-turn devices suggest product innovation at the part-level remains a competitive lever.
-
Honeywell — systems-level leverage: As a diversified systems supplier, Honeywell’s multi-turn offerings are often bundled into broader position-sensing and control platforms, creating stickiness with large OEMs and system integrators.
From a corporate-strategy lens, the top-tier players concentrate on reliability, product breadth, and certification-led differentiation, while smaller vendors compete on agility, customization, and cost. This mix supports a market in which the top few firms control a meaningful share but mid-tier and regional specialists retain influence in niche applications.
Strategic implications and recommended actions for 2026
-
Procurement: Implement a two-track supplier strategy — secure long-term, partially hedged contracts with primary suppliers for critical products while qualifying agile regional suppliers as secondary sources. Model the financial impact of copper-price thresholds that would trigger alternative sourcing or price renegotiations.
-
Product management: Prioritize design reviews for material-intense variants and accelerate substitution where reliability trade-offs are acceptable. For medical/aerospace programs, invest in co-engineering to shorten qualification cycles and justify price premiums.
-
Operations: Reassess inventory policies to protect production continuity against raw-material spikes — targeted safety-stock or forward-buying of high-impact inputs can be cheaper than repeated line stoppages.
-
Corporate development: Use targeted M&A to acquire manufacturing scale or specialized capabilities (miniaturization, hybrid technology, custom resistive elements) to buffer margin exposure and expand served markets.
-
Commercial: Rework pricing playbooks to include material surcharge clauses, tiered service SLAs, and validated quality metrics that justify premium pricing in reliability-sensitive channels.
What you won’t find in this brief — and why
To preserve the strategic value of our primary research, granular regional/application split tables, product-type revenue breakdowns, and contract-level supplier pricing models are reserved for the full PW Consulting report. This “teaser” is designed to give you the actionable macro view and the decision checklist you need to start 2026 planning today; the comprehensive datasets and scenario files are available on the report landing page for clients who require the full analytical stack.
Next steps
For procurement heads, product chiefs, and corporate development teams seeking to translate the market outlook into executable plans this year, PW Consulting can deliver a tailored briefing package: customized supplier scorecards, a copper-price stress test calibrated to your BOM, or a 90-day supplier risk remediation plan. Contact PW Consulting to schedule a strategy workshop and obtain the full report with downloadable datasets, supplier benchmarking deliverables, and the scenario-sensitivity models that underpin our 2026 recommendations.
For detailed analysis of this topic, please visit the official page: Multi Turn Potentiometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com