

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
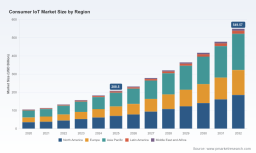
PW Consulting: Consumer IoT Market to Soar to USD 549.6 Billion by 2032, Driven by a 14.85% CAGR

Consumer IoT Market 2026: A Strategic Preview — Why PW Consulting’s New Report Is Mission-Critical for Executive Decision-Making
As consumer IoT accelerates from novelty to necessity, 2026 will be a pivot year for companies building products, platforms, and ecosystems. PW Consulting’s forthcoming Consumer IoT Market report synthesizes five years of historical evidence and robust forecasting to translate market momentum into executable corporate strategy. This preview summarizes the report’s macro posture, competitive takeaways, regulatory inflection points, and the concrete actions senior leaders should prioritize when allocating capital, shaping partnerships, and designing product roadmaps for 2026.
Consumer Iot Market
Macro view: growth trajectory and market structure
The consumer IoT market has moved from early expansion into rapid scale. Our model — which uses 2020–2025 as the historical baseline, takes 2025 as the base year, and projects through 2026–2032 — shows continued strong expansion at a compound annual growth rate (CAGR) of 14.85%. This pace positions the market to more than double over the forecast window, underscoring a structural shift in consumer behavior, device affordability, and network capability.
Consumer Iot Market
Equally important to growth is market structure. Market concentration metrics indicate a market that is neither monopolized nor atomized: the three-largest players account for a meaningful but not dominant share, and the top five consolidate under 50% of market revenue. In practice, this means incumbents retain strong influence through platform and distribution advantages, while a broad field of innovators can still win share through differentiated product features, pricing, and vertical specialization.
Consumer Iot Market
What the report delivers — practical, transaction-ready intelligence
- Proprietary demand model calibrated to real-world shipments and channel data, delivering topline forecasts and scenario sensitivities for 2026 planning cycles.
- Executive dashboards and KPI trackers tailored for product, corporate development, and regulatory teams (including unit economics, TAM/SAM estimates, and scenario-driven revenue paths).
- Vendor benchmarking and ecosystem maps that show platform interdependencies, interoperability readiness, and partner adjacency opportunities.
- Go-to-market playbooks with tested channel strategies for direct-to-consumer, retail, carrier bundles, and subscription conversions.
- Regulatory compliance checklists and impact assessments tied to major jurisdictions and upcoming mandates.
- M&A and partnership scorecards with shortlists of high-value targets by capability (edge AI, low-power connectivity, secure provisioning, and cloud orchestration).
- Supply-chain stress-tests and component-cost sensitivity analyses to model margin compression or restoration under different chipset and logistics scenarios.
Each section combines quantitative modeling with practitioner-focused recommendations — not academic theory. The intent is to arm leadership with both the numbers and the operational playbook to make swift, defensible decisions in 2026.
Competitive landscape: leaders, challengers, and what matters in 2026
The consumer IoT competitive map is shaped by platform control, brand trust, retail reach, and cost-to-serve. Ten companies in particular illustrate strategic archetypes executives should study:
- Amazon — Continues to leverage Alexa and retail scale to convert device ownership into recurring services. Recent wearable launches demonstrate a push to embed voice and ambient intelligence across consumer touchpoints. Strategic implication: incumbents should assess voice-as-a-service agreements and distribution partnerships to remain competitive on convenience and recurring revenue.
- Google — Focused on platform interoperability and ecosystem coherence; its rollout of Matter 1.3 support underscores a tactical emphasis on reducing friction for cross-vendor experiences. Strategic implication: prioritize Matter certification and compatibility investments to avoid being left out of bundled smart-home offers.
- Apple — Maintains a premium, privacy-centric approach. Expansion of HomeKit integrations signals a dual strategy: protect the walled garden while selectively enabling third-party experiences. Strategic implication: firms targeting premium segments must demonstrate privacy-first data handling to partner with or compete against Apple-led experiences.
- Samsung — Plays the ecosystem aggregator role — appliances to wearables — and recent certification moves for next-gen Wi‑Fi show readiness for higher-throughput, lower-latency use cases. Strategic implication: look for partnership opportunities around appliance integration and connectivity upgrades.
- Philips (Signify) , Sonos , and other appliance/audio incumbents — Hold product leadership in specific verticals; their ability to integrate with platform leaders will determine growth in bundled home solutions.
- iRobot — Product-led differentiation via advanced onboard AI and navigation is extending lifecycle value and aftermarket services; robotics remains a bellwether for consumer willingness to pay for autonomy.
- Arlo, Wyze, TP‑Link — Represent competing strategies across premium-to-value: Arlo emphasizes advanced features and cloud services; Wyze competes on price and accessibility; TP‑Link focuses on distribution and connectivity bundles. Strategic implication: companies should map where they want to play on the value-performance axis and design channel & support economics accordingly.
Taken together, these players show that future winners will combine platform reach, certification/standards compliance, and a flexible monetization mix (one-time device revenue, subscriptions, services). The report provides a vendor-by-vendor heatmap that ranks opportunity windows and partnership value.
Regulatory and standards landscape — immediate priorities
Regulation and standards will materially shape product roadmaps and GTM strategies in 2026:
- EU cybersecurity requirements for connected devices introduce compliance timelines that will affect product certification cost and time-to-market. Companies selling into Europe must bake compliance into 2026 roadmaps.
- US federal procurement standards and state-level security laws (e.g., unique default password requirements and vulnerability disclosure mandates) create baseline expectations that are increasingly global de facto norms.
- Broad industry adoption of the Matter protocol and accelerated certification counts mean interoperability is becoming table stakes for consumer IoT kits sold through mainstream channels.
- Connectivity evolution (Wi‑Fi 6E/7 and advanced low-power chipsets) is changing hardware BOM dynamics; marginal increases in chipset cost must be weighed against user experience and long-term ARPU upside.
Our report includes a jurisdictional impact matrix and a compliance-cost model to help legal, product, and operations teams budget and sequence remediation work through 2026.
Strategic implications — a prioritized 2026 action list for executives
- Hardwire interoperability and certification: Make Matter and dominant platform compatibility non-negotiable for new SKUs. Prioritize cross-certification paths that reduce integration friction for retail and carrier bundles.
- Design for regulatory resilience: Integrate security-by-design with clear supply-chain traceability and a prioritized certification roadmap to avoid market access delays in key regions.
- Re-evaluate monetization mixes: Test hybrid models that combine device sales with subscription services tied to value-add AI features and cloud orchestration. Use cohort-level economics from our report to model CAC payback under different scenarios.
- Optimize BOM vs. experience tradeoffs: Use component-cost sensitivity outputs to determine when higher-cost connectivity chips (e.g., Wi‑Fi 6E/7) materially improve retention and ARPU, and when they simply erode margins.
- Pursue tactical M&A and partnerships: Target edge-AI, secure provisioning, and subscription-enablement assets that accelerate time-to-market and reduce integration risk; our acquisition scorecards identify the capability gaps most impactful for 2026 scale-up.
- Strengthen aftermarket and services: Invest in warranty, predictive maintenance, and upgrade paths to convert device buyers into long-term subscribers — the revenue mix that supports higher valuations.
- Prepare channels for scale: Build retail merchandising and carrier-inclusive offers now to capitalize on the expected consumer upgrade cycle; the right channel economics will determine 2026 traction.
Methodology and evidence confidence
The report’s forecasts are built on a transparent methodology: historical shipments and revenue (2020–2025), a base-year calibration (2025 denominated in USD, revenue unit: Billion), and an explicit forecast period covering 2026–2032. We triangulate multiple data sources — primary interviews, device shipment data, component-cost intelligence, and proprietary demand elasticity models — to produce both point forecasts and scenario ranges. Key macro outputs are underpinned by the 14.85% CAGR noted above and a detailed sensitivity analysis you can use for budget stress-testing.
Why this matters for 2026 planning
Decisions made in 2026 will lock in platform positions, channel relationships, and regulatory compliance postures for the next business cycle. The combination of rapid market growth, moderate concentration, and tightening regulation creates a strategic window for companies that can move quickly on interoperability, secure their supply chains, and convert hardware into recurring value.
PW Consulting’s Consumer IoT Market report is designed to be operational: it not only explains where the market is headed, but shows what to do next — product specs to prioritize, partnership archetypes to pursue, regulatory milestones to budget for, and acquisition targets that close capability gaps.
Next steps
This article is a strategic preview. For the full dataset, granular segment breakouts, vendor scorecards, and downloadable executive decks that operationalize the recommendations above, access the complete report on the PW Consulting website. The full report contains the detailed tables, appendices, and modeling templates your teams will need to convert insight into 2026 action plans.
For detailed analysis of this topic, please visit the official page: Consumer Iot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com