

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: P Series Glycol Ether Market Poised to Expand at a 4.85% CAGR, 2025 Insight Predicts Steady Growth
By pmarketresearch, 2026-07-13
P Series Glycol Ether Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
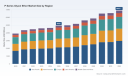
The global market for P‑series glycol ethers reached roughly USD 4.95 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of approximately 4.85% across the 2026–2032 forecast window. That trajectory points to market scale and resilience that matter for investment planning, plant allocation, and procurement strategies in 2026. This preview summarizes the strategic insights in PW Consulting’s P Series Glycol Ether Market report, highlighting actionable implications for commercial, supply‑chain, and M&A decisions while intentionally withholding granular segment figures to encourage direct access to the full analysis.
P Series Glycol Ether Market
Why P‑series glycol ethers deserve boardroom attention in 2026
-
End‑market breadth: P‑series glycol ethers are embedded across paints & coatings, electronics, industrial and household cleaners, printing inks and adhesives. This cross‑industry exposure cushions demand volatility but also requires differentiated go‑to‑market tactics by end‑use.
P Series Glycol Ether Market -
Moderate, steady growth: The sub‑5% CAGR signals a market that is neither a hyper‑growth play nor in terminal decline — ideal for firms seeking stable, cash‑generative chemical portfolios or for financial buyers targeting defensive specialty‑chemical assets.
P Series Glycol Ether Market -
Supply sensitivity: The production chain is tightly linked to propylene oxide feedstock and a concentrated set of global producers, making short‑term supply shocks and price moves materially relevant to operating and pricing strategy.
Market dynamics and demand drivers
Demand dynamics in 2026 will be shaped by a steady recovery and structural shifts across major end markets. Paints and coatings remain the single largest demand driver by application, with performance and regulatory requirements pushing formulators toward higher‑purity solvents and specialty grades. The electronics and semiconductor segment continues to exert above‑average growth given precision cleaning and formulation needs in advanced packaging and assembly.
Concurrently, industrial and household cleaning formulations are evolving toward low‑VOC and performance‑enhanced chemistries. This means producers with technical service capabilities and formulation partnerships will be better positioned to capture premium value than purely commodity suppliers.
Upstream cost and supply signals to monitor
-
Propylene oxide remains the primary upstream feedstock. Recent price volatility — including a notable uptick in early 2026 driven by firm downstream demand and feedstock cost pressures — underscores the channel through which raw‑material shocks transmit to glycol ether margins and market pricing.
-
Regional feedstock imbalances also create tactical arbitrage opportunities. Quarterly swings have been observed, and players with flexible feedstock sourcing, hedging programs, or integrated propylene/propylene‑oxide positions will see differentiated margin performance.
-
Operational disruptions at key facilities can cascade rapidly because of market concentration. The March 2026 force majeure declared by a major producer following a Bayport facility incident is a reminder that short‑term tightness can reshape trade flows and margin profiles for months.
Regulatory and sustainability tailwinds
Regulatory developments are elevating both compliance risk and opportunity. In the U.S., proposed Significant New Use Rules (SNURs) under TSCA signal greater scrutiny of certain glycol‑ether related substances. Parallel initiatives in EMEA and APAC focus on emissions, worker safety, and end‑use labeling.
These regulatory currents are accelerating buyer preferences for documented low‑toxicity, low‑VOC, and life‑cycle‑assessed solvent alternatives. Manufacturers that proactively invest in regulatory affairs, product stewardship, and Green Chemistry initiatives will not only reduce risk but also open premium channels in regulated markets.
Competitive landscape — what the leading players are doing
The P‑series market exhibits moderate concentration: the top three producers control a meaningful share of capacity while the top five intensify that concentration. This structure produces both stability and competitive friction: stable incumbent economics on one hand, and recurring opportunities for differentiation through specialty grades, service models, and geographic footprint optimization on the other.
-
Dow Inc. — A major global producer with well‑known P‑series brands and broad production capacity. Recent 2026 pricing actions illustrate how integrated sellers can manage margin recovery during feedstock volatility.
-
LyondellBasell Industries — Significant producer with large-scale assets; the March 2026 Bayport Choate facility fire and subsequent force majeure exemplify how single‑site incidents can influence global availability.
-
BASF SE , INEOS Oxide , Eastman , Shell Chemicals , and Huntsman — These incumbents compete across commodity and specialty grades, leveraging technical service, geographic reach, and integrated petrochemical capabilities.
-
Regional and specialty players such as KH Neochem, Chang Chun Group, Sasol and Solventis play important roles in local supply, niche applications, and cost‑competitive service models, especially in Asia and Europe.
Recent market shocks with strategic implications
-
Early‑2026 price increases from a major supplier demonstrate how producers attempt to recover margin when feedstock costs firm and operational leverage exists.
-
Operational disruptions (e.g., Bayport) have already prompted buyers to re‑evaluate sourcing redundancy, inventory policies, and contractual protections such as force majeure clauses.
-
Raw‑material price swings require sharper procurement playbooks: dynamic hedging, multi‑source qualification, and strategic inventory positioning.
What PW Consulting’s report delivers — practical, decision‑grade tooling
Our full P Series Glycol Ether Market report is designed for executives who need to translate market intelligence into 90‑day and 18‑month actions. Deliverables include:
-
Market sizing and growth scenarios with demand‑sensitivity testing across the 2026–2032 forecast horizon (base year 2025).
-
Supply‑side mapping that traces capacity, utilization, and trade flows across major production hubs—paired with a risk matrix that quantifies disruption probability and likely commercial impacts.
-
Commercial playbooks: go‑to‑market archetypes for commodity, differentiated, and specialty strategies; pricing levers and contract clauses to protect margins during feedstock volatility; and account segmentation frameworks for prioritizing downstream relationships.
-
Regulatory and sustainability impact models that translate proposed rules and ESG KPIs into cost and revenue scenarios for compliant portfolio optimization.
-
Competitive due diligence dossiers on the leading producers, including capacity positioning, product portfolios, recent commercial moves, and M&A/partnership playbooks.
-
Proprietary index of raw‑material and logistics indicators that serve as early‑warning signals for procurement and operations teams.
Strategic playbook for 2026 — recommended executive actions
-
Short term (0–6 months): Reassess procurement and inventory policies to reflect current feedstock volatility. Prioritize contractual flexibility and diversify qualified suppliers for critical grades. Leverage short‑duration hedges where feasible.
-
Medium term (6–18 months): Accelerate qualification of specialty and high‑purity grades for electronics and regulated end markets. Invest in formulation partnerships and co‑development agreements to lock in downstream demand and margins.
-
Portfolio & M&A: Target bolt‑on acquisitions that add technical service capabilities, regional footprint, or niche grades. Divest commodity exposure where capital allocation is constrained and pursue vertical integration if feedstock control is strategically viable.
-
Risk & compliance: Establish regulatory surveillance to track SNUR and analogous developments globally. Build compliance roadmaps and marketing narratives around low‑toxicity credentials to maintain market access and pricing power.
-
Operational resilience: Model alternative production and logistics scenarios to prepare for site‑level outages. Invest selectively in capacity redundancy or tolling arrangements in strategically important regions.
How to use this preview
This article functions as a strategic trailer: it communicates the major forces and recommended responses that should shape 2026 decision cycles, while preserving the detailed segmentation, regional flows, and proprietary numeric assumptions for subscribers of the full PW Consulting report. If your 2026 plan hinges on new capacity investments, contract renewals, or an acquisition mandate in glycol ethers, the full report provides the granular, transaction‑grade analysis needed to proceed with confidence.
Next steps
For access to the full dataset, regional and application breakdowns, supplier scorecards, and scenario models referenced in this preview, please consult the P Series Glycol Ether Market report on PW Consulting’s website or contact your PW account representative. The full report includes the underlying assumptions, sensitivity analyses and downloadable tables required to build investment memos, procurement strategies, and board presentations for 2026.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Residential Solar Power Solutions Poised for Rapid Expansion — 14.02% CAGR Projected Through 2032, Report Finds
By pmarketresearch, 2026-07-13
Residential Solar Power Solutions Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s Residential Solar Power Solution Market report (base year 2025; forecast 2026–2032) delivers a concise, actionable intelligence set designed for executive teams making investment, sourcing, product, and M&A decisions in 2026. The global market reached approximately USD 128.2 Billion in 2025 and—driven by continued residential electrification, storage adoption, and falling balance-of-system costs—is projected to grow at a compound annual growth rate of roughly 14.02% through 2032, reaching the low hundreds of billions by the end of the forecast window.
Residential Solar Power Solution Market
Why this report matters for 2026 planning
- High-growth context: A sustained double-digit CAGR creates a widening set of strategic options—but also amplifies supply-chain and regulatory risk for players who delay decisive moves.
- Policy inflection points: Recent regulatory shifts and trade enforcement actions materially alter market access and cost structures for suppliers and integrators in 2026.
- Commercial inflection points: The convergence of solar + storage + smart energy management is re-defining product bundles and the revenue model for residential offerings.
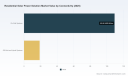
- Competitive positioning: Moderate market concentration at the top (CR3 ~34.5%, CR5 ~42.8%) means scale advantages exist, but there is also room for differentiated challengers through technology, services, or channel control.
Key dynamics shaping 2026 strategy
- Supply-side pressure and raw-material cost swings — Special focus: polysilicon. Industry reporting showed a notable spot-price uptick in polysilicon in early 2025 (circa +12% in Q1 2025), which, together with module capacity cycles, can compress supplier margins and translate into intermittent price volatility for system integrators.
- Policy and trade interventions — U.S. policy moves in 2025–2026 (including domestic tax-credit changes and tariff/quota enforcement periods) have created near-term shifts in demand economics and import sourcing strategies. These changes require scenario-based planning to understand how pricing and market access evolve through 2026.
- Residential system cost trends — Benchmarks from the market indicate U.S. residential system pricing ranges observable in H1 2025; these remain a critical commercial input for pricing, rebate modeling, and homeowner ROI communications heading into 2026.
- Product convergence — Energy storage and advanced inverter/control platforms are moving from “optional upsell” to core elements of competitive residential propositions. Integrators that combine hardware, software, and financing will capture higher lifetime value.
- Consolidation and supplier concentration — Leading module and inverter manufacturers continue to expand capacity and vertically integrate. While top-tier suppliers enjoy procurement and technology advantages, channel control by installers, software players, and financiers will be decisive for go-to-market success.
Competitive landscape — strategic implications
Our competitive assessment synthesized public profiles, shipment trends, and capability mapping for leading suppliers and system suppliers. The market features a mix of very large module manufacturers, specialized inverter and microinverter innovators, and integrated home energy providers. Representative strategic positions include:
Residential Solar Power Solution Market
- Large-module manufacturers (scale & vertical integration): Major PV module producers emphasize high-efficiency monocrystalline technologies and vertical integration across wafers-to-modules. Their strengths lie in cost control at scale, R&D investment into efficiency gains (including N-type technologies), and global distribution networks. For 2026, these players will continue to shape pricing corridors and availability of higher-efficiency modules suited for residential rooftops.
- Performance-differentiated suppliers (premium efficiency & specialty cells): A subset of manufacturers focuses on premium panels optimized for constrained-rooftop applications or aesthetic-sensitive deployments. These firms can capture premium ASPs (average selling prices) but face pressure if polysilicon and cell-cost spreads compress.
- Power electronics leaders (inverters & integrated control): Companies focused on microinverters, DC-optimizer systems, and home-energy orchestration platforms provide clear customer-value differentiation via improved production, module-level monitoring, and seamless storage integration. These capabilities are a primary battleground for installers seeking higher-margin service offerings.
- Integrated home-energy OEMs & assemblers: Vendors combining panels, storage, and software create simpler procurement pathways for residential customers and installers. Their ability to deliver unified warranty, financing, and experience is reshaping purchase decision criteria.
Strategic implications for 2026 include defending margin via vertical hedging, selectively partnering with differentiated inverter/EMS providers, and accelerating product-service bundles that lock-in customers across lifecycle touchpoints (sales, financing, warranty, upgrades).
Residential Solar Power Solution Market
What’s in the PW Consulting report — practical, decision-ready content
We designed the report to support decisions made in 2026 by corporate strategy, corporate development, product, supply chain, and commercial teams. Highlights of the deliverables include:
- Market sizing and topline forecasts (2020–2032) with scenario variants reflecting material price shocks, tariff cases, and rapid storage adoption pathways.
- Supplier and technology benchmarking decks that score manufacturers and platform providers across manufacturing scale, technology roadmap, channel relationships, and risk exposure—presented as a management-ready scorecard (high-level view in the public summary; full scorecards in the report).
- Supply-chain stress tests and procurement scenarios that model the impact of polysilicon price spikes, quota/duty events, and shipping disruptions on landed module cost and system gross margins.
- Commercial playbooks for product bundling, installer partnerships, financing constructs, and price communication strategies for different homeowner segments—each with example P&L and payback illustrations.
- M&A and partnership pipeline: prioritized capability gaps and target archetypes, plus due-diligence checklists tailored for residential solar acquisitions (technology, O&M, installer networks, storage).
- Regulatory playbook and scenario matrix: mapping major near-term policy changes and enforcement actions to demand elasticity, subsidy exposure, and regional go-to-market risk.
Actionable recommendations for 2026 (for CEOs, CPOs, and Heads of Strategy)
- Pursue supplier diversification with contractual hedges: lock forward volumes and index-linked pricing where possible to insulate gross margins from polysilicon volatility.
- Prioritize storage-enabled offerings: structure bundled propositions that make energy storage the default upgrade for higher-LTV customers, with financing that smooths upfront economics.
- Accelerate software and service capabilities: invest in EMS, monitoring, and remote O&M to differentiate on lifecycle economics rather than one-time hardware sales.
- Re-assess channel economics under changing policy scenarios: build flexible go-to-market playbooks for both subsidy-rich and subsidy-constrained environments, and stress-test customer acquisition cost assumptions.
- Stand ready for trade/regulatory developments: monitor quota windows, duty announcements, and anti-dumping cases closely; incorporate rapid sourcing-switch capabilities into procurement playbooks.
- Use targeted M&A to fill capability gaps: prioritize targets that offer installer footprints, storage technology, or software stacks that immediately lift margins and shorten time-to-market for integrated propositions.
What we intentionally withheld in this preview — and why
To preserve the report’s value as a decision-grade deliverable, this public preview intentionally omits granular segment-level revenue tables, proprietary supplier scorecards, and the full set of scenario-modeled P&L impacts. Those detailed data points and downloadable templates are included in the full PW Consulting report and are accessible via our report portal for clients and subscribers.
Next steps
For executive teams preparing 2026 budgets and strategic plans, the full report is the recommended starting point for scenario workshops, procurement term negotiations, product roadmap updates, and M&A screening. PW Consulting also offers tailored advisory sessions and data workshops that overlay your company’s P&L and supplier portfolio onto our market model to produce bespoke action plans for the year ahead.
To request the full report, a briefing, or a customized scenario run for your organization, visit the PW Consulting research center or contact your account lead. In a market expanding at a mid-teens CAGR with fast-moving policy and raw-material headwinds, having the right market intelligence—and the operational plans to act on it—will determine who leads the residential energy transition in 2026.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Atmosphere Furnace Market Tops USD 612.45 Million in 2025, Forecast to Reach USD 1,037.85 Million by 2032 at a 7.85% CAGR
By pmarketresearch, 2026-07-13
Vacuum Atmosphere Furnace Market 2026: Strategic Intelligence Briefing for Decision-Makers
As companies position for growth in 2026, senior leaders in manufacturing, aerospace, energy, and advanced materials require a compact, actionable line of sight into the vacuum atmosphere furnace market. PW Consulting’s latest market research synthesizes historical performance, forward-looking forecasts, competitive motion, supply-chain dynamics, and regulation-driven technology shifts to provide that line of sight — without giving away the proprietary segment-level granularity reserved for the full report.
Vacuum Atmosphere Furnace Market
Market at a Glance: Growth, Scale, and Momentum
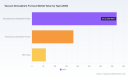
The vacuum atmosphere furnace market has shown steady expansion across the 2020–2025 historical window, rising from roughly USD 412 million in 2020 to an estimated USD 612 million in the 2025 base year. Our forecast models, calibrated with manufacturing capex cycles, materials demand, and regulatory tailwinds, project continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 7.85%. By 2032 the market is expected to exceed USD 1.03 billion, underscoring material opportunities for equipment suppliers, service providers and downstream manufacturers that can capture mid- to long-term demand.
Vacuum Atmosphere Furnace Market
Two structural forces are driving this scale: (1) ongoing capital expenditure among aerospace, semiconductor and advanced metallurgy customers that favor controlled-atmosphere processing; and (2) retrofit and replacement demand as energy-efficiency and emissions regulations increasingly constrain older furnace assets. These forces create both near-term serviceable revenue and longer-term platform replacement cycles.
Vacuum Atmosphere Furnace Market
What the PW Consulting Report Delivers
- Integrated market model: A transparent top-down forecast (2026–2032) plus back-tested historical reconciliation (2020–2025) that enables scenario analysis under different macro and commodity assumptions.
- Practical procurement playbook: Sourcing strategy templates, lead-time mitigation tactics, and supplier scorecards for negotiating turn-key and custom furnace solutions.
- Technology and product roadmap: Comparative assessment of horizontal vs. vertical architectures, quenching technologies, control systems, and energy-efficient retrofits — with guidance on R&D prioritization.
- Supply chain & materials risk matrix: Actionable mitigants for graphite and specialty alloy constraints, including dual-sourcing strategies and inventory buffers calibrated to lead-time elasticity.
- Competitive positioning and M&A playbook: Profiles of market-leading suppliers, CRx concentration analysis, and inorganic growth scenarios tailored to different buyer archetypes.
- Regulatory and sustainability checklist: Region-aware compliance triggers, energy-performance KPIs, and CAPEX ROI models that quantify payback for cleaner furnace technologies.
Note: This briefing intentionally omits the granular, per-segment revenue splits and unit-level price decks included in the complete report to preserve the value of the premium dataset.
Competitive Landscape: Strategic Profiles and Implications
-
Ispen (Ipsen) — Cherry Valley, IL, USA: A full-line supplier with series offerings optimized for aerospace, medical and industrial heat treating. Ipsen’s breadth is a defensive advantage for customers seeking end-to-end service and certification continuity. Strategy implication: buyers should benchmark total cost of ownership (TCO) and service footprint when comparing Ipsen to more specialized contenders.
-
Solar Manufacturing — Sellersville, PA, USA: Known for advanced vacuum furnaces incorporating high-pressure gas quenching and energy-efficiency features. Recent shipments to aerospace suppliers reinforce its relevance for precision component heat treatment. Strategy implication: OEMs prioritizing cycle time and surface integrity should evaluate Solar’s high-pressure platforms against retrofit alternatives.
-
Centorr Vacuum Industries — Nashua, NH, USA: Offers extremely high-temperature and specialized furnaces used in R&D and niche production applications, with a long installed-base record. Strategy implication: companies in advanced materials and research-intensive sectors should consider Centorr for bespoke, high-temperature needs where standard platforms underperform.
-
SECO/WARWICK — Meadville, PA (Group: Poland): Provider of high-vacuum and brazing systems across aerospace, automotive and nuclear segments. The Group’s geographic footprint is an advantage for global programs. Strategy implication: multi-site manufacturers should evaluate SECO/WARWICK where commonality of equipment simplifies qualification and cross-site standardization.
-
AVS Inc. — Ayer, MA, USA: A custom-builder focused on meeting exacting temperature and vacuum specifications. Strategy implication: AVS is a natural partner for customers requiring tight process control and bespoke thermal solutions rather than commodity platforms.
-
ECM Technologies — Grenoble, France: Strong in brazing, sintering and vacuum heat treatment for European metallurgy and aerospace supply chains. Strategy implication: European manufacturers focused on certification and localized service should prioritize ECM in vendor shortlists.
-
Camco Furnace — San Carlos, CA, USA: Specializes in hydrogen and high-vacuum solutions up to very high temperatures. Strategy implication: Companies exploring hydrogen atmosphere processing or cold-wall architectures should evaluate Camco’s offerings for process-specific advantages.
-
ALD-Holcroft — Wixom, MI, USA: Delivers vacuum technologies targeted at advanced heat treatment processes with emphasis on industrial-scale throughput. Strategy implication: suitable for high-volume producers seeking continuous-improvement partnerships.
Industry concentration metrics highlight an outcome of moderate fragmentation with pockets of consolidation: the top three players account for a meaningful share of revenue, while the top five control a clear majority, indicating acquisition opportunities for firms looking to scale quickly or consolidate supply chains.
Recent Market Developments: Signals to Watch
- 2026: Installation of a 10-bar vacuum furnace at a major U.S. heat-treating facility signals increasing adoption of high-pressure, high-throughput equipment for aerospace and heavy-industry processing.
- 2025: Multiple new shipments and hot-zone upgrades to leading aerospace suppliers — evidence of ongoing modernization and demand for higher-integrity process environments.
- 2025: Nadcap merit status awarded to a facility for heat treating and brazing underlines the continuing importance of accredited processing capacity for aerospace supply-chain compliance.
Collectively, these events reflect two overlapping trends: investment in higher-performance equipment to meet advanced material specifications, and expansion of certified processing capacity to absorb rising demand from regulated, quality-driven industries.
Segment Dynamics, Risks and Near-Term Disruptors
Three predominant dynamics will shape supplier and buyer strategies in 2026:
- Materials supply risk: Constraints in high-purity graphite and export controls have increased cost and lead-time volatility for furnace hot zones and insulation systems. Firms should model production schedules with extended lead-times and consider inventory hedging or alternate material investments.
- Regulatory pressure: European energy-efficiency and emissions requirements are accelerating demand for cleaner furnace technologies and higher-efficiency controls. This shifts buyer preference toward vendors able to demonstrate certified energy-performance improvements and lifecycle emissions reductions.
- Technology substitution and retrofits: As customers weigh the economics of replacing legacy furnaces versus retrofitting modern control and quench systems, suppliers offering modular, upgradeable architectures will capture aftermarket and conversion revenue.
These dynamics magnify the value of a dual-track strategy that protects short-term throughput while investing in long-term efficient platforms.
Actionable Strategic Playbook for 2026
- For OEMs and Asset Owners: Prioritize qualification paths that preserve supply continuity (multi-vendor trials) and include service-level agreements for spare parts tied to graphite-critical subassemblies. Run accelerated ROI models to validate energy-efficiency retrofits where regulatory pressure is highest.
- For Equipment Suppliers: Invest in modular designs enabling field upgrades, expand service networks in regulated markets, and develop commodity procurement partnerships to mitigate graphite supply shocks. Consider targeted M&A to increase scale in certification-heavy segments.
- For Investors and Private Equity: Seek platform investments in suppliers with strong service capabilities and global certification footprints. Use the market’s moderate concentration to structure buy-and-build strategies that capture aftermarket revenue and standardize spare-parts catalogs.
- For R&D and Product Strategy: Accelerate development of alternative hot-zone materials and closed-loop energy recovery technologies. Differentiate through digital process controls that reduce cycle variability and enable predictive maintenance monetization.
Why PW Consulting’s Intelligence Matters for 2026
Decisions in 2026 will be shaped less by single-year demand spikes and more by strategic positioning across supply-chain resilience, regulatory compliance, and the ability to monetize aftermarket services. PW Consulting’s report converts raw market indicators into decision-ready options: quantified trade-offs for CAPEX vs. retrofit, supplier scorecards for procurement, and an M&A playbook mapped to concentration dynamics. The analysis is deliberately tactical — enough to inform board-level capital allocation and procurement plans — while withholding the full segment-level datasets that form the report’s competitive advantage.
Next Steps
For organizations preparing budgets, supplier negotiations or inorganic growth strategies in 2026, access to the full dataset and scenario models will materially reduce execution risk. The full PW Consulting Vacuum Atmosphere Furnace Market Report contains the detailed segmentation, regional forecasts, unit pricing models and supplier scorecards required to convert strategy into executable plans. Contact our team for a briefing or to request the full report and bespoke advisory engagements tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Vacuum Atmosphere Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 24-Hour Emergency Roadside Assistance Market Poised to Expand at a 5.12% CAGR Through 2032
By pmarketresearch, 2026-07-13
PW Consulting: Strategic Preview — 24 Hour Emergency Roadside Assistance Market Outlook for 2026 Decision-Makers
As automotive ecosystems accelerate toward electrification, connectivity and new ownership models, the 24 Hour Emergency Roadside Assistance market is undergoing structural change that will determine competitive advantage through the remainder of the decade. PW Consulting’s latest market study — covering historical performance (2020–2025) and a seven-year forecast (2026–2032) — equips executives, investors and public-sector planners with the practical intelligence necessary to translate operational readiness into strategic value in 2026 and beyond.
24 Hour Emergency Roadside Assistance Market
Headline market context
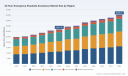
After resilient expansion through the early 2020s, the global 24-hour roadside assistance market is now a multibillion-dollar segment with sustained mid-single-digit growth. Our model shows the market expanding from roughly USD 24.9 billion in 2020 to approximately USD 31.9 billion in 2025, and continuing on to an estimated USD 45.2 billion by 2032 — a compound annual growth rate of 5.12% over the forecast horizon (2026–2032). This growth is being driven by rising vehicle parc, bundled insurance and OEM service propositions, fleet telematics adoption, and incremental service complexity tied to EVs, ADAS and vehicle software-driven immobilisations.
24 Hour Emergency Roadside Assistance Market
Why this report matters for 2026 planning
- Translating growth into margin: We show where revenue pools are expanding versus where unit costs are rising (e.g., EV handling, specialist storage and safety protocols), enabling CFOs to forecast margin sensitivity under realistic scenarios.
- Vendor selection and partnership strategy: Insurers, OEMs and fleets face a choice between scale players, white-label integrators and on-demand digital platforms. The report provides a decision framework to match partner capabilities to required SLAs, liability exposures and customer experience outcomes.
- Regulatory & operational risk management: With patchwork regulation across jurisdictions (from storage fees and EV-incident requirements to inconsistent standards for roadside service vehicles), the study flags where compliance gaps will create near-term costs or service failures.
- Technology investment prioritisation: We prioritise investments — dispatch orchestration, predictive call triage, remote diagnostics and EV-safe response tooling — by expected ROI and adoption risk through 2028.
What’s inside — operationally focused deliverables
Rather than a high-level narrative, the report is structured as a hands-on playbook for commercial leaders and operations teams. Core chapters include:
24 Hour Emergency Roadside Assistance Market
- Executive synthesis and decision-ready dashboards summarising market size, growth trajectories and scenario sensitivities for 2026 board cycles.
- Methodology and raw-market modelling (transparent assumptions, data sources, and a reproducible forecasting engine) so clients can stress-test outcomes under custom inputs.
- Service-level economics: unit costing models for towing, battery/jump starts, tire replacement, fuel delivery and lockout/minor repair, with uplift drivers for EVs and heavy-vehicle responses.
- Provider benchmarking and capability scorecards: operational KPIs, dispatch technology maturity, OEM integrations, white-label strength and financial resilience — enabling shortlist creation for RFPs and M&A screening.
- Technology map and vendor directory: comparison of telematics integrators, AI dispatch providers, mobile repair platforms and EV charging/handling specialists.
- Regulatory impact assessment: jurisdictional risk heatmaps, compliance cost estimates and recommended policy interventions for operators and policy-makers.
- Scenario planning and contingency playbooks: 12–36 month stress scenarios (sharp EV incident uptick, regional regulatory shifts, acute labour shortages) with step-by-step operational responses.
- Commercial go-to-market templates: bundled product architectures for insurers and OEMs, pricing sensitivity matrices and customer-retention levers for membership models.
- Appendices: interview transcripts with operators, anonymised call-level cost samples, and procurement templates for outsourcing roadside services.
Note: the report contains detailed segment-level tables (geography, service type, provider model) and granular forecasts intended for purchasing organisations. This press summary purposefully highlights strategic implications while reserving segmental line-items for report subscribers.
Competitive landscape — how incumbents and challengers are positioning
The market is shaped by a mix of longstanding member clubs, insurance-affiliated programs, OEM-backed white-label operators and digitally native platforms. Our competitive analysis profiles each major participant on commercial model, technology posture and scale economics:
- American Automobile Association (AAA) — A membership-centric model with deep brand equity and operational scale across North America. AAA’s strengths lie in its trusted local patrol networks and member experience, which create high retention even as service mix slowly broadens toward EV-related capabilities.
- Agero, Inc. — A dominant white-label integrator offering orchestration for insurers, OEMs and fleets. Agero’s competitive edge is advanced dispatch tech and the ability to integrate EV charging and specialty services into end-to-end claims workflows.
- Allianz Partners — Strong in OEM and insurance partnerships across Europe and beyond. Recent contract extensions with automakers demonstrate the group’s focus on harmonised, cross-market programs and premium-level features such as alternative transport and repair coordination.
- ADAC , RAC and AA (UK) — Large national clubs with substantial patrol fleets and strong member loyalty. Their operating playbooks prioritise rapid roadside repair and recovery, while selectively partnering with third parties for specialised services or new vehicle technologies.
- Digital challengers (e.g., Urgently) — These platforms compete on speed-to-scene, dynamic dispatching and seamless UX. Their capital-light networks and AI-driven triage are attractive to dealers and urban fleets, but scaling to long-distance towing and heavy-recovery remains a challenge.
- Insurer-owned programs (e.g., GEICO, Allstate, Progressive) — Roadside assistance is often an embedded add-on or motor-club product, used strategically to enhance policy stickiness and customer satisfaction. Integration with claims handling is the differentiator.
- Regional network providers (Falck, ARC Europe, Viking Assistance, SOS International) — Important partners for cross-border continuity, especially for OEMs and pan-European insurers. Their value is network coverage combined with local compliance expertise.
- Smaller independents and fleet specialists — Provide flexible surge capacity and local expertise for large fleet customers; often targets for consolidation by scale players seeking geographic density.
Recent moves and what they signal
- Allianz Partners’ expanded OEM agreements and reappointments underscore the commercial value automakers place on harmonised roadside experiences as part of owner retention strategies.
- RAC’s retailer/OEM collaborations signal continuing co-opetition in new-entrant markets: incumbent patrol networks are monetising service delivery for emerging brands.
- Cox Automotive’s fleet organisation consolidation points to integration playbooks where vehicle lifecycle services (roadside, maintenance, remarketing) are bundled to extract higher lifetime value.
- High-profile marketing and sports sponsorships by member clubs remain a low-cost retention channel that also supports brand trust — a critical asset for converting roadside interactions into longer-term customer relationships.
Regulatory and operational dynamics to watch in 2026
Operators and contracting organisations must plan for a more complex regulatory environment and changing operational risk:
- Jurisdictional fragmentation: rules governing storage and handling of damaged EVs, roadside service vehicle lighting and provider vetting vary significantly across states and countries. For example, new state-level rules affecting post-crash EV storage and separation specifications will create logistic and cost implications for regional operators.
- Oversight gaps: some jurisdictions still treat roadside assistance distinctly from licensed towing, creating uneven standards for training, equipment and liability exposure — a contracting and reputational risk for insurers and platforms relying on third-party vendors.
- Service demand composition: despite high visibility around EV range anxiety, EV-related calls remain a small share of total volumes for large member clubs today, suggesting a near-term mismatch between public perception and operational reality. However, as EV market share rises, specialised handling and storage requirements will impose non-linear cost increases if unplanned.
- Asset stressors: infrastructure issues (for example, spikes in pothole-related breakdowns observed by patrol services) create episodic demand peaks that stress capacity planning and surge pricing models.
Ten strategic implications for 2026 decision cycles
- Embed EV-safe response processes into vendor contracts and insurance claims flows now, not later.
- Invest selectively in dispatch and predictive triage tools to reduce drive time and increase first-time-fix rates.
- Make regional regulatory risk a transaction checklist item for M&A and partnership diligence.
- Design tiered service bundles that reflect differing economics of short-haul urban responses vs. long-distance recovery.
- Create cross-functional playbooks between claims, roadside operations and customer experience teams to monetise service touchpoints.
- Use pilot procurements to test AI-enabled digital dispatchers with clear KPIs before wide rollout.
- Prioritise partnerships with network providers for cross-border continuity when serving OEMs and multinational fleets.
- Stress-test pricing models against episodic demand surges caused by infrastructure failures or severe weather.
- Retain in-house capability for critical, brand-defining interventions even where outsourcing is economical for routine calls.
- Monitor public policy trends and participate in regulatory consultations to shape practicable standards for EV handling and RSV operations.
Conclusion — how PW Consulting’s report supports 2026 decisions
For executives needing to convert market growth into sustainable margin and resilience, this report provides both the horizon picture and the tactical playbooks required for 2026 board decisions. It balances reproducible forecasting with procurement-ready due diligence tools and operational playbooks that address the most pressing risks — from regulatory heterogeneity to technology adoption trade-offs. As incumbent operators, insurers, OEMs and challengers set priorities for capital allocation, hiring and partner selection this year, access to the full dataset and provider-level benchmarking included in PW Consulting’s study will be decisive.
To access the complete report — including the granular segmentation tables, provider scorecards and downloadable modelling files that underpin the conclusions summarised here — visit PW Consulting’s report page or contact our client services team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Satellite Control Service Market Poised to Expand at 7.45% CAGR During 2026–2032, New Report Finds
By pmarketresearch, 2026-07-13
Satellite Control Service Market 2026: Strategic Intelligence to Guide C-Suites and Program Managers
Executive summary
PW Consulting’s latest Satellite Control Service Market report, with base year 2025 and a forecast horizon through 2032, distills the commercial and government dynamics that will shape mission-critical satellite operations decisions in 2026. After a sustained expansion from 2020 through 2025, the market reached roughly USD 21.45 billion in 2025 and is projected to grow at a compound annual growth rate of approximately 7.45% across the 2026–2032 forecast window, reaching the mid‑30 billion USD range by the end of the period. This trajectory reflects accelerated demand for resilient telemetry, tracking & command (TT&C), multi-orbit operations, and outsourced ground services models that reduce capital intensity for satellite owners and operators.
Satellite Control Service Market
Why this report matters for 2026 decision-making
Space programs that fail to align procurement, operations and regulatory strategy in 2026 risk operational fragility and suboptimal total cost of ownership over a satellite’s lifecycle. This report is designed as an executable intelligence product for executives, program managers, investors and policymakers facing three interdependent choices: build or buy (infrastructure vs. GSaaS), mono-orbit vs. multi-orbit operational posture, and local compliance vs. global access strategies.
Satellite Control Service Market
-
Timing: With regulatory windows and spectrum access decisions maturing in early 2026, strategic procurement and partnership decisions made this year will determine 2027–2029 mission capabilities and margins.
Satellite Control Service Market -
Capital allocation: The market’s growth path amplifies both opportunity and risk—investors and operators must balance near-term GSaaS engagements against long-term investments in distributed ground infrastructure.
-
Operational resilience: Trends toward constellation scale, mixed orbits, and shorter mission lifecycles make automated, software‑defined control architectures a requirement rather than an option.
What the report contains — practical, decision‑ready content
PW Consulting’s report goes beyond market sizing to deliver operational playbooks and procurement-ready artifacts that teams can use immediately. Core contents include:
-
Executive summaries and scenario models that translate macro growth into portfolio‑level revenue and cost trajectories under alternative business models (in-house operations, hybrid outsourcing, GSaaS).
-
Vendor evaluation frameworks and procurement checklists designed to shorten RFP cycles while reducing vendor lock-in risk (including recommended contract clauses for continuity-of-operations, spectrum contingency, and cyber assurance).
-
Operational architecture templates for single-point and distributed TT&C—covering automation, mission planning interfaces, latency profiling, and SLAs aligned to mission classes (commercial, civil/scientific, defense).
-
CapEx vs. OpEx decision matrices that quantify break-even horizons for ground infrastructure purchases versus long-term service agreements, adjusted for mission tempo and risk tolerance.
-
Regulatory and market-access trackers that map near-term legislative and agency actions to operational impacts—so teams can prioritize licensing, spectrum filings and stakeholder engagement.
Competitive landscape — who matters and why
The satellite control services market is shaped by a mix of global fleet operators, ground‑segment specialists, defense contractors, and nimble GSaaS providers. Rather than a winner‑takes‑all topology, competition is forming around capability bundles—end‑to‑end mission services, geographic diversity of ground access, multi‑orbit expertise, and 24/7 operational continuity. Key strategic players profiled in the report include established operators and specialized providers with differentiated propositions:
-
KSAT (Kongsberg Satellite Services) — leader in globally distributed ground networks and multi-orbit TT&C, increasingly positioning itself as a mission-adapted operator for LEO through lunar missions. Its continued network expansion in early 2026 reinforces its role as a resilience partner for operators seeking geographic redundancy.
-
SES S.A. — combines global antenna assets with operations centers to offer lifecycle flight-operations services and emergency TT&C restoration; attractive to operators needing integrated continuity solutions.
-
Viasat Inc. — leverages managed connectivity and network operations expertise into satellite control services; recent multi-year contract renewals with defense customers underscore strength in government and joint-base mission support.
-
Intelsat, Eutelsat, Telesat — incumbent fleet operators who balance in‑house control capabilities with third-party ground partnerships to optimize capacity and resilience across commercial and government customer segments. Recent financial and operational updates from select incumbents signal continued investment in control and ground infrastructure.
-
Defense and systems integrators (Kratos, Lockheed Martin, Airbus, General Dynamics, L3Harris, RTX) — these firms supply hardened command-and-control systems, cyber-hardened ground equipment, and full program management for government and defense customers; strategic for customers prioritizing security and sovereign control.
-
Newer GSaaS entrants (Atlas Space Operations, Leaf Space, RBC Signals) — focused on elastic, networked ground services and rapid integration via cloud-native operations models; attractive to smallsat constellations and commercial entrants seeking to avoid CapEx and accelerate time-to-first-contact.
Competitive moves to watch in 2026 include further ground network densification, horizontal consolidation between GSaaS and systems integrators, and an expansion of managed operations contracts with defense agencies. Operators that can combine multi-orbit operational depth with service-level guarantees and cyber maturity will take the commercial lead.
Market dynamics and regulatory context
Several cross-cutting trends and near-term regulatory actions are reshaping strategic trade-offs for 2026:
-
Spectrum and licensing reform: Regulatory initiatives in late 2025 and early 2026 have accelerated prospective access to spectrum and simplified licensing timelines in major markets. For commercial operators this shortens the runway for service launches but increases competition for spectrum-dependent services.
-
Infrastructure approvals and harmonization: Measures to accelerate infrastructure permitting — most notably in major economic blocs — reduce time-to-deploy for ground assets but raise the bar on compliance and cross-border coordination.
-
CapEx pressure and GSaaS adoption: High initial capital requirements for antennas, RF chains and control software are driving even established operators to hybridize their business models, blending owned assets with leased GSaaS capacity to preserve cash and flexibility.
-
Operational resilience and sovereignty: Governments and defense customers continue to demand sovereign control capabilities, driving a dual-market dynamic: one for open commercial GSaaS and another for controlled, sovereign operations with higher margins.
-
Co-existence frameworks: National telecom authorities are advancing coexistence rules for integrated satellite‑to‑device services, which has operational implications for spectrum planning, TT&C scheduling and interference mitigation strategies.
Strategic recommendations for 2026
We recommend that leaders adopt a portfolio approach to satellite control services in 2026, combining short-term agility with long-term optionality. Key actions include:
-
Lock-step regulatory engagement: Prioritize filings and regulatory dialogue in jurisdictions with imminent spectrum and licensing changes; treat regulatory positioning as a core competitive asset.
-
Hybrid operations playbooks: Implement blended GSaaS and owned-infrastructure strategies to optimize for mission class, cost of capital, and sovereign requirements. Use pilot contracts to validate SLA performance before committing to large CapEx.
-
Invest in software-defined control: Accelerate automation, telemetry analytics and contingency orchestration to reduce human-in-the-loop burden and shorten reaction times for anomaly resolution.
-
Partner selectively: Pursue strategic alliances with global ground‑network providers for redundancy while keeping mission‑critical command, cyber and mission assurance capabilities in trusted hands.
-
Prepare for consolidation: Build a playbook for M&A and partnership to close capability gaps in multi-orbit operations, ground network diversity, and cyber-hardened control systems.
How to use this report
The PW Consulting Satellite Control Service Market report is both a market sizing model and an operational toolkit. It is structured to support board-level investment decisions, procurement and program management teams, and policy advisors. Subscribers will receive vendor scorecards, contract language templates, scenario financials, and a prioritized roadmap of regulatory actions to monitor through 2026.
For teams preparing 2026 budgets, negotiating multi-year GSaaS contracts, or evaluating vertical integration of ground assets, the report provides the analytical foundation and tactical artifacts you need to move from debate to execution.
Next steps
Contact PW Consulting to obtain the full report and access the underlying models, granular segmentation, vendor benchmarking and executive briefings. The full publication includes the detailed regional, service-type and end-user segmentation that underpins the high-level forecasts presented here—information we intentionally reserve for report subscribers to preserve commercial sensitivity and ensure accuracy in procurement contexts.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Remote Monitoring Systems for Aquaculture Poised for 12% CAGR, Revolutionizing Global Fish Farming
By pmarketresearch, 2026-07-13
Remote Monitoring System for Aquaculture Market: Strategic Insights to Guide 2026 Decisions
PW Consulting today releases a strategic briefing accompanying our forthcoming market study on Remote Monitoring Systems for Aquaculture. This briefing synthesizes the report’s most consequential implications for executive teams, investors, and technology leaders who must make decisive, near-term choices in 2026. It highlights market scale and growth dynamics, competitive positioning, regulatory pressures, and the operational levers that will determine who captures value as the industry moves from early adoption into commercial scale.
Remote Monitoring System For Aquaculture Market
Market trajectory: a data-backed growth story
The remote monitoring systems market for aquaculture has moved quickly from niche deployment to a core enabler of modern farm management. Our analysis documents an expansion from USD 485.6 Million in 2020 to USD 852.4 Million in 2025 (base year). Under the scenarios modeled in the full report, the market is projected to reach approximately USD 1,884.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 12.0% over the 2026–2032 forecast period. This trajectory is driven by accelerating adoption of IoT sensors, AI-enabled analytics, and satellite/satellite-assisted connectivity, coupled with rising regulatory and buyer expectations for demonstrable water quality and animal-health monitoring.
Remote Monitoring System For Aquaculture Market
Why this matters for 2026 strategic planning
- Timing is critical: Firms must move from pilots to operational scale in 2026 if they intend to capture first-mover advantages in standardized monitoring offerings and service contracts. The market’s growth profile rewards early investments in scalable architecture and data integration.
- Platform vs. point-sensor choices have financial implications: Technology decisions made now will influence margins, recurring revenue potential, and upgrade pathways for years. The report models TCO and upgrade cycles across common technology stacks to quantify these impacts.
- Data governance is a competitive moat: Operators who standardize data schemas, provenance, and API-first architectures will be best positioned for partnerships, certification, and value-added analytics monetization.
- Regulatory compliance is non-negotiable: Increasing permit and reporting requirements in key markets mean monitoring systems are transitioning from 'nice-to-have' optimization tools into compliance enablers. Non-compliance risk materially affects valuation and access to markets.
Report contents — practical, decision-ready intelligence
PW Consulting’s full study is designed for immediate operational use by technology buyers and strategic teams. It combines market modeling with a suite of practitioner tools:
Remote Monitoring System For Aquaculture Market
- Market sizing and demand scenarios calibrated to regulatory and deployment milestones;
- Technology roadmap assessments comparing sensors, communications, and analytics layers against deployment contexts (sea-based, pond, RAS);
- Vendor evaluation framework and scorecards to accelerate procurement decisions;
- Operational playbooks (pilot design, scaling checklist, integration with farm-management systems);
- TCO and ROI templates that quantify capex/opex trade-offs, sensitivity to sensor accuracy, and subscription pricing models;
- Regulatory compliance matrix mapping common monitoring requirements to technical specifications and reporting workflows;
- Case studies and field-trial summaries demonstrating practical outcomes and lessons learned from recent deployments.
In keeping with our “trailer” principle, this briefing highlights the kinds of actionable intelligence included in the full report while intentionally withholding granular vendor-level pricing and detailed segment-level allocations to preserve strategic value for subscribers and readers who visit our report page.
Competitive landscape — who to watch
The remote monitoring ecosystem is characterized by a mix of specialized sensor manufacturers, AI and computer-vision startups, systems integrators, and connectivity providers. Market concentration is moderate: the top three vendors account for roughly 31.5% of measured market value, and the top five approximately 46.8%, indicating room for challengers and regional specialists while also showing scale benefits for larger platform players.
Key competitive archetypes and representative vendors include:
- Integrated systems & platform providers: Firms delivering end-to-end IoT platforms and hardware for feeding, water quality, and environmental management. These providers often pair hardware with enterprise software and services.
- AI & imaging specialists: Companies combining underwater cameras, computer vision, and machine learning to provide biomass estimates, behavioral analytics, and health alerts.
- Sensor manufacturers & oceanographic systems: Vendors offering ruggedized probes and oceanographic sensors tailored to aquaculture parameters (DO, pH, ammonia, salinity).
- Connectivity enablers: Satellite and long-range wireless providers delivering off-grid data links critical to offshore and remote farms.
Representative companies profiled in the report include Innovasea Systems, AKVA Group, Aquabyte, XpertSea, Umitron, TerraConnect, eFishery, SENECT, AQ1 Systems, ScaleAQ, YSI (Xylem), Campbell Scientific, Aanderaa, Pentair Aquatic Eco-Systems, BioSonics, Viasat, Deep Trekker, and Eruvaka Technologies. Our vendor assessments evaluate product maturity, integration readiness, after-sales support, regulatory credentials, and proven field performance.
Recent developments shaping 2026 decisions
- Innovasea’s late-2025 Topian Initiative emphasizes submersible net-pen technology paired with advanced remote monitoring — a signal that hardware innovations and novel farming concepts will create new product-specification demands.
- Industry guides and buyer’s manuals published in early 2026 are accelerating buyer education on standards such as RS485/Modbus support and baseline budget expectations for remote IoT setups.
- Peer-reviewed field trials reported in 2025 demonstrate DO and ammonia sensors achieving accuracy levels above 98% when properly calibrated and maintained — underscoring that sensor quality and lifecycle management materially affect outcomes.
Regulatory and operational headwinds
Regulatory frameworks and compliance costs are a material factor in adoption economics. Our dynamics analysis integrates public sources showing significant compliance costs and evolving permit regimes in major markets. International guidelines and directives—ranging from FAO recommendations on water-quality thresholds to regional directives that set stricter dissolved-oxygen and ammonia limits—are raising minimum technical specifications for monitoring systems. In the U.S., permit and reporting regimes under the Clean Water Act and national strategic initiatives to streamline aquaculture regulation are influencing capital deployment timelines and operator obligations.
Strategic playbook for 2026
- Prioritize modular, API-first architectures: Build monitoring stacks that allow phased upgrades to sensors, analytics, and connectivity without wholesale replacement.
- Run high-quality pilots with measurable KPIs: Define biomass, feeding efficiency, and compliance KPIs up front and test end-to-end integration under production conditions for a full seasonal cycle where possible.
- Lock in data governance and ownership: Contracts should preserve data rights and define allowable secondary uses; this directly affects downstream monetization and partnership options.
- Partner with connectivity specialists early: Off-grid and offshore projects require bespoke satellite or LPWAN solutions; embedding connectivity into procurement avoids deployment delays.
- Quantify and insure against sensor drift: Include calibration schedules, remote diagnostics, and warranty terms in procurement documents; sensor accuracy materially impacts control-loop decisions and ROI.
- Evaluate M&A and partnership targets: Consolidation is a likely outcome as platforms seek customer stickiness via integrated services (feeding, health, traceability); evaluate targets for data assets and installed base.
What PW Consulting’s report enables
For executives and investment committees, the full PW Consulting study translates market momentum into executable programs: procurement decision trees, contract templates, technology selection matrices, and ROI models that can be applied to live projects. For product teams, the report offers a prioritized feature roadmap informed by farmer needs, field-trial evidence, and regulatory thresholds. For investors and M&A teams, the report identifies strategic gaps and arbitrage opportunities across geography and technology segments.
To preserve actionable differentiation, the full study retains granular vendor scorecards, deployment-level pricing, and segment-specific forecasts that are not disclosed in this briefing. Those subscribers who require the underlying datasets, sensitivity models, or bespoke consulting support to convert insight into operational plans should consult the complete report.
Next steps
PW Consulting’s Remote Monitoring System for Aquaculture Market study is published as a strategic resource for 2026 planning cycles. Organizations seeking to accelerate deployment, validate supplier claims, or construct defensible investment theses should access the full report and accompanying tools. For tailored briefings or to commission a custom scenario analysis aligned to a specific farm type, species, or regulatory regime, PW Consulting is available to deliver accelerated advisory engagements.
Visit the PW Consulting report page to review the full table of contents, sample scorecards, and subscription options. The full publication—complete with modeling spreadsheets, vendor matrices, and procurement templates—provides the granular intelligence necessary to translate market growth into profitable, compliant operations in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Remote Monitoring System For Aquaculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Robust 6.0% CAGR for Critical Care Blood Gas Analyser Market Through 2032
By pmarketresearch, 2026-07-13
Critical Care Blood Gas Analyser Market — Strategic Briefing (PW Consulting)
Executive summary
PW Consulting’s latest market study on the Critical Care Blood Gas Analyser market (base year 2025; historical 2020–2025; forecast 2026–2032) frames a commercial landscape that is both mature and receptive to technology-led disruption. The global market expanded from roughly USD 760 million in 2020 to about USD 1,050 million in 2025 and is projected to continue growing at a steady compound annual growth rate (CAGR) of 6.0% through 2032. By the terminal year of our forecast the market approaches USD 1.58 billion based on current trajectories and observable adoption patterns.
Critical Care Blood Gas Analyser Market
Two structural features are immediately relevant to strategy in 2026: (1) a concentrated supplier base, with the top three suppliers controlling a substantial portion of sales and the top five showing even greater dominance, and (2) accelerating adoption of point-of-care capabilities and quality-control innovations that materially change procurement and clinical workflows in intensive care and emergency settings. Together these dynamics create both barriers and targeted opportunities for established vendors, tier‑2 entrants, and strategic investors.
Critical Care Blood Gas Analyser Market
Why this report matters for 2026 decisions
- Time-sensitive regulatory and product developments are reshaping procurement cycles in hospitals and urgent care settings — decisions taken in 2026 will determine competitive position through the next contract cycle.
- Market growth is predictable at the macro level but heterogenous at the product and channel level; our report converts that predictability into operational scenarios and revenue-impact models for FY26 planning.
- Consolidation among leading vendors increases the value of tactical partnerships, OEM supply agreements and targeted M&A — all of which we quantify qualitatively and through scenario modeling to support board-level choices.
What the report delivers — practical, actionable content
- Validated market size and baseline trajectory (2020–2025) and forward projections (2026–2032) by revenue and growth drivers, expressed in USD Million to align with financial planning.
- Scenario-based revenue and ROI models calibrated to different commercialization strategies (direct sales, distributor-led, OEM partnerships, and consumable/service-centric models).
- Competitive dossiers and product feature scorecards for leading vendors, including product positioning, technology differentiators, regulatory status, and recent product/clearance milestones.
- Regulatory and reimbursement map focusing on the principal jurisdictions that shape critical care procurement cycles and hospital purchasing policies.
- Go‑to‑market playbooks that translate insights into sales motions, tender strategies, and hospital lab/ICU value propositions for 2026 launches.
- M&A and partnership heatmaps to prioritize targets and partnership archetypes by strategic fit, technical complementarity, and speed-to-market.
- Operational checklists for production scaling, quality management, and post‑market surveillance necessary to meet Class II medical device expectations and to accelerate approval timelines.
Competitive landscape — names, strengths, and recent shifts
The market is led by a small set of established medtech companies with deep installed bases and integrated service ecosystems. Our report provides concise, comparative intelligence on each major competitor to help you select the right counter‑strategies.
Critical Care Blood Gas Analyser Market
- Radiometer Medical ApS (Danaher) — Brønshøj, Denmark ( https://www.radiometer.com). Known for ABL platforms optimized for ICU and emergency settings; recent regulatory progress underscores ongoing investment in critical care usability and throughput.
- Werfen (Instrumentation Laboratory) — Barcelona, Spain ( https://www.werfen.com). The GEM Premier family emphasizes intelligent quality management at the point of care, positioning the company to capture buyers prioritizing in-field QC and error mitigation.
- Siemens Healthineers — Erlangen, Germany ( https://www.siemens-healthineers.com). Offers RAPIDPoint/RAPIDLab systems focused on integration with hospital IT and comprehensive parameter sets, attractive to large health systems seeking consolidated device fleets.
- Nova Biomedical — Waltham, MA, USA ( https://www.novabiomedical.com). Their Stat Profile family extends analytical breadth (gases, electrolytes, metabolites, CO‑Oximetry, hematology), creating value where multi‑parameter reporting shortens clinical decision loops.
- Abbott Laboratories — Abbott Park, IL, USA ( https://www.globalpointofcare.abbott). The i‑STAT line is a leading portable solution for rapid bedside testing and acute care scenarios.
- Other notable players include Medica Corporation, OPTI Medical Systems (IDEXX), F. Hoffmann‑La Roche, Chengdu Seamaty Technology, and EDAN Instruments; each contributes differentiated capabilities in cost, features, or regional reach.
Recent, market-relevant events highlighted in the report include regulatory clearances and product launches that materially affect competitive positioning — for example, late‑2024 and 2023 milestones that expanded on‑label capabilities and sample handling options. These events are analysed for their likely impact on procurement cycles and switching costs.
Market dynamics and regulatory context
Blood gas analysers remain essential clinical tools in ICU and emergency medicine for acid‑base, oxygenation and metabolic assessment. From a regulatory perspective, blood gas analyser systems are commonly regulated as Class II medical devices under U.S. FDA frameworks — a consideration that imposes predictable design controls, verification pathways, and post‑market obligations. Innovations that improve in‑field quality control (for example, hemolysis detection) and that enable lower sample volumes or micro‑capillary operation materially reduce clinical friction and create new adoption vectors.
Key technology vectors covered in the report include:
- Point‑of‑care portability and robustness vs. centralized benchtop performance tradeoffs.
- Advanced QC and automation (including hemolysis detection) to reduce false results and retests.
- Multi‑parameter analytics (CO‑oximetry, electrolytes, metabolites) and calculated indices that shorten clinical decision loops.
- Data interoperability and middleware integration for seamless EMR and lab information system workflows.
Strategic implications for 2026 — recommended actions
- Product strategy: Prioritise features that reduce clinical friction (sample handling, hemolysis detection, rapid QC) and modular designs that allow field upgrades. Where feasible, bundle analytics with consumables and service contracts to stabilize recurring revenue.
- Regulatory readiness: Align development roadmaps with Class II expectations and prepare pre‑submission engagements in major markets. Leverage cleared predicate appliances and recent precedent clearances to accelerate time-to-market.
- Commercial model: Test mixed go‑to‑market approaches—direct sales in large health systems, channel partners in fragmented markets, and OEM partnerships for device-in-device placements. Use value-based tendering playbooks anchored on clinical outcomes and total cost of ownership.
- Partnerships & M&A: Evaluate tuck‑in acquisitions that add complementary assay capabilities or regional distribution strength; assess strategic OEM agreements to access consumables or software ecosystems quickly.
- Supply chain & operations: Build supplier diversification and certificate-driven quality systems to mitigate lead-time volatility and to meet hospital procurement requirements.
- Commercial analytics: Deploy our scenario models to stress-test pricing, service plans, and rollout sequencing to quantify FY26 revenue impacts under different adoption curves.
How to use the PW Consulting report in boardroom and market planning
This study is intentionally structured to serve as both evidence base and playbook. Executive summaries and one‑page dashboards are designed for board briefings; modular models and scenario outputs support CFO-level planning and product roadmap committees. For commercial teams, the go-to-market playbooks and competitor dossiers reduce time-to-action by translating market signals into field-ready tactics for the 2026 procurement cycle.
Next steps — where to get the full intelligence
This briefing outlines the strategic takeaways we believe will matter most for decisions made in 2026, while preserving the full analytic depth and segment-level tables for licensed report subscribers. The published report contains the granular regional and end‑user split tables, detailed product‑level revenue build-ups, supplier market‑share reconstructions, and downloadable forecast models that underpin the scenarios summarized here.
Contact PW Consulting or visit our report page to request the complete market dataset, model files, and a bespoke briefing tailored to your organisation’s specific strategic questions.
For detailed analysis of this topic, please visit the official page: Critical Care Blood Gas Analyser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biopharma Autoclaves Market Hits USD 2,488.58 Million in 2025, Poised to Grow at an 8.5% CAGR
By pmarketresearch, 2026-07-13
Strategic Imperatives for 2026: Navigating the Biopharmaceutical Autoclaves Market
PW Consulting’s latest market study on Biopharmaceutical Autoclaves delivers a focused strategic playbook for executive teams making CapEx, procurement, and M&A decisions in 2026. The global market has matured into a clear growth corridor: from an estimated USD ~2.49 billion in 2025, the market is positioned to expand at a compound annual growth rate (CAGR) of 8.5% across the 2026–2032 forecast window, reaching roughly USD ~4.41 billion by 2032. That macro trajectory—backed by granular scenario modelling in our report—creates both risk and opportunity for buyers, manufacturers, and service providers across the biopharma ecosystem.
Biopharmaceutical Biopharma Autoclaves Market
Why this market matters for 2026 planning
-
Acceleration of biologics and advanced therapies. The rapid build-out of biologics manufacturing capacity, together with scaled investment in cell & gene therapies and vaccine platforms, is increasing demand for validated sterilization solutions that can meet complex process requirements.
Biopharmaceutical Biopharma Autoclaves Market -
Regulatory tightening and validation burden. Recent standard-setting updates (notably ISO 17665:2024 and the continuing relevance of EN 285 and EU GMP expectations such as Annex 15) are raising the bar on design, qualification, and routine control of moist heat sterilization—the practical implication is higher front-end investment and greater emphasis on digital validation workflows.
Biopharmaceutical Biopharma Autoclaves Market -
Technology convergence. The leading vendors are embedding IoT, predictive analytics, and AI-assisted cycle validation into autoclave platforms—shifts that change both procurement criteria and the aftermarket services equation.
-
Capital and operational trade-offs. Construction and start-up budgets for new biomanufacturing sites are substantial; autoclaves remain a material line item within these projects. Buyers must reconcile unit costs, throughput requirements, validation timelines, and scalable footprints.
What the PW Consulting report delivers (practical, decision-focused content)
-
Market sizing and scenario forecasts through 2032 with transparent modelling assumptions—illustrating upside/downside cases for capacity expansion and regulatory-driven retrofit cycles.
-
Procurement and CapEx playbooks—templates to phase investments, optimise total cost of ownership, and align delivery timelines with validation milestones (IQ/OQ/PQ).
-
Vendor scorecards and selection frameworks—objective criteria and weighting matrices tailored to biopharma requirements (compliance, automation, throughput, integration, and global service footprint).
-
Validation and compliance checklists—practical IQ/OQ/PQ roadmaps cross-referenced to ISO 17665:2024 and EU GMP expectations to reduce qualification risk.
-
Technology adoption roadmaps—assessing integration of IoT sensors, AI-driven cycle validation, and goods handling automation to help buyers prioritise investments with measurable ROI.
-
M&A and supplier risk snapshot—strategic implications of recent industry actions and the likely consolidation pathways over the medium term.
-
Downloadable Excel models and procurement templates for buyer teams to stress-test options under varying demand, CAPEX availability, and cycle-time requirements.
Competitive landscape — what the field looks like in 2026
The autoclave market for biopharmaceutical applications is balanced between global players that supply high-throughput, validation-ready platforms and a broad set of specialised vendors that serve niche laboratory, bench-scale, and bespoke manufacturing needs. Our concentration analysis shows a market where the top three suppliers account for a meaningful but not dominating share of revenue, and the top five firms capture just over half of industry revenues—this structure sustains both competitive differentiation and opportunities for focused entrants.
-
Global systems suppliers (examples include STERIS plc and Getinge AB) are competing on scale, regulatory pedigree, and system integration—investing heavily in automation, digital validation, and goods handling to service high-volume biologics and vaccine production.
-
Specialised process equipment manufacturers (such as Fedegari Srl and BMT USA) differentiate through cGMP-engineered solutions for terminal sterilization and complex process integration—an attractive proposition for cell & gene therapy and biologics manufacturers with unique process needs.
-
Regional and lab-focused vendors (including Consolidated Sterilizer Systems, Astell Scientific, Priorclave, and others) remain important partners for R&D and early-stage manufacturing due to speed-to-deploy and flexibility.
-
Large equipment and life-science groups are selectively consolidating sterilization capabilities. Recent strategic moves—product launches with IoT/AI-enabled validation and a notable acquisition integrating validation software into sterilization portfolios—signal that technology integration and software-enabled differentiation are primary battlegrounds.
-
Manufacturers from high-capacity regions are increasingly competitive on price and scale, but buyers are prioritising documented compliance, lifecycle service, and digital validation capability over lowest-cost procurement.
Recent vendor moves that signal market direction
-
IoT and AI-enabled product introductions are moving from prototype to production-ready solutions—enabling automated cycle documentation and predictive maintenance that materially reduce qualification and operational friction.
-
Strategic partnerships focused on modular, scalable autoclaves tailored to advanced therapies indicate a shift toward pre-validated, application-specific systems that shorten time-to-clinic and time-to-market.
-
Acquisitions that combine sterilization hardware with validation software are creating vertically integrated offerings that bundle hardware, lifecycle compliance, and analytics—changing how procurement evaluates total value.
Five priority actions for executive teams in 2026
-
Prioritise modularity and scalability. Insist on architectures that enable phased capacity expansions, avoiding large lump-sum investments that may become stranded if process needs evolve.
-
Demand digital validation as standard. Require vendors to provide automated cycle validation, secure data handling, and clear audit trails aligned to ISO 17665:2024 and EU GMP Annex 15; factor reduced validation lifecycle costs into procurement calculus.
-
Integrate service and spare parts SLAs into TCO. For critical sterilization equipment, uptime and rapid response are as important as unit price—build long-term service agreements and local spares strategies into vendor selection.
-
Stress-test supply chain and lead times. Plan procurement timelines to accommodate long-lead components and potential regional bottlenecks; consider dual-sourcing for mission-critical assets.
-
Embed scenario-based CapEx planning. Use the report’s downloadable models to run demand, regulatory, and technology adoption scenarios—this reduces bias in capacity planning and improves timing for procurement versus retrofit decisions.
How PW Consulting’s report supports fast, defensible decisions
We designed this study to bridge board-level strategy and operational execution. The report does not stop at market direction: it equips procurement, engineering, quality, and regulatory teams with templates, scorecards, and validation checklists that can be operationalised during vendor selection and site qualification. The combination of forward-looking demand modelling, vendor benchmarking against compliance and digital capabilities, and practical CapEx phasing tools means leadership teams can convert macro trends into clear, defensible procurement roadmaps for 2026.
What we intentionally withhold in this preview
In order to preserve the actionability of the primary research and to encourage structured engagement with our full intelligence set, this release omits detailed sub-segment level breakdowns and granular regional share tables. The full report contains those breakouts, including segment-specific forecasts, vendor market shares by application and configuration, and downloadable models that you can adapt to your facility or portfolio. If your team is evaluating new-build or retrofit options in 2026, the full dataset and our advisory workshop will materially shorten your decision cycle.
For executive teams preparing procurement, validation, or M&A decisions next year, the right next step is a short briefing with our industry practice. PW Consulting can map the public market intelligence to your tolerance for innovation risk, compliance posture, and capacity timeline—converting the market’s 8.5% CAGR opportunity into a concrete, staged investment plan that de-risks time-to-operation.
For detailed analysis of this topic, please visit the official page: Biopharmaceutical Biopharma Autoclaves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com