

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vacuum Atmosphere Furnace Market Tops USD 612.45 Million in 2025, Forecast to Reach USD 1,037.85 Million by 2032 at a 7.85% CAGR

Vacuum Atmosphere Furnace Market 2026: Strategic Intelligence Briefing for Decision-Makers
As companies position for growth in 2026, senior leaders in manufacturing, aerospace, energy, and advanced materials require a compact, actionable line of sight into the vacuum atmosphere furnace market. PW Consulting’s latest market research synthesizes historical performance, forward-looking forecasts, competitive motion, supply-chain dynamics, and regulation-driven technology shifts to provide that line of sight — without giving away the proprietary segment-level granularity reserved for the full report.
Vacuum Atmosphere Furnace Market
Market at a Glance: Growth, Scale, and Momentum
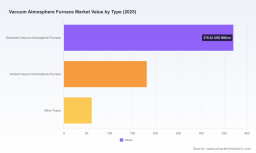
The vacuum atmosphere furnace market has shown steady expansion across the 2020–2025 historical window, rising from roughly USD 412 million in 2020 to an estimated USD 612 million in the 2025 base year. Our forecast models, calibrated with manufacturing capex cycles, materials demand, and regulatory tailwinds, project continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 7.85%. By 2032 the market is expected to exceed USD 1.03 billion, underscoring material opportunities for equipment suppliers, service providers and downstream manufacturers that can capture mid- to long-term demand.
Vacuum Atmosphere Furnace Market
Two structural forces are driving this scale: (1) ongoing capital expenditure among aerospace, semiconductor and advanced metallurgy customers that favor controlled-atmosphere processing; and (2) retrofit and replacement demand as energy-efficiency and emissions regulations increasingly constrain older furnace assets. These forces create both near-term serviceable revenue and longer-term platform replacement cycles.
Vacuum Atmosphere Furnace Market
What the PW Consulting Report Delivers
- Integrated market model: A transparent top-down forecast (2026–2032) plus back-tested historical reconciliation (2020–2025) that enables scenario analysis under different macro and commodity assumptions.
- Practical procurement playbook: Sourcing strategy templates, lead-time mitigation tactics, and supplier scorecards for negotiating turn-key and custom furnace solutions.
- Technology and product roadmap: Comparative assessment of horizontal vs. vertical architectures, quenching technologies, control systems, and energy-efficient retrofits — with guidance on R&D prioritization.
- Supply chain & materials risk matrix: Actionable mitigants for graphite and specialty alloy constraints, including dual-sourcing strategies and inventory buffers calibrated to lead-time elasticity.
- Competitive positioning and M&A playbook: Profiles of market-leading suppliers, CRx concentration analysis, and inorganic growth scenarios tailored to different buyer archetypes.
- Regulatory and sustainability checklist: Region-aware compliance triggers, energy-performance KPIs, and CAPEX ROI models that quantify payback for cleaner furnace technologies.
Note: This briefing intentionally omits the granular, per-segment revenue splits and unit-level price decks included in the complete report to preserve the value of the premium dataset.
Competitive Landscape: Strategic Profiles and Implications
-
Ispen (Ipsen) — Cherry Valley, IL, USA: A full-line supplier with series offerings optimized for aerospace, medical and industrial heat treating. Ipsen’s breadth is a defensive advantage for customers seeking end-to-end service and certification continuity. Strategy implication: buyers should benchmark total cost of ownership (TCO) and service footprint when comparing Ipsen to more specialized contenders.
-
Solar Manufacturing — Sellersville, PA, USA: Known for advanced vacuum furnaces incorporating high-pressure gas quenching and energy-efficiency features. Recent shipments to aerospace suppliers reinforce its relevance for precision component heat treatment. Strategy implication: OEMs prioritizing cycle time and surface integrity should evaluate Solar’s high-pressure platforms against retrofit alternatives.
-
Centorr Vacuum Industries — Nashua, NH, USA: Offers extremely high-temperature and specialized furnaces used in R&D and niche production applications, with a long installed-base record. Strategy implication: companies in advanced materials and research-intensive sectors should consider Centorr for bespoke, high-temperature needs where standard platforms underperform.
-
SECO/WARWICK — Meadville, PA (Group: Poland): Provider of high-vacuum and brazing systems across aerospace, automotive and nuclear segments. The Group’s geographic footprint is an advantage for global programs. Strategy implication: multi-site manufacturers should evaluate SECO/WARWICK where commonality of equipment simplifies qualification and cross-site standardization.
-
AVS Inc. — Ayer, MA, USA: A custom-builder focused on meeting exacting temperature and vacuum specifications. Strategy implication: AVS is a natural partner for customers requiring tight process control and bespoke thermal solutions rather than commodity platforms.
-
ECM Technologies — Grenoble, France: Strong in brazing, sintering and vacuum heat treatment for European metallurgy and aerospace supply chains. Strategy implication: European manufacturers focused on certification and localized service should prioritize ECM in vendor shortlists.
-
Camco Furnace — San Carlos, CA, USA: Specializes in hydrogen and high-vacuum solutions up to very high temperatures. Strategy implication: Companies exploring hydrogen atmosphere processing or cold-wall architectures should evaluate Camco’s offerings for process-specific advantages.
-
ALD-Holcroft — Wixom, MI, USA: Delivers vacuum technologies targeted at advanced heat treatment processes with emphasis on industrial-scale throughput. Strategy implication: suitable for high-volume producers seeking continuous-improvement partnerships.
Industry concentration metrics highlight an outcome of moderate fragmentation with pockets of consolidation: the top three players account for a meaningful share of revenue, while the top five control a clear majority, indicating acquisition opportunities for firms looking to scale quickly or consolidate supply chains.
Recent Market Developments: Signals to Watch
- 2026: Installation of a 10-bar vacuum furnace at a major U.S. heat-treating facility signals increasing adoption of high-pressure, high-throughput equipment for aerospace and heavy-industry processing.
- 2025: Multiple new shipments and hot-zone upgrades to leading aerospace suppliers — evidence of ongoing modernization and demand for higher-integrity process environments.
- 2025: Nadcap merit status awarded to a facility for heat treating and brazing underlines the continuing importance of accredited processing capacity for aerospace supply-chain compliance.
Collectively, these events reflect two overlapping trends: investment in higher-performance equipment to meet advanced material specifications, and expansion of certified processing capacity to absorb rising demand from regulated, quality-driven industries.
Segment Dynamics, Risks and Near-Term Disruptors
Three predominant dynamics will shape supplier and buyer strategies in 2026:
- Materials supply risk: Constraints in high-purity graphite and export controls have increased cost and lead-time volatility for furnace hot zones and insulation systems. Firms should model production schedules with extended lead-times and consider inventory hedging or alternate material investments.
- Regulatory pressure: European energy-efficiency and emissions requirements are accelerating demand for cleaner furnace technologies and higher-efficiency controls. This shifts buyer preference toward vendors able to demonstrate certified energy-performance improvements and lifecycle emissions reductions.
- Technology substitution and retrofits: As customers weigh the economics of replacing legacy furnaces versus retrofitting modern control and quench systems, suppliers offering modular, upgradeable architectures will capture aftermarket and conversion revenue.
These dynamics magnify the value of a dual-track strategy that protects short-term throughput while investing in long-term efficient platforms.
Actionable Strategic Playbook for 2026
- For OEMs and Asset Owners: Prioritize qualification paths that preserve supply continuity (multi-vendor trials) and include service-level agreements for spare parts tied to graphite-critical subassemblies. Run accelerated ROI models to validate energy-efficiency retrofits where regulatory pressure is highest.
- For Equipment Suppliers: Invest in modular designs enabling field upgrades, expand service networks in regulated markets, and develop commodity procurement partnerships to mitigate graphite supply shocks. Consider targeted M&A to increase scale in certification-heavy segments.
- For Investors and Private Equity: Seek platform investments in suppliers with strong service capabilities and global certification footprints. Use the market’s moderate concentration to structure buy-and-build strategies that capture aftermarket revenue and standardize spare-parts catalogs.
- For R&D and Product Strategy: Accelerate development of alternative hot-zone materials and closed-loop energy recovery technologies. Differentiate through digital process controls that reduce cycle variability and enable predictive maintenance monetization.
Why PW Consulting’s Intelligence Matters for 2026
Decisions in 2026 will be shaped less by single-year demand spikes and more by strategic positioning across supply-chain resilience, regulatory compliance, and the ability to monetize aftermarket services. PW Consulting’s report converts raw market indicators into decision-ready options: quantified trade-offs for CAPEX vs. retrofit, supplier scorecards for procurement, and an M&A playbook mapped to concentration dynamics. The analysis is deliberately tactical — enough to inform board-level capital allocation and procurement plans — while withholding the full segment-level datasets that form the report’s competitive advantage.
Next Steps
For organizations preparing budgets, supplier negotiations or inorganic growth strategies in 2026, access to the full dataset and scenario models will materially reduce execution risk. The full PW Consulting Vacuum Atmosphere Furnace Market Report contains the detailed segmentation, regional forecasts, unit pricing models and supplier scorecards required to convert strategy into executable plans. Contact our team for a briefing or to request the full report and bespoke advisory engagements tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Vacuum Atmosphere Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com