

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Residential Solar Power Solutions Poised for Rapid Expansion — 14.02% CAGR Projected Through 2032, Report Finds

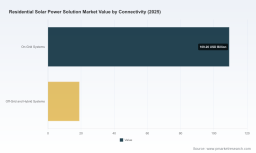
Residential Solar Power Solutions Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s Residential Solar Power Solution Market report (base year 2025; forecast 2026–2032) delivers a concise, actionable intelligence set designed for executive teams making investment, sourcing, product, and M&A decisions in 2026. The global market reached approximately USD 128.2 Billion in 2025 and—driven by continued residential electrification, storage adoption, and falling balance-of-system costs—is projected to grow at a compound annual growth rate of roughly 14.02% through 2032, reaching the low hundreds of billions by the end of the forecast window.
Residential Solar Power Solution Market
Why this report matters for 2026 planning
- High-growth context: A sustained double-digit CAGR creates a widening set of strategic options—but also amplifies supply-chain and regulatory risk for players who delay decisive moves.
- Policy inflection points: Recent regulatory shifts and trade enforcement actions materially alter market access and cost structures for suppliers and integrators in 2026.
- Commercial inflection points: The convergence of solar + storage + smart energy management is re-defining product bundles and the revenue model for residential offerings.
- Competitive positioning: Moderate market concentration at the top (CR3 ~34.5%, CR5 ~42.8%) means scale advantages exist, but there is also room for differentiated challengers through technology, services, or channel control.
Key dynamics shaping 2026 strategy
- Supply-side pressure and raw-material cost swings — Special focus: polysilicon. Industry reporting showed a notable spot-price uptick in polysilicon in early 2025 (circa +12% in Q1 2025), which, together with module capacity cycles, can compress supplier margins and translate into intermittent price volatility for system integrators.
- Policy and trade interventions — U.S. policy moves in 2025–2026 (including domestic tax-credit changes and tariff/quota enforcement periods) have created near-term shifts in demand economics and import sourcing strategies. These changes require scenario-based planning to understand how pricing and market access evolve through 2026.
- Residential system cost trends — Benchmarks from the market indicate U.S. residential system pricing ranges observable in H1 2025; these remain a critical commercial input for pricing, rebate modeling, and homeowner ROI communications heading into 2026.
- Product convergence — Energy storage and advanced inverter/control platforms are moving from “optional upsell” to core elements of competitive residential propositions. Integrators that combine hardware, software, and financing will capture higher lifetime value.
- Consolidation and supplier concentration — Leading module and inverter manufacturers continue to expand capacity and vertically integrate. While top-tier suppliers enjoy procurement and technology advantages, channel control by installers, software players, and financiers will be decisive for go-to-market success.
Competitive landscape — strategic implications
Our competitive assessment synthesized public profiles, shipment trends, and capability mapping for leading suppliers and system suppliers. The market features a mix of very large module manufacturers, specialized inverter and microinverter innovators, and integrated home energy providers. Representative strategic positions include:
Residential Solar Power Solution Market
- Large-module manufacturers (scale & vertical integration): Major PV module producers emphasize high-efficiency monocrystalline technologies and vertical integration across wafers-to-modules. Their strengths lie in cost control at scale, R&D investment into efficiency gains (including N-type technologies), and global distribution networks. For 2026, these players will continue to shape pricing corridors and availability of higher-efficiency modules suited for residential rooftops.
- Performance-differentiated suppliers (premium efficiency & specialty cells): A subset of manufacturers focuses on premium panels optimized for constrained-rooftop applications or aesthetic-sensitive deployments. These firms can capture premium ASPs (average selling prices) but face pressure if polysilicon and cell-cost spreads compress.
- Power electronics leaders (inverters & integrated control): Companies focused on microinverters, DC-optimizer systems, and home-energy orchestration platforms provide clear customer-value differentiation via improved production, module-level monitoring, and seamless storage integration. These capabilities are a primary battleground for installers seeking higher-margin service offerings.
- Integrated home-energy OEMs & assemblers: Vendors combining panels, storage, and software create simpler procurement pathways for residential customers and installers. Their ability to deliver unified warranty, financing, and experience is reshaping purchase decision criteria.
Strategic implications for 2026 include defending margin via vertical hedging, selectively partnering with differentiated inverter/EMS providers, and accelerating product-service bundles that lock-in customers across lifecycle touchpoints (sales, financing, warranty, upgrades).
Residential Solar Power Solution Market
What’s in the PW Consulting report — practical, decision-ready content
We designed the report to support decisions made in 2026 by corporate strategy, corporate development, product, supply chain, and commercial teams. Highlights of the deliverables include:
- Market sizing and topline forecasts (2020–2032) with scenario variants reflecting material price shocks, tariff cases, and rapid storage adoption pathways.
- Supplier and technology benchmarking decks that score manufacturers and platform providers across manufacturing scale, technology roadmap, channel relationships, and risk exposure—presented as a management-ready scorecard (high-level view in the public summary; full scorecards in the report).
- Supply-chain stress tests and procurement scenarios that model the impact of polysilicon price spikes, quota/duty events, and shipping disruptions on landed module cost and system gross margins.
- Commercial playbooks for product bundling, installer partnerships, financing constructs, and price communication strategies for different homeowner segments—each with example P&L and payback illustrations.
- M&A and partnership pipeline: prioritized capability gaps and target archetypes, plus due-diligence checklists tailored for residential solar acquisitions (technology, O&M, installer networks, storage).
- Regulatory playbook and scenario matrix: mapping major near-term policy changes and enforcement actions to demand elasticity, subsidy exposure, and regional go-to-market risk.
Actionable recommendations for 2026 (for CEOs, CPOs, and Heads of Strategy)
- Pursue supplier diversification with contractual hedges: lock forward volumes and index-linked pricing where possible to insulate gross margins from polysilicon volatility.
- Prioritize storage-enabled offerings: structure bundled propositions that make energy storage the default upgrade for higher-LTV customers, with financing that smooths upfront economics.
- Accelerate software and service capabilities: invest in EMS, monitoring, and remote O&M to differentiate on lifecycle economics rather than one-time hardware sales.
- Re-assess channel economics under changing policy scenarios: build flexible go-to-market playbooks for both subsidy-rich and subsidy-constrained environments, and stress-test customer acquisition cost assumptions.
- Stand ready for trade/regulatory developments: monitor quota windows, duty announcements, and anti-dumping cases closely; incorporate rapid sourcing-switch capabilities into procurement playbooks.
- Use targeted M&A to fill capability gaps: prioritize targets that offer installer footprints, storage technology, or software stacks that immediately lift margins and shorten time-to-market for integrated propositions.
What we intentionally withheld in this preview — and why
To preserve the report’s value as a decision-grade deliverable, this public preview intentionally omits granular segment-level revenue tables, proprietary supplier scorecards, and the full set of scenario-modeled P&L impacts. Those detailed data points and downloadable templates are included in the full PW Consulting report and are accessible via our report portal for clients and subscribers.
Next steps
For executive teams preparing 2026 budgets and strategic plans, the full report is the recommended starting point for scenario workshops, procurement term negotiations, product roadmap updates, and M&A screening. PW Consulting also offers tailored advisory sessions and data workshops that overlay your company’s P&L and supplier portfolio onto our market model to produce bespoke action plans for the year ahead.
To request the full report, a briefing, or a customized scenario run for your organization, visit the PW Consulting research center or contact your account lead. In a market expanding at a mid-teens CAGR with fast-moving policy and raw-material headwinds, having the right market intelligence—and the operational plans to act on it—will determine who leads the residential energy transition in 2026.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com