

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Satellite Control Service Market Poised to Expand at 7.45% CAGR During 2026–2032, New Report Finds

Satellite Control Service Market 2026: Strategic Intelligence to Guide C-Suites and Program Managers
Executive summary
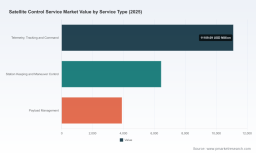
PW Consulting’s latest Satellite Control Service Market report, with base year 2025 and a forecast horizon through 2032, distills the commercial and government dynamics that will shape mission-critical satellite operations decisions in 2026. After a sustained expansion from 2020 through 2025, the market reached roughly USD 21.45 billion in 2025 and is projected to grow at a compound annual growth rate of approximately 7.45% across the 2026–2032 forecast window, reaching the mid‑30 billion USD range by the end of the period. This trajectory reflects accelerated demand for resilient telemetry, tracking & command (TT&C), multi-orbit operations, and outsourced ground services models that reduce capital intensity for satellite owners and operators.
Satellite Control Service Market
Why this report matters for 2026 decision-making
Space programs that fail to align procurement, operations and regulatory strategy in 2026 risk operational fragility and suboptimal total cost of ownership over a satellite’s lifecycle. This report is designed as an executable intelligence product for executives, program managers, investors and policymakers facing three interdependent choices: build or buy (infrastructure vs. GSaaS), mono-orbit vs. multi-orbit operational posture, and local compliance vs. global access strategies.
Satellite Control Service Market
-
Timing: With regulatory windows and spectrum access decisions maturing in early 2026, strategic procurement and partnership decisions made this year will determine 2027–2029 mission capabilities and margins.
Satellite Control Service Market -
Capital allocation: The market’s growth path amplifies both opportunity and risk—investors and operators must balance near-term GSaaS engagements against long-term investments in distributed ground infrastructure.
-
Operational resilience: Trends toward constellation scale, mixed orbits, and shorter mission lifecycles make automated, software‑defined control architectures a requirement rather than an option.
What the report contains — practical, decision‑ready content
PW Consulting’s report goes beyond market sizing to deliver operational playbooks and procurement-ready artifacts that teams can use immediately. Core contents include:
-
Executive summaries and scenario models that translate macro growth into portfolio‑level revenue and cost trajectories under alternative business models (in-house operations, hybrid outsourcing, GSaaS).
-
Vendor evaluation frameworks and procurement checklists designed to shorten RFP cycles while reducing vendor lock-in risk (including recommended contract clauses for continuity-of-operations, spectrum contingency, and cyber assurance).
-
Operational architecture templates for single-point and distributed TT&C—covering automation, mission planning interfaces, latency profiling, and SLAs aligned to mission classes (commercial, civil/scientific, defense).
-
CapEx vs. OpEx decision matrices that quantify break-even horizons for ground infrastructure purchases versus long-term service agreements, adjusted for mission tempo and risk tolerance.
-
Regulatory and market-access trackers that map near-term legislative and agency actions to operational impacts—so teams can prioritize licensing, spectrum filings and stakeholder engagement.
Competitive landscape — who matters and why
The satellite control services market is shaped by a mix of global fleet operators, ground‑segment specialists, defense contractors, and nimble GSaaS providers. Rather than a winner‑takes‑all topology, competition is forming around capability bundles—end‑to‑end mission services, geographic diversity of ground access, multi‑orbit expertise, and 24/7 operational continuity. Key strategic players profiled in the report include established operators and specialized providers with differentiated propositions:
-
KSAT (Kongsberg Satellite Services) — leader in globally distributed ground networks and multi-orbit TT&C, increasingly positioning itself as a mission-adapted operator for LEO through lunar missions. Its continued network expansion in early 2026 reinforces its role as a resilience partner for operators seeking geographic redundancy.
-
SES S.A. — combines global antenna assets with operations centers to offer lifecycle flight-operations services and emergency TT&C restoration; attractive to operators needing integrated continuity solutions.
-
Viasat Inc. — leverages managed connectivity and network operations expertise into satellite control services; recent multi-year contract renewals with defense customers underscore strength in government and joint-base mission support.
-
Intelsat, Eutelsat, Telesat — incumbent fleet operators who balance in‑house control capabilities with third-party ground partnerships to optimize capacity and resilience across commercial and government customer segments. Recent financial and operational updates from select incumbents signal continued investment in control and ground infrastructure.
-
Defense and systems integrators (Kratos, Lockheed Martin, Airbus, General Dynamics, L3Harris, RTX) — these firms supply hardened command-and-control systems, cyber-hardened ground equipment, and full program management for government and defense customers; strategic for customers prioritizing security and sovereign control.
-
Newer GSaaS entrants (Atlas Space Operations, Leaf Space, RBC Signals) — focused on elastic, networked ground services and rapid integration via cloud-native operations models; attractive to smallsat constellations and commercial entrants seeking to avoid CapEx and accelerate time-to-first-contact.
Competitive moves to watch in 2026 include further ground network densification, horizontal consolidation between GSaaS and systems integrators, and an expansion of managed operations contracts with defense agencies. Operators that can combine multi-orbit operational depth with service-level guarantees and cyber maturity will take the commercial lead.
Market dynamics and regulatory context
Several cross-cutting trends and near-term regulatory actions are reshaping strategic trade-offs for 2026:
-
Spectrum and licensing reform: Regulatory initiatives in late 2025 and early 2026 have accelerated prospective access to spectrum and simplified licensing timelines in major markets. For commercial operators this shortens the runway for service launches but increases competition for spectrum-dependent services.
-
Infrastructure approvals and harmonization: Measures to accelerate infrastructure permitting — most notably in major economic blocs — reduce time-to-deploy for ground assets but raise the bar on compliance and cross-border coordination.
-
CapEx pressure and GSaaS adoption: High initial capital requirements for antennas, RF chains and control software are driving even established operators to hybridize their business models, blending owned assets with leased GSaaS capacity to preserve cash and flexibility.
-
Operational resilience and sovereignty: Governments and defense customers continue to demand sovereign control capabilities, driving a dual-market dynamic: one for open commercial GSaaS and another for controlled, sovereign operations with higher margins.
-
Co-existence frameworks: National telecom authorities are advancing coexistence rules for integrated satellite‑to‑device services, which has operational implications for spectrum planning, TT&C scheduling and interference mitigation strategies.
Strategic recommendations for 2026
We recommend that leaders adopt a portfolio approach to satellite control services in 2026, combining short-term agility with long-term optionality. Key actions include:
-
Lock-step regulatory engagement: Prioritize filings and regulatory dialogue in jurisdictions with imminent spectrum and licensing changes; treat regulatory positioning as a core competitive asset.
-
Hybrid operations playbooks: Implement blended GSaaS and owned-infrastructure strategies to optimize for mission class, cost of capital, and sovereign requirements. Use pilot contracts to validate SLA performance before committing to large CapEx.
-
Invest in software-defined control: Accelerate automation, telemetry analytics and contingency orchestration to reduce human-in-the-loop burden and shorten reaction times for anomaly resolution.
-
Partner selectively: Pursue strategic alliances with global ground‑network providers for redundancy while keeping mission‑critical command, cyber and mission assurance capabilities in trusted hands.
-
Prepare for consolidation: Build a playbook for M&A and partnership to close capability gaps in multi-orbit operations, ground network diversity, and cyber-hardened control systems.
How to use this report
The PW Consulting Satellite Control Service Market report is both a market sizing model and an operational toolkit. It is structured to support board-level investment decisions, procurement and program management teams, and policy advisors. Subscribers will receive vendor scorecards, contract language templates, scenario financials, and a prioritized roadmap of regulatory actions to monitor through 2026.
For teams preparing 2026 budgets, negotiating multi-year GSaaS contracts, or evaluating vertical integration of ground assets, the report provides the analytical foundation and tactical artifacts you need to move from debate to execution.
Next steps
Contact PW Consulting to obtain the full report and access the underlying models, granular segmentation, vendor benchmarking and executive briefings. The full publication includes the detailed regional, service-type and end-user segmentation that underpins the high-level forecasts presented here—information we intentionally reserve for report subscribers to preserve commercial sensitivity and ensure accuracy in procurement contexts.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com