

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: P Series Glycol Ether Market Poised to Expand at a 4.85% CAGR, 2025 Insight Predicts Steady Growth

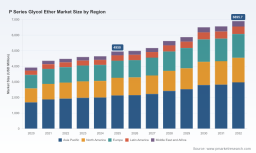
P Series Glycol Ether Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
The global market for P‑series glycol ethers reached roughly USD 4.95 billion in our 2025 base year and is projected to expand at a compound annual growth rate (CAGR) of approximately 4.85% across the 2026–2032 forecast window. That trajectory points to market scale and resilience that matter for investment planning, plant allocation, and procurement strategies in 2026. This preview summarizes the strategic insights in PW Consulting’s P Series Glycol Ether Market report, highlighting actionable implications for commercial, supply‑chain, and M&A decisions while intentionally withholding granular segment figures to encourage direct access to the full analysis.
P Series Glycol Ether Market
Why P‑series glycol ethers deserve boardroom attention in 2026
-
End‑market breadth: P‑series glycol ethers are embedded across paints & coatings, electronics, industrial and household cleaners, printing inks and adhesives. This cross‑industry exposure cushions demand volatility but also requires differentiated go‑to‑market tactics by end‑use.
P Series Glycol Ether Market -
Moderate, steady growth: The sub‑5% CAGR signals a market that is neither a hyper‑growth play nor in terminal decline — ideal for firms seeking stable, cash‑generative chemical portfolios or for financial buyers targeting defensive specialty‑chemical assets.
P Series Glycol Ether Market -
Supply sensitivity: The production chain is tightly linked to propylene oxide feedstock and a concentrated set of global producers, making short‑term supply shocks and price moves materially relevant to operating and pricing strategy.
Market dynamics and demand drivers
Demand dynamics in 2026 will be shaped by a steady recovery and structural shifts across major end markets. Paints and coatings remain the single largest demand driver by application, with performance and regulatory requirements pushing formulators toward higher‑purity solvents and specialty grades. The electronics and semiconductor segment continues to exert above‑average growth given precision cleaning and formulation needs in advanced packaging and assembly.
Concurrently, industrial and household cleaning formulations are evolving toward low‑VOC and performance‑enhanced chemistries. This means producers with technical service capabilities and formulation partnerships will be better positioned to capture premium value than purely commodity suppliers.
Upstream cost and supply signals to monitor
-
Propylene oxide remains the primary upstream feedstock. Recent price volatility — including a notable uptick in early 2026 driven by firm downstream demand and feedstock cost pressures — underscores the channel through which raw‑material shocks transmit to glycol ether margins and market pricing.
-
Regional feedstock imbalances also create tactical arbitrage opportunities. Quarterly swings have been observed, and players with flexible feedstock sourcing, hedging programs, or integrated propylene/propylene‑oxide positions will see differentiated margin performance.
-
Operational disruptions at key facilities can cascade rapidly because of market concentration. The March 2026 force majeure declared by a major producer following a Bayport facility incident is a reminder that short‑term tightness can reshape trade flows and margin profiles for months.
Regulatory and sustainability tailwinds
Regulatory developments are elevating both compliance risk and opportunity. In the U.S., proposed Significant New Use Rules (SNURs) under TSCA signal greater scrutiny of certain glycol‑ether related substances. Parallel initiatives in EMEA and APAC focus on emissions, worker safety, and end‑use labeling.
These regulatory currents are accelerating buyer preferences for documented low‑toxicity, low‑VOC, and life‑cycle‑assessed solvent alternatives. Manufacturers that proactively invest in regulatory affairs, product stewardship, and Green Chemistry initiatives will not only reduce risk but also open premium channels in regulated markets.
Competitive landscape — what the leading players are doing
The P‑series market exhibits moderate concentration: the top three producers control a meaningful share of capacity while the top five intensify that concentration. This structure produces both stability and competitive friction: stable incumbent economics on one hand, and recurring opportunities for differentiation through specialty grades, service models, and geographic footprint optimization on the other.
-
Dow Inc. — A major global producer with well‑known P‑series brands and broad production capacity. Recent 2026 pricing actions illustrate how integrated sellers can manage margin recovery during feedstock volatility.
-
LyondellBasell Industries — Significant producer with large-scale assets; the March 2026 Bayport Choate facility fire and subsequent force majeure exemplify how single‑site incidents can influence global availability.
-
BASF SE , INEOS Oxide , Eastman , Shell Chemicals , and Huntsman — These incumbents compete across commodity and specialty grades, leveraging technical service, geographic reach, and integrated petrochemical capabilities.
-
Regional and specialty players such as KH Neochem, Chang Chun Group, Sasol and Solventis play important roles in local supply, niche applications, and cost‑competitive service models, especially in Asia and Europe.
Recent market shocks with strategic implications
-
Early‑2026 price increases from a major supplier demonstrate how producers attempt to recover margin when feedstock costs firm and operational leverage exists.
-
Operational disruptions (e.g., Bayport) have already prompted buyers to re‑evaluate sourcing redundancy, inventory policies, and contractual protections such as force majeure clauses.
-
Raw‑material price swings require sharper procurement playbooks: dynamic hedging, multi‑source qualification, and strategic inventory positioning.
What PW Consulting’s report delivers — practical, decision‑grade tooling
Our full P Series Glycol Ether Market report is designed for executives who need to translate market intelligence into 90‑day and 18‑month actions. Deliverables include:
-
Market sizing and growth scenarios with demand‑sensitivity testing across the 2026–2032 forecast horizon (base year 2025).
-
Supply‑side mapping that traces capacity, utilization, and trade flows across major production hubs—paired with a risk matrix that quantifies disruption probability and likely commercial impacts.
-
Commercial playbooks: go‑to‑market archetypes for commodity, differentiated, and specialty strategies; pricing levers and contract clauses to protect margins during feedstock volatility; and account segmentation frameworks for prioritizing downstream relationships.
-
Regulatory and sustainability impact models that translate proposed rules and ESG KPIs into cost and revenue scenarios for compliant portfolio optimization.
-
Competitive due diligence dossiers on the leading producers, including capacity positioning, product portfolios, recent commercial moves, and M&A/partnership playbooks.
-
Proprietary index of raw‑material and logistics indicators that serve as early‑warning signals for procurement and operations teams.
Strategic playbook for 2026 — recommended executive actions
-
Short term (0–6 months): Reassess procurement and inventory policies to reflect current feedstock volatility. Prioritize contractual flexibility and diversify qualified suppliers for critical grades. Leverage short‑duration hedges where feasible.
-
Medium term (6–18 months): Accelerate qualification of specialty and high‑purity grades for electronics and regulated end markets. Invest in formulation partnerships and co‑development agreements to lock in downstream demand and margins.
-
Portfolio & M&A: Target bolt‑on acquisitions that add technical service capabilities, regional footprint, or niche grades. Divest commodity exposure where capital allocation is constrained and pursue vertical integration if feedstock control is strategically viable.
-
Risk & compliance: Establish regulatory surveillance to track SNUR and analogous developments globally. Build compliance roadmaps and marketing narratives around low‑toxicity credentials to maintain market access and pricing power.
-
Operational resilience: Model alternative production and logistics scenarios to prepare for site‑level outages. Invest selectively in capacity redundancy or tolling arrangements in strategically important regions.
How to use this preview
This article functions as a strategic trailer: it communicates the major forces and recommended responses that should shape 2026 decision cycles, while preserving the detailed segmentation, regional flows, and proprietary numeric assumptions for subscribers of the full PW Consulting report. If your 2026 plan hinges on new capacity investments, contract renewals, or an acquisition mandate in glycol ethers, the full report provides the granular, transaction‑grade analysis needed to proceed with confidence.
Next steps
For access to the full dataset, regional and application breakdowns, supplier scorecards, and scenario models referenced in this preview, please consult the P Series Glycol Ether Market report on PW Consulting’s website or contact your PW account representative. The full report includes the underlying assumptions, sensitivity analyses and downloadable tables required to build investment memos, procurement strategies, and board presentations for 2026.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com