

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 24-Hour Emergency Roadside Assistance Market Poised to Expand at a 5.12% CAGR Through 2032

PW Consulting: Strategic Preview — 24 Hour Emergency Roadside Assistance Market Outlook for 2026 Decision-Makers
As automotive ecosystems accelerate toward electrification, connectivity and new ownership models, the 24 Hour Emergency Roadside Assistance market is undergoing structural change that will determine competitive advantage through the remainder of the decade. PW Consulting’s latest market study — covering historical performance (2020–2025) and a seven-year forecast (2026–2032) — equips executives, investors and public-sector planners with the practical intelligence necessary to translate operational readiness into strategic value in 2026 and beyond.
24 Hour Emergency Roadside Assistance Market
Headline market context
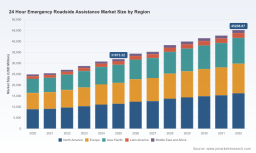
After resilient expansion through the early 2020s, the global 24-hour roadside assistance market is now a multibillion-dollar segment with sustained mid-single-digit growth. Our model shows the market expanding from roughly USD 24.9 billion in 2020 to approximately USD 31.9 billion in 2025, and continuing on to an estimated USD 45.2 billion by 2032 — a compound annual growth rate of 5.12% over the forecast horizon (2026–2032). This growth is being driven by rising vehicle parc, bundled insurance and OEM service propositions, fleet telematics adoption, and incremental service complexity tied to EVs, ADAS and vehicle software-driven immobilisations.
24 Hour Emergency Roadside Assistance Market
Why this report matters for 2026 planning
- Translating growth into margin: We show where revenue pools are expanding versus where unit costs are rising (e.g., EV handling, specialist storage and safety protocols), enabling CFOs to forecast margin sensitivity under realistic scenarios.
- Vendor selection and partnership strategy: Insurers, OEMs and fleets face a choice between scale players, white-label integrators and on-demand digital platforms. The report provides a decision framework to match partner capabilities to required SLAs, liability exposures and customer experience outcomes.
- Regulatory & operational risk management: With patchwork regulation across jurisdictions (from storage fees and EV-incident requirements to inconsistent standards for roadside service vehicles), the study flags where compliance gaps will create near-term costs or service failures.
- Technology investment prioritisation: We prioritise investments — dispatch orchestration, predictive call triage, remote diagnostics and EV-safe response tooling — by expected ROI and adoption risk through 2028.
What’s inside — operationally focused deliverables
Rather than a high-level narrative, the report is structured as a hands-on playbook for commercial leaders and operations teams. Core chapters include:
24 Hour Emergency Roadside Assistance Market
- Executive synthesis and decision-ready dashboards summarising market size, growth trajectories and scenario sensitivities for 2026 board cycles.
- Methodology and raw-market modelling (transparent assumptions, data sources, and a reproducible forecasting engine) so clients can stress-test outcomes under custom inputs.
- Service-level economics: unit costing models for towing, battery/jump starts, tire replacement, fuel delivery and lockout/minor repair, with uplift drivers for EVs and heavy-vehicle responses.
- Provider benchmarking and capability scorecards: operational KPIs, dispatch technology maturity, OEM integrations, white-label strength and financial resilience — enabling shortlist creation for RFPs and M&A screening.
- Technology map and vendor directory: comparison of telematics integrators, AI dispatch providers, mobile repair platforms and EV charging/handling specialists.
- Regulatory impact assessment: jurisdictional risk heatmaps, compliance cost estimates and recommended policy interventions for operators and policy-makers.
- Scenario planning and contingency playbooks: 12–36 month stress scenarios (sharp EV incident uptick, regional regulatory shifts, acute labour shortages) with step-by-step operational responses.
- Commercial go-to-market templates: bundled product architectures for insurers and OEMs, pricing sensitivity matrices and customer-retention levers for membership models.
- Appendices: interview transcripts with operators, anonymised call-level cost samples, and procurement templates for outsourcing roadside services.
Note: the report contains detailed segment-level tables (geography, service type, provider model) and granular forecasts intended for purchasing organisations. This press summary purposefully highlights strategic implications while reserving segmental line-items for report subscribers.
Competitive landscape — how incumbents and challengers are positioning
The market is shaped by a mix of longstanding member clubs, insurance-affiliated programs, OEM-backed white-label operators and digitally native platforms. Our competitive analysis profiles each major participant on commercial model, technology posture and scale economics:
- American Automobile Association (AAA) — A membership-centric model with deep brand equity and operational scale across North America. AAA’s strengths lie in its trusted local patrol networks and member experience, which create high retention even as service mix slowly broadens toward EV-related capabilities.
- Agero, Inc. — A dominant white-label integrator offering orchestration for insurers, OEMs and fleets. Agero’s competitive edge is advanced dispatch tech and the ability to integrate EV charging and specialty services into end-to-end claims workflows.
- Allianz Partners — Strong in OEM and insurance partnerships across Europe and beyond. Recent contract extensions with automakers demonstrate the group’s focus on harmonised, cross-market programs and premium-level features such as alternative transport and repair coordination.
- ADAC , RAC and AA (UK) — Large national clubs with substantial patrol fleets and strong member loyalty. Their operating playbooks prioritise rapid roadside repair and recovery, while selectively partnering with third parties for specialised services or new vehicle technologies.
- Digital challengers (e.g., Urgently) — These platforms compete on speed-to-scene, dynamic dispatching and seamless UX. Their capital-light networks and AI-driven triage are attractive to dealers and urban fleets, but scaling to long-distance towing and heavy-recovery remains a challenge.
- Insurer-owned programs (e.g., GEICO, Allstate, Progressive) — Roadside assistance is often an embedded add-on or motor-club product, used strategically to enhance policy stickiness and customer satisfaction. Integration with claims handling is the differentiator.
- Regional network providers (Falck, ARC Europe, Viking Assistance, SOS International) — Important partners for cross-border continuity, especially for OEMs and pan-European insurers. Their value is network coverage combined with local compliance expertise.
- Smaller independents and fleet specialists — Provide flexible surge capacity and local expertise for large fleet customers; often targets for consolidation by scale players seeking geographic density.
Recent moves and what they signal
- Allianz Partners’ expanded OEM agreements and reappointments underscore the commercial value automakers place on harmonised roadside experiences as part of owner retention strategies.
- RAC’s retailer/OEM collaborations signal continuing co-opetition in new-entrant markets: incumbent patrol networks are monetising service delivery for emerging brands.
- Cox Automotive’s fleet organisation consolidation points to integration playbooks where vehicle lifecycle services (roadside, maintenance, remarketing) are bundled to extract higher lifetime value.
- High-profile marketing and sports sponsorships by member clubs remain a low-cost retention channel that also supports brand trust — a critical asset for converting roadside interactions into longer-term customer relationships.
Regulatory and operational dynamics to watch in 2026
Operators and contracting organisations must plan for a more complex regulatory environment and changing operational risk:
- Jurisdictional fragmentation: rules governing storage and handling of damaged EVs, roadside service vehicle lighting and provider vetting vary significantly across states and countries. For example, new state-level rules affecting post-crash EV storage and separation specifications will create logistic and cost implications for regional operators.
- Oversight gaps: some jurisdictions still treat roadside assistance distinctly from licensed towing, creating uneven standards for training, equipment and liability exposure — a contracting and reputational risk for insurers and platforms relying on third-party vendors.
- Service demand composition: despite high visibility around EV range anxiety, EV-related calls remain a small share of total volumes for large member clubs today, suggesting a near-term mismatch between public perception and operational reality. However, as EV market share rises, specialised handling and storage requirements will impose non-linear cost increases if unplanned.
- Asset stressors: infrastructure issues (for example, spikes in pothole-related breakdowns observed by patrol services) create episodic demand peaks that stress capacity planning and surge pricing models.
Ten strategic implications for 2026 decision cycles
- Embed EV-safe response processes into vendor contracts and insurance claims flows now, not later.
- Invest selectively in dispatch and predictive triage tools to reduce drive time and increase first-time-fix rates.
- Make regional regulatory risk a transaction checklist item for M&A and partnership diligence.
- Design tiered service bundles that reflect differing economics of short-haul urban responses vs. long-distance recovery.
- Create cross-functional playbooks between claims, roadside operations and customer experience teams to monetise service touchpoints.
- Use pilot procurements to test AI-enabled digital dispatchers with clear KPIs before wide rollout.
- Prioritise partnerships with network providers for cross-border continuity when serving OEMs and multinational fleets.
- Stress-test pricing models against episodic demand surges caused by infrastructure failures or severe weather.
- Retain in-house capability for critical, brand-defining interventions even where outsourcing is economical for routine calls.
- Monitor public policy trends and participate in regulatory consultations to shape practicable standards for EV handling and RSV operations.
Conclusion — how PW Consulting’s report supports 2026 decisions
For executives needing to convert market growth into sustainable margin and resilience, this report provides both the horizon picture and the tactical playbooks required for 2026 board decisions. It balances reproducible forecasting with procurement-ready due diligence tools and operational playbooks that address the most pressing risks — from regulatory heterogeneity to technology adoption trade-offs. As incumbent operators, insurers, OEMs and challengers set priorities for capital allocation, hiring and partner selection this year, access to the full dataset and provider-level benchmarking included in PW Consulting’s study will be decisive.
To access the complete report — including the granular segmentation tables, provider scorecards and downloadable modelling files that underpin the conclusions summarised here — visit PW Consulting’s report page or contact our client services team for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com