

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
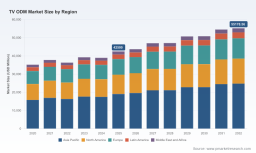
PW Consulting: TV ODM Market Reaches USD 42,500 Million in 2025, Poised for Continued Growth

TV ODM Market 2026: Strategic Imperatives for C-Suites, Procurement Heads and Product Leaders
Executive snapshot
PW Consulting’s Tv ODM Market report establishes a forward-looking framework to guide enterprise decision-making through 2026 and beyond. Anchored on a 2025 base year and a clear forecast window to 2032, the study quantifies a steady industry expansion at a compounded annual growth rate (CAGR) of 3.8% and maps the structural forces reshaping TV original design manufacturing. By combining hard market-sizing, supplier capability mapping, and scenario-driven risk analysis, this report is designed as an executable playbook for executives who must balance cost, speed-to-market and technological differentiation in a market that remains capital- and supply-chain intensive.
Tv Odm Market
Market trajectory and implications for 2026
-
The global TV ODM market reached a robust scale in 2025 (base-year) and, under our baseline assumptions, is set to expand into the mid-to-late 2030s, growing from the 2025 base toward an expected total market significantly larger by 2032. This growth—while moderate in percentage terms—translates into meaningful absolute volume and revenue shifts for OEMs, ODMs and component suppliers alike.
Tv Odm Market -
Importantly, the market’s 3.8% CAGR masks heterogeneity in technology adoption, regional manufacturing shifts and channel dynamics. For corporate strategists, that means prioritizing flexibility: the companies that can reconfigure supply commitments, diversify sources, and accelerate integration of emerging display technologies will capture disproportionate share gains.
Tv Odm Market -
Market concentration metrics indicate a market neither fully fragmented nor monopolistic—leading-tier ODMs command meaningful share but there remains room for challenger models and contract manufacturers to scale quickly when they combine factory capacity with software/platform partnerships.
Why this report matters to decision-makers in 2026
-
Capital allocation and capacity planning: Our analysis converts macro growth into actionable manufacturing demand scenarios so CFOs and operations leaders can time investment in new lines or short-term capacity leasing.
-
Procurement and supplier strategy: With panel costs and IC prices volatile in early 2026, sourcing teams need granular supplier scorecards, hedging options and contract templates to prevent margin erosion.
-
Product roadmap and commercialization: R&D and product leaders will benefit from our adoption maps showing where premium display formats and smart-TV platform partnerships deliver the greatest price/feature elasticity.
-
Regulatory and geopolitics playbook: The study contains trade-policy scenario analyses—critical as governments revisit tariffs and onshoring incentives that could re-route manufacturing economics within 12–36 months.
What the report contains — an operationally focused index
-
Robust market sizing (historical 2020–2025) and demand-driven forecasts (2026–2032), with base-case, upside and downside scenarios informed by component-price shocks and policy interventions.
-
Technology adoption pathways (LED variants, emissive displays and incremental backlight innovations), with implications for BOM composition and margin sensitivity.
-
Comprehensive supplier ecosystem maps: factory footprints, scalable capacity options, licensing and platform partnerships, and time-to-market estimates by region.
-
Cost structure decomposition and supplier negotiation playbooks that quantify panel, IC and assembly exposure—plus practical contract clauses to manage lead times and warranty risk.
-
Go-to-market and channel strategies for brands and retailers, including private-label and licensed-brand models optimized for omnichannel distribution.
-
M&A and partnership screening tools: target prioritization matrices built on industrial economics, capacity synergies and IP/firm capabilities.
-
Regulatory and trade-risk module with mitigation plans (nearshoring, dual-sourcing, bonded-warehouse strategies).
Competitive landscape — profiles and strategic moves
The TV ODM market’s competitive map blends traditional electronics contract manufacturers, panel makers that offer ODM services, and specialist TV-focused OEMs. Leading players combine scale production, platform partnerships and multi-region footprints to serve global brand customers. Key incumbents and strategic characteristics covered in the report include:
-
MOKA (TCL MOKA) — A turnkey TV ODM with a proven track record in large-volume shipments and full-service solutions tied to the broader TCL supply chain. Recent platform partnerships have expanded its addressable pipeline for licensed brands and white-label customers.
-
AMTC — A China-headquartered ODM increasingly focused on export markets, with substantial capacity expansion outside China to serve North America and other key markets.
-
HKC — A vertically integrated supplier with multi-factory scale and recent capacity additions that materially alter regional supply dynamics; its footprint supports both OEM and ODM route-to-market strategies.
-
Express Luck — A rapidly scaling player transitioning from coastal park manufacturing to larger annual ODM throughput, representing the archetype of operators ready to capitalize on shifting orders.
-
TPV Technology, BOE VT, Foxconn, Innolux, KTC, JPE and several agile regional specialists — These firms span the gamut from large EMS/ODM OEMs to display-first suppliers offering integrated display + assembly solutions. Their strategic differences—platform partnerships, licensing relationships and in-region capacity—are explored in depth.
Notable developments tracked in the report include recent turnkey platform tie-ups that accelerate time-to-market for license holders, large greenfield factory commissioning that shifts capacity balance, and active trade-show participation that signals customer acquisition campaigns for global distribution.
Supply-chain stressors and policy risk
-
Component-cost volatility: Display panels remain the largest single cost component in TV manufacturing, and early-2026 inflationary pressure on panels, integrated circuits and memory has already pushed pricing assumptions. Buyers and manufacturers must recalibrate BOM and margin models accordingly.
-
Tariff and geopolitical headwinds: Policy proposals to restrict reliance on particular supply bases are creating a re-evaluation of sourcing geographies. For many brands and providers, this is accelerating investment in alternative assembly locations and contingency inventory models.
-
Capacity versus demand timing: Several large-scale factory ramp-ups and capacity shifts are changing lead-time dynamics; firms that can lock favorable supply terms early will enjoy a procurement advantage in 2026.
Strategic recommendations for 2026 (prioritized, actionable)
-
Immediate (0–6 months): Establish a supplier stress test across panel and IC exposure; negotiate short-term price collars or volume-flex clauses; identify two alternate OEM/ODM suppliers for critical SKUs.
-
Near term (6–18 months): Reassess capacity commitments and consider hybrid models (captive lines + contract capacity) to manage demand swings; accelerate platform-level integrations with select ODM partners to reduce software/hardware integration risk.
-
Medium term (18–36 months): Evaluate capex or strategic partnership to secure prioritized component supply (e.g., local panel agreements or equity stakes in upstream suppliers); incorporate trade-policy scenarios into sourcing and price pass-through clauses.
-
Competitive positioning: For brands: prioritize differentiated UX and platform partnerships over marginal hardware feature races. For ODMs: pursue services-led differentiation (turnkey software, logistics and after-sales) to escape pure price competition.
How to use the report
This report is structured as a decision-support tool rather than a descriptive catalog. Each chapter concludes with “playbooks” that translate insight into specific next steps (procurement templates, scenario inputs for financial models, risk-mitigation checklists). Executives will find checklists tailored to capital planning, supplier negotiations and product roadmap prioritization—intended to accelerate time-to-decision without redoing foundational analysis.
Closing — the strategic value proposition
As enterprises prepare budgets, capacity plans and go-to-market programs for the 2026 planning cycle, PW Consulting’s Tv ODM Market report delivers the macro context, competitive intelligence and operating levers necessary to make high-conviction decisions. The combination of a clear CAGR-based forecast, scenario-driven risk matrices and practical implementation templates positions this study as a single reference for teams aligning procurement, manufacturing and commercial strategy.
For senior leaders who must convert market signals into executable plans—and for teams who require the underlying segmentation, factory-level capacity schedules and supplier scorecards—our full report provides the data and the templates you need. Visit the PW Consulting Tv ODM Market report page to access the complete intelligence package, including downloadable models and supplier diligence kits.
For detailed analysis of this topic, please visit the official page: Tv Odm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com