

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: High Precision Copper Foil Market Set to Reach USD 21,167.27 Million by 2032, Growing at an 8.64% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
High Precision Copper Foil Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive snapshot
The global high precision copper foil market is entering 2026 from a position of structural growth and heightened volatility. PW Consulting’s latest market model shows the industry expanding from an estimated USD 11,850.5 million in 2025 to roughly USD 12,531.9 million in 2026, with a compounded annual growth rate of 8.64% across our 2026–2032 forecast window. By 2032, the base-case projection approaches the low‑tens of billions of dollars, underlining sustained demand driven by electrification, advanced packaging, high‑frequency electronics and next‑generation battery architectures.
High Precision Copper Foil Market
Why this matters for 2026 decision-making
-
Timing matters. After a year of material-price shocks and uneven operating rates, suppliers and buyers who crystallize supply agreements and capacity strategies in the first half of 2026 will be best positioned to capture growth without losing margin to price volatility.
High Precision Copper Foil Market -
Product differentiation is a premium. Ultra‑thin, ultra‑smooth foils and battery‑grade foils for EVs and energy storage now command strategic importance for OEMs in electrification and AI hardware supply chains. Technology leadership and process control translate directly into higher realized prices and stickier customer relationships.
High Precision Copper Foil Market -
Regulatory and sustainability compliance is non‑negotiable. Policies—particularly in markets with aggressive carbon neutrality targets—are forcing production upgrades, incremental costs and, for some producers, capex reallocation toward renewable energy and recycled feedstocks.
What's inside the PW Consulting report (practical, executable deliverables)
-
Top‑down market model with multi‑scenario forecasts (base, stress, upside) that translate macro demand drivers into quarterly demand curves and capacity utilization trajectories through 2032.
-
Supplier risk-heatmaps and procurement playbooks that rank upstream concentration, single‑sourcing exposures and pass‑through risk—designed for sourcing leads to implement immediate mitigation steps.
-
CapEx prioritization framework for manufacturers: an ROI matrix that contrasts brownfield upgrades, new‑line investments and technology licensing for ultra‑thin/ultra‑smooth product classes.
-
Pricing‑and‑margin scenario tools that map copper cathode moves, TC/RC dynamics and labor inputs into product‑level margin sensitivity analyses.
-
Regulatory stress tests and decarbonization roadmaps tailored to high‑precision foil producers—actionable steps to convert policy requirements into capital and operational timelines.
-
M&A and partnership playbook highlighting value creation levers for strategic buyers, financial sponsors and specialized technology licensors.
Competitive landscape — who matters and why
The supply side of high‑precision copper foil is a blend of century‑old metallurgists, regional champions and specialized newcomers. Key strategic differentiators are process technology (surface roughness control, thickness precision), scale in ultra‑thin/ultra‑smooth segments, geographic footprint, and integration with downstream laminated materials or battery supply chains.
-
Mitsui Mining & Smelting (Mitsui Kinzoku) — Technology leadership via proprietary ultra‑smooth processes and ongoing capacity expansion has positioned Mitsui as a price‑making force in the premium product tier. Recent announcements include a material price increase for select product lines, reflecting both elevated input costs and deliberate margin management.
-
JX Nippon Mining & Metals (JX Advanced Metals) — Strong in electrodeposited and rolled precision foils, with an emphasis on signal integrity and thickness control for high‑frequency applications. Their R&D and process discipline make them a preferred partner for customers where tight tolerances are mission‑critical.
-
Furukawa Electric — Global manufacturing footprint and tight tolerance manufacturing capabilities make Furukawa a resilient supplier for high‑end electronics demand, particularly where global lead times and quality consistency matter.
-
Circuit Foil Luxembourg — Longstanding specialty producer in electrodeposited foils, maintaining a strong reputation for precision across very thin-to-thicker product ranges—an important option for European and global high‑reliability applications.
-
Solus Advanced Materials — A specialist in ultra‑low roughness foils for AI accelerators and advanced PCBs, their technical positioning underscores the premium available in emerging high‑performance electronic segments.
-
Regional manufacturers (China, Korea, Taiwan, Europe) — Several local champions and manufacturers have scale advantages for commodity and certain precision classes; their strategic plays include vertical integration toward copper clad laminates and closer alignment with battery and FPCB demand.
Recent industry developments validate these dynamics: a number of producers have announced price adjustments to cope with higher copper and labor costs, and leading manufacturers continue to expand premium‑product capacity. These moves collectively increase short‑term price stickiness while encouraging downstream customers to rethink sourcing and product design strategies.
Supply‑side and raw‑material dynamics to factor into 2026 strategy
-
Copper feedstock volatility remains the single biggest operational risk. Early‑2026 price episodes reached multi‑year highs before partial moderation; upstream treatment charge dynamics are moving independently of cathode levels, compressing margins unpredictably.
-
China’s dominant production footprint means regional operating rates, export controls and tariff moves can rapidly alter global availability and lead times. Buyers should model concentrated‑supply shock scenarios as part of any sourcing decision.
-
Environmental policy—in particular commitments to carbon neutrality in major producer countries—creates immediate capex planning implications. Compliance is creating a bifurcation: producers that invest early in decarbonized operations can command premium access to eco‑sensitive customers; laggards face escalating compliance costs or market access limits.
Six priority actions for executives in 2026
-
Implement a 90‑day procurement triage: secure rolling contracts for critical product classes, add alternate qualified sources for ultra‑thin foils, and negotiate conditional price‑pass through clauses tied to copper indices.
-
Stress‑test product roadmaps: where product design can tolerate slightly coarser roughness or different foil types, work with suppliers on re‑qualification roadmaps that reduce single‑supplier exposure.
-
Prioritize retrofit capex for energy efficiency and recycled feedstock capability—these initiatives reduce operating costs and future regulatory risk while increasing appeal to sustainability‑driven end customers.
-
Carve out a premium product strategy: if you are a supplier, double down on ultra‑thin/ultra‑smooth capabilities and customer co‑development for AI/accelerator and high‑end PCB segments—margins and customer stickiness are highest here.
-
For investors: use our supplier risk scorecards to prioritize targets with differentiated process IP, stable long‑term offtake and sustainability credentials. Pay attention to balance‑sheet resilience in a high‑capex, cyclical raw‑material environment.
-
Governments and trade advisors should engage with industry to calibrate export and tariff policies; abrupt policy shifts will materially affect global lead times and supply security for strategic industries like EVs and telecommunications.
How PW Consulting’s intelligence accelerates your 2026 playbook
Our High Precision Copper Foil Market report is structured to be operational: not only does it quantify macro demand and price sensitivity, it provides executable templates—contract language for pass‑through events, a supplier qualification checklist, a prioritized capex decision tree, and M&A valuation overlays. The report’s scenario suite converts industry noise into board‑level choices: which market exposures to hedge, which capacities to contract, where to invest in process upgrades, and where consolidation is most likely to create value.
We have deliberately maintained the granularity that executives need while withholding proprietary segmentation tables and supplier scorecards in this public brief. These detailed tables and supplier‑level assessments are available in the full report and via our online portal for clients who require immediate supplier validation, contract language, or tailored model runs for corporate planning.
Next steps
For commercial teams, procurement heads and corporate strategists preparing 2026 budgets and three‑year plans, the next 60–120 days are critical: finalize hedging and contract approaches, begin supplier qualification pilots and align capex with decarbonization timelines. PW Consulting can deliver a condensed 48‑hour diagnostic for your supply footprint, or a bespoke two‑week scenario workshop that maps your demand profile to supplier and price risk under the three forecast cases.
To access the full intelligence set—detailed segmentation, supplier scorecards, and downloadable modelling tools—visit our High Precision Copper Foil Market report page or contact PW Consulting’s industry practice to request a briefing and demonstration of the scenario toolkit.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trial Process Management System Market Poised for 13.18% CAGR from 2026–2032
By pmarketresearch, 2026-07-13
Trial Process Management System Market — Strategic Outlook for 2026 (PW Consulting)
Executive teaser
As enterprises finalize technology budgets and vendor roadmaps for 2026, the Trial Process Management System market stands at an inflection point. Our new PW Consulting report—anchored on 2025 as the base year—shows the market reaching roughly USD 2,892.6 million (revenue unit: Million USD) in 2025, with a sustained compound annual growth rate (CAGR) of 13.18% through our 2026–2032 forecast horizon. By 2032, PW Consulting projects the market to approach the multi‑billion dollar threshold that will reframe how sponsors, CROs and research sites budget for clinical operations and data orchestration.
Trial Process Management System Market
Why this research matters for 2026 decisions
-
Speed vs. compliance: Sponsors and CROs face intensifying pressure to compress timelines while meeting stricter regulatory expectations—forcing tradeoffs in platform selection, validation cadence and operational staffing.
Trial Process Management System Market -
AI and orchestration are no longer optional: Leading vendors are embedding AI companions, virtual twins and orchestration layers into CTMS suites. Assessing maturity and production readiness of these capabilities is central to 2026 procurement decisions.
Trial Process Management System Market -
Cybersecurity/regulatory tightening: Proposed updates to the HIPAA Security Rule (target final action May 2026) introduce mandatory controls—encryption, biannual vulnerability scanning and annual penetration testing—that materially affect vendor selection, contracting and total cost of ownership.
-
Consolidation dynamics: Market concentration indicates room for scale advantages—our concentration analysis shows the top three vendors account for a meaningful portion of market activity (CR3 ≈ 38.45%) and the top five increase that share (CR5 ≈ 54.12%)—but specialist and site‑centric vendors remain strategically important for niche workflows.
What the PW Consulting report delivers (practical, executable content)
-
Decision frameworks: A vendor due‑diligence matrix calibrated for enterprise sponsors, mid‑sized CROs and research sites—covering functional fit, API openness, AI readiness, validation evidence and commercial terms.
-
TCO & ROI models: Dynamic templates that translate license, implementation, hosting and ongoing labor into multi‑year scenarios; sensitivity analysis for cloud storage/ingress, integration complexity and validation labor.
-
Procurement playbook: Contract archetypes with mandatory clauses (data residency, encryption at rest/in transit, audit rights, BAA requirements) and negotiation levers for pilot‑to‑enterprise transitions.
-
Implementation & change management: A practical 90–180 day implementation checklist, validation IQ/OQ/PQ templates aligned with 21 CFR Part 11, training curricula and site on‑boarding sequences that minimize subject and site burden.
-
Risk and compliance mapping: Crosswalks that map HIPAA, GDPR (Article 25: data protection by design and by default), and FDA/EMA computerized systems expectations to specific technical and organizational controls.
-
Vendor selection scenarios: Playbooks optimized for three archetypes—enterprise consolidation, best‑of‑breed interoperability and site‑led adoption—each with sample KPIs and governance constructs.
Market dynamics: what the macro numbers imply
The macro trajectory—near‑term market growth from a 2025 base of approximately USD 2.9 billion at a 13.18% CAGR—signals robust investment appetite. Buyers should interpret this as a window to secure strategic leverage: with significant expansion ahead, early adopters of maturity‑enhancing capabilities (advanced analytics, orchestrated AI, integrated EHR/EDC workflows) will capture disproportionate operational ROI, while laggards face escalating migration and integration costs. The documented concentration (CR3/CR5) reflects dominant platform footprints but also underscores an expanding middle market where specialist vendors compete on functionality, lower total cost and site friendliness.
Competitive landscape — how to read vendor signals
-
Veeva Systems — Enterprise‑grade CTMS with a growing push toward site enablement (recent SiteVault CTMS and eISF/eConsent integrations). Useful for sponsors prioritizing end‑to‑end Vault ecosystems and tight sponsor‑site data flows.
-
Medidata (Dassault Systèmes) — Emphasizing AI orchestration and virtual twins; strategic partnerships and AI companions position the platform for protocol optimization and real‑time study execution acceleration.
-
Oracle — Siebel/Clinical One heritage with deep EHR/EDC integration credentials; recognized by industry assessments for lifecycle integration and enterprise governance.
-
Advarra — Site and academic center focus with strong capabilities in financial management, billing and regulatory workflow automation—a go‑to where institutional billing and compliance complexity dominate.
-
Parexel, IQVIA — CRO‑anchored CTMS offerings that bundle operational services and informatics; attractive for sponsors seeking integrated service + tech propositions.
-
Clario, RealTime, ArisGlobal, MasterControl — Specialists offering differentiated strengths (endpoint integration, site workflow efficiency, pharmacovigilance integration, quality‑centric CTMS) and are frequently the tactical choice for niche trials or regulated device programs.
Recent vendor moves in 2025–2026 illustrate strategic priorities: Medidata’s AI ecosystem and partnership announcements (early 2026) underscore investment in orchestration; Veeva’s site‑centric SiteVault launch signals a push to lower site friction; Advarra’s product enhancements highlight the competitive focus on analytics and automation for sites; and Oracle’s recognition reaffirms enterprise integration leadership. Buyers should evaluate these moves not as isolated PR events but as directional indicators of where product roadmaps and partner ecosystems will mature through 2026.
Regulatory and operational headwinds that must be budgeted
-
Regulatory controls: Anticipate mandatory technical controls linked to HIPAA Security Rule updates (encryption, scheduled vulnerability scanning, annual penetration testing) and contractually defined BAAs under the HIPAA Privacy Rule. GDPR Article 25 will continue to require demonstrable data protection‑by‑design in clinical systems.
-
Validation obligations: FDA 21 CFR Part 11 and EMA expectations require rigorous validation artifacts—automation does not eliminate documentation; it changes the shape of validation and continuous compliance evidence.
-
Labor and hosting costs: The primary operational cost drivers remain specialist labor for configuration, validation and compliance monitoring, plus cloud hosting fees driven by data volume and integration breadth.
Investment priorities for 2026 — recommended focus areas
-
Prioritize modular, API‑first platforms that reduce integration risk and provide graceful migration paths.
-
Require explicit AI governance and reliability SLAs for any vendor marketing ML/AI features; demand production case studies and failure‑mode assessments.
-
Budget for compliance operationalization: penetration testing, formal vulnerability scanning cadence, and a validation sustainment team—these are non‑optional line items in 2026.
-
Negotiate BAAs, data residency and exit provisions up front; include obligations for de‑identification/pseudonymization and data export mechanisms to avoid later disputes.
-
Invest in site enablement: low/no‑cost site offerings (where available) and training can materially reduce time‑to‑enrollment and site turnover.
Six‑month strategic checklist for procurement & implementation leads
-
Assemble a cross‑functional steering committee (clinical operations, IT/security, regulatory, finance, and site representation).
-
Run a TCO sensitivity analysis across best‑and‑worst‑case scenarios for integration complexity, validation labor and cloud costs.
-
Execute vendor pilots that include security testing, API interoperability proof‑points and an AI feature acceptance test where applicable.
-
Include contractual safeguards: clear SLAs, compliance attestations, audit rights, BAA language, and defined exit/transition services.
-
Define KPIs tied to operational outcomes (subject enrollment velocity, monitoring efficiency, site query resolution time) and instrument progress into vendor compensation where appropriate.
Why PW Consulting’s Trial Process Management System report is essential now
For 2026 strategy, tactical vendor selection is inseparable from long‑term operational design. Our report blends macro forecasting (market sizing and trajectory through 2032), concentration analysis and proprietary procurement frameworks with hands‑on tools—TCO templates, contract archetypes, validation checklists and implementation playbooks—that are immediately actionable. To preserve the strategic value of the full dataset, PW Consulting intentionally presents high‑level insights here while withholding granular subsegment tables and region/application splits. Those detailed breakdowns, vendor scorecards and downloadable templates are available in the full report and accompanying data annex.
If your 2026 roadmap includes a CTMS refresh, cloud migration, AI pilot or an enterprise consolidation program, this PW Consulting research will shorten your decision cycle and reduce downstream cost and compliance surprises. Access the full report to view the proprietary segmentation, vendor scorecards, downloadable procurement models and the complete dataset that support the strategic recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Purity Methyl Acetate Market to Reach USD 309.62 Million by 2032, Backed by a 5.48% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
PW Consulting: High Purity Methyl Acetate Market — Strategic Imperatives for 2026
PW Consulting today publishes a strategic briefing accompanying our forthcoming full-market study on the High Purity Methyl Acetate market. The briefing distills the implications senior executives must internalize in 2026: the market recorded USD 213.12 Million in 2025 and — under our central case — is expected to expand at a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window, approaching roughly USD 310 million by 2032. These headline numbers mask structural shifts in feedstock economics, purity-driven value capture, and supplier concentration that will determine winners and losers over the next planning horizon.
High Purity Methyl Acetate Market
Why this briefing matters for 2026 decision-makers
- Translate macro growth into operational choices: Is your 2026 capex roadmap aligned to where value is concentrated (purity, specialty applications, or geographic advantage)?
- Protect margins against feedstock volatility: With methanol and acetic acid representing the majority of production cost, procurement and hedging strategies will materially influence competitiveness.
- Decide where to compete — and where to partner: High-purity grades command significant price premiums and require different production and quality infrastructure than commodity acetate.
- Use regulatory and sustainability positioning as a market lever: VOC-exempt status and biodegradability can be converted into commercial advantage in coatings, adhesives, and cleaning formulations.
Market dynamics and drivers
Three dynamics dominate the high-purity methyl acetate landscape in 2026: feedstock cost sensitivity, purity-driven pricing, and concentration among established suppliers. Production of high-purity grades is materially more capital- and energy-intensive than standard acetate because of advanced purification steps; this increases sensitivity to feedstock swings. Methanol and acetic acid together account for roughly 60–70% of production costs for methyl acetate, so changes in those markets transmit quickly to plant margins and short-term pricing.
High Purity Methyl Acetate Market
Recent market signals in China illustrate the risk profile: operating rate adjustments and methanol feedstock pressure produced upward movement in acetic acid spot values early in 2026, with further material increases observed through Q1. Those movements have immediate implications for contract pricing negotiations and working-capital planning for producers and buyers alike.
High Purity Methyl Acetate Market
On the demand side, high-purity methyl acetate benefits from multiple structural tailwinds. Its VOC-exempt status under relevant U.S. regulations supports substitution into environmentally focused coatings, adhesives, and cleaning formulations. More importantly for margin capture, true high-purity and ultra-high-purity grades — required by pharmaceutical intermediates, electronics cleaning, and premium coating systems — command meaningful price differentials versus commodity grades, driven by stricter quality specifications and the cost of advanced purification technologies.
Competitive landscape — where strategic advantage resides
The market exhibits moderate concentration: the top three players capture a meaningful share of market revenue and the top five increase that share substantially, which creates both barriers and opportunities for new entrants and regional challengers. Competitive advantage today is built on six capabilities:
- Purification and quality assurance — capacity to deliver electronic- and pharma-grade product.
- Feedstock integration and procurement scale — lowering exposure to spot swings through vertical integration or long-term feedstock contracts.
- Regulatory and certification footprint — ISO/REACH, pharma GMP-equivalent controls, and lab-validated analytics.
- Customer channel depth in coatings, adhesives, electronics, and pharma intermediates.
- Geographic production flexibility — ability to shift volumes or source nearer to demand hubs quickly.
- Cost and environmental profile — energy efficiency, emissions intensity, and biodegradability claims that influence buyer preferences.
Leading firms exemplify distinct strategic positions:
- Eastman Chemical Company: Positions its high-purity methyl acetate as a fast-evaporating, low-odor solvent tailored for coatings, 2-K polyurethane systems, adhesives, and pharmaceutical intermediates. The combination of VOC-exempt status and biodegradability provides Eastman a commercialization angle for environmentally oriented formulators.
- Celanese Corporation: Competes on purity leadership and broad industrial application set — from pharmaceutical intermediates to specialty coatings and foam blowing agents. Celanese’s emphasis on the highest purity available in the market targets customers where specification-driven pricing is less elastic.
- BASF SE and Wacker Chemie AG: Both leverage deep specialty-chemical portfolios and global customer footprints to supply high-purity grades to coatings and adhesive value chains; their differentiation leans on integrated solutions and formulation know-how.
- Merck KGaA (MilliporeSigma) and Thermo Fisher Scientific: These firms focus on ultra-high-purity, analytical, and life-science–grade methyl acetate for R&D and pharmaceutical manufacturing, where trace-level quality is a purchase determinant and switching costs are high.
- Anhui Ruibai New Materials (Ruibai Group): Represents a strategic counterweight from China — a large-scale, vertically integrated acetate producer with patented synthesis routes and capacity advantages. Its scale and integration can enable competitive pricing and fast response to regional demand swings, while certification credentials (ISO, REACH) address export and regulated-market requirements.
What PW Consulting’s full report delivers — practical, decision-ready content
The complete PW Consulting High Purity Methyl Acetate report is structured to convert insight into action. Key deliverables include:
- Validated market sizing and seven-year forecast (2026–2032), with sensitivity scenarios and upside/downside tails tied to raw material prices and regulatory shifts.
- Feedstock cost model and scenario stress-tests showing margin impact across price paths for methanol and acetic acid.
- Supplier scorecards and a risk matrix that evaluate production footprint, purity capabilities, certification status, and counterparty risk.
- Purity-grade pricing framework that quantifies typical premium bands and break-even points for investments in additional purification.
- Go-to-market playbooks for producers and downstream formulators — including product positioning templates, tiered sample qualification strategies for electronics/pharma customers, and contracting guidelines to lock-in supply at scale.
- M&A and JV screening toolset highlighting targets by capability gap (e.g., purification technology, geographic access, certified pharma supply).
- 24-month tactical roadmap for procurement, R&D, and commercial teams — prioritized actions to preserve margin and capture share amid volatility.
Note: This briefing follows the “trailer” principle — we intentionally withhold the granular regional and application-level splits and the full tabulated supplier scorecards to preserve the value of the full dataset. The report available on our site contains these detailed matrices and downloadable models.
How to use the report in 2026 corporate planning
- C-Suite / Strategy: Use the forecast scenarios and concentration analysis to set portfolio bets — whether to double down on high-purity, pursue vertical integration, or pursue licensing/partner models.
- Procurement: Implement the feedstock cost model to design hedging and long-term sourcing strategies; prioritize contracts that reduce short-term exposure to methanol and acetic acid spot volatility.
- R&D and Product Management: Calibrate formulation roadmaps to exploit VOC-exempt positioning and purity-led premium segments; prioritize investments in purification technology where return-on-capital is clearest.
- Operations and Capex Planning: Use supplier scorecards to evaluate whether brownfield upgrades versus greenfield capacity best meet demand timing and specification needs; run break-even analyses for additional purification stages against the premium for high-purity output.
- Commercial and Sales: Adopt the report’s qualification playbooks when approaching electronics and pharma customers — reduce qualification timelines and capture sticky, higher-margin contracts.
- M&A and Corporate Development: Screen targets against capability gaps identified in the report and use the report’s valuations framework to size strategic acquisitions or JVs.
Conclusion — immediate implications for 2026
2026 will be a year of active tactical choices rather than passive market-following. A market growing in the mid-single digits annually creates opportunity, but capture requires disciplined attention to feedstock risk, purity-driven product strategy, and supplier positioning. Firms that combine purification capability, procurement sophistication, regulatory-compliant manufacturing, and targeted commercial playbooks will convert forecast growth into above-market returns.
Call to action
PW Consulting’s full High Purity Methyl Acetate Market report contains the datasets, supplier scorecards, and executable templates described above. Corporates preparing 2026 budgets, procurement negotiations, or M&A pipelines should consult the full report for the granular regional and application-level intelligence that we intentionally redact here. Visit PW Consulting’s report page to request the complete dataset and tailored advisory support.
For detailed analysis of this topic, please visit the official page: High Purity Methyl Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insights: Paper Laminates Market Poised for 5.48% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
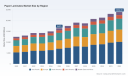
Paper Laminates Market 2026: Strategic Signals and Action Roadmap — PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise yet incisive preview of our full Paper Laminates Market research report. The industry is entering a decisive phase: after expanding from roughly USD 12,510 million in 2020 to USD 16,475 million in 2025, global demand is forecast to continue growing at a compounded annual growth rate (CAGR) of 5.48% through our 2026–2032 forecast horizon. By 2032 the market is projected to approach the mid‑twenty billion USD mark. These macro dynamics, combined with accelerating regulatory pressure and raw material volatility, mean that 2026 will be a pivotal year for strategic moves — and the full report provides the operational intelligence executives need to act with conviction.
Paper Laminates Market
Why this preview matters to executives planning for 2026
- It synthesizes the most consequential market signals: steady overall growth, fragmented supplier structure, and intensifying regulatory mandates that shift the economics of lamination choices.
- It highlights actionable frameworks — not just descriptive statistics — that procurement, product, and M&A leaders can apply immediately to scenario planning, supply‑chain hedging, and portfolio rebalancing.
- It follows a “teaser” approach: we show you the analytical depth and the decision-grade outputs while withholding the proprietary segmentation matrices and granular figures that you’ll find in the full report.
Market trajectory and structure — what the headlines reveal
The paper laminates market has moved from recovery into a structural upswing. After a mid‑cycle plateau in 2023, the sector regained momentum in 2024–2025 driven by renewed demand in packaging and construction applications and an uptick in sustainable-lamination adoption. The 5.48% CAGR we forecast for 2026–2032 incorporates both near-term cyclical effects and medium-term structural shifts toward recyclable and bio‑based laminates.
Paper Laminates Market
One important competitive signal: the market remains moderately fragmented. The combined share of the top three and top five providers indicates that no single player dominates — creating opportunity for targeted consolidation, technology differentiation and scale plays in logistics or specialty barrier solutions.
Paper Laminates Market
What the full report contains — practical, executable deliverables
PW Consulting’s full report is designed as a toolkit for practitioners. Key deliverables include:
- Strategic growth playbooks by demand cluster — frameworks to prioritize segments based on margin resilience, regulatory exposure, and supplier leverage.
- Supply‑chain risk matrix and sourcing heatmap — supplier concentration, raw material exposure, and lead‑time scenarios to support procurement hedging and near‑shoring choices.
- Regulatory impact scoring model — scoring and scenario stress‑tests for major markets that translate upcoming mandates into P&L and product‑design implications.
- Cost sensitivity and pass‑through modeling — multi‑factor simulations incorporating pulp and polymer feedstock price shocks, logistics disruptions, and potential carbon pricing.
- M&A and partnership heatmaps — tactical targets and capability gaps by technology (e.g., extrusion lamination, barrier coatings, aseptic systems) with suggested deal rationale and integration risks.
- Go‑to‑market playbooks — channel strategies for converters, laminators, and end‑users with differentiated pricing, certification roadmaps and circularity communications.
Regulatory and input‑cost dynamics shaping 2026 choices
Two regulatory vectors and two input‑cost realities will disproportionately influence vendor and buyer strategies in 2026:
- Regulatory pressure toward recycled content and circularity. The European Packaging and Packaging Waste Regulation’s recycled‑content mandates, California’s Extended Producer Responsibility (EPR) requirements already in effect, and single‑use plastic restrictions collectively raise the stakes for meeting minimum recycled content thresholds and for delivering demonstrably recyclable laminate constructions. These requirements translate into reformulation costs, chain‑of‑custody considerations, and labeling complexity — all of which are modeled in our regulatory impact scoring tool.
- EPR and compliance costs are forcing brand owners to re‑evaluate paper versus plastic lamination trade‑offs. Legal and reputational risks favor paper‑dominant or recyclable hybrid constructions, but the cost delta and functional barriers (e.g., moisture and oxygen barrier performance) require careful technical and commercial trade‑offs.
- Raw material price volatility. Recent price markers we track — such as bleached hardwood kraft pulp averaging near USD 820/metric ton (Q4 2025) and LDPE resin prices observed around USD 1,250/metric ton in Asia‑Pacific markets (Q1 2026) — create immediate margin pressure for extrusion‑laminated constructions and for any solution that relies on polymer films. These dynamics are embedded in our cost‑sensitivity models and supplier negotiation playbooks.
- Availability and certification of recycled feedstock. Access to certified recycled fibers and mass‑balanced production streams is an increasingly scarce advantage that some early movers have secured to meet incoming mandates; our supplier capability benchmarking highlights which partners have credible scale and certification readiness.
Competitive landscape — who’s moving and what their plays mean for 2026 strategy
The report provides a non‑exhaustive competitive analysis of leading paper and packaging players who are materially shaping market direction. Below are high‑level profiles and strategic observations.
- Mondi Group (Vienna, Austria — https://www.mondigroup.com) : Mondi’s innovation cadence around recyclable flexible packaging (for example, its 2025 PEEL & SEAL paper‑based laminate launch) positions it to capture demand from brands seeking mono‑material solutions. Their R&D and production scale make them a natural partner for co‑development — particularly for premium food applications where seal integrity matters.
- WestRock Company (Atlanta, USA — https://www.westrock.com) : WestRock’s extrusion coating capabilities and recent exhibition of fiber-based, high‑barrier laminates at trade shows signal an emphasis on defending folding carton and flexible packaging share by improving barrier performance while retaining recyclability claims.
- Smurfit Kappa Group (Dublin, Ireland — https://www.smurfitkappa.com) : Progress on certification (e.g., ISCC PLUS for recycled content) reinforces Smurfit Kappa’s value proposition for customers under recycled‑content mandates. Expect them to push integrated carton‑plus‑laminate solutions for retail and liquid packaging.
- International Paper Company (Memphis, USA — https://www.internationalpaper.com) : With capabilities in corrugated and specialty laminates, International Paper is positioned to monetize demand in logistics‑sensitive packaging chains where lamination enhances durability and stackability.
- DS Smith plc (London, UK — https://www.dssmith.com) : Their sustainability‑first positioning and extrusion‑laminated offerings target e‑commerce and food sectors, where single‑use plastic restrictions and consumer scrutiny are greatest.
- Tetra Laval / Tetra Pak (Pully, Switzerland — https://www.tetrapak.com) : As a specialist in multi‑layer aseptic cartons, Tetra Pak’s technical moat in PE and aluminum foil laminates for liquid packaging keeps it central to any discussion on high‑performance paper laminates for beverages.
- Stora Enso Oyj (Helsinki, Finland — https://www.storaenso.com) : Stora Enso’s mass‑balanced production and investments in renewable barrier coatings underscore a longer‑term transition to polymer‑alternative laminates — a key consideration for brands targeting plastic reduction commitments.
Recent corporate moves — product launches, certification achievements and capacity additions during 2025 and early 2026 — are not random. They reflect a common strategic response: secure feedstock and certification, raise technical performance of paper‑based laminates, and use marketing claims to capture brands shifting away from traditional plastic laminates. Our competitive heatmap ranks these initiatives by strategic significance and replicability, helping executives prioritize partnerships or defensive investments.
Actionable priorities for 2026
Based on our synthesis, organizations should prioritize the following in 2026:
- Conduct a rapid regulatory gap analysis and reprice SKUs that will bear EPR costs or require reformulation; treat compliance as a product development imperative rather than a back‑office cost.
- Secure access to certified recycled fiber and mass‑balance production capacity to avoid late‑stage reformulation bottlenecks; consider strategic contracts, minority equity plays, or supply agreements tied to certification milestones.
- Invest selectively in barrier innovation (coatings, AL foil hybridization, or advanced extrusion) to maintain functional parity with polymer laminates where needed; offset the investment with premium positioning or cost engineering elsewhere.
- Use CR3/CR5 fragmentation to pursue bolt‑on M&A in regions or technologies where scale will yield logistics or procurement advantage, but validate synergies via our M&A playbook before committing capital.
- Embed raw‑material price stress tests into pricing algorithms; implement dynamic clauses or indexation in supplier and customer contracts where feasible.
How PW Consulting’s report converts insight into decisions
This report is structured to move users from insight to execution within 90 days. Deliverables include a prioritized action list customized to buyer or supplier archetypes, an editable financial model with raw‑material scenarios, and a supplier‑selection tool that combines capacity, certification and proximity. Importantly, we provide an M&A decision framework with valuation sensitivities and integration checklists specific to paper‑laminate assets.
Next step — where to get the full intelligence
This preview maps the strategic landscape and highlights the specific actions that will determine winners and laggards in 2026. For the full dataset, proprietary segmentation matrices, interactive models and supplier rankings, access to the complete PW Consulting Paper Laminates Market report is required. The full report contains the granular regional, application and type splits, as well as the scenario outputs that are critical for formal board or investment committee approval.
Contact PW Consulting to obtain the comprehensive report and associated implementation toolkit. Our team stands ready to convert this market intelligence into a tailored 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Paper Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rosin Modified Phenolic Resin Market Hits USD 1,936.8 Million in 2025, Eyes Further Gains in 2026–2032 Forecast
By pmarketresearch, 2026-07-13
Rosin Modified Phenolic Resin Market: 2026 Strategic Preview — Actionable Intelligence for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present a strategic preview of our latest market research on Rosin Modified Phenolic Resin (RMPR). This briefing synthesizes the high‑level market trajectory, competitive posture, supply‑chain dynamics and the actionable playbook senior executives need to shape resilient, opportunity‑oriented decisions through 2026 and beyond. The full report contains the granular datasets, regional and application splits, supplier scorecards and modelled scenarios referenced here.
Rosin Modified Phenolic Resin Market
Executive snapshot
- The RMPR sector has demonstrated steady recovery and expansion following COVID‑era disruptions, with global market size rising from USD 1,582.4 million in 2020 to USD 1,936.8 million in 2025.
- PW Consulting forecasts continued growth through our 2026–2032 horizon at a compound annual growth rate (CAGR) of 4.18%, with the market projected to exceed USD 2.5 billion by the end of the forecast window.
- Market structure is moderately concentrated: the top three firms control a meaningful share and the top five firms account for just over half of industry revenues, underscoring oligopolistic tendencies in high‑value feedstocks and grade specialization.
Why this matters for 2026 corporate strategy
RMPR sits at the intersection of traditional industrial chemistry and evolving downstream needs across printing inks, adhesives, coatings and specialized road‑marking systems. For 2026 planning cycles, executives must treat RMPR strategy not as a product‑line decision but as a cross‑functional portfolio consideration: procurement, R&D, regulatory compliance, pricing and M&A are all materially affected by the resin’s market dynamics.
Rosin Modified Phenolic Resin Market
- Procurement & margin protection: Volatility in gum rosin and phenolic feedstocks has direct pass‑through effects on manufacturing costs. Firms that lock diversified supply sources or hedge feedstock exposure will preserve margin flexibility.
- Regulatory & product risk: Increasing VOC and environmental controls are reshaping acceptable formulations. Companies must invest in low‑VOC, compliant grades or secure niche exemptions through certification and value demonstration.
- Commercial positioning: With a modest degree of concentration among incumbents, focused differentiation on grade performance (high melt point, adhesion, thermal stability) and service (custom blending, logistical reliability) creates defensible pockets of value.
Market dynamics & outlook (strategic highlights)
- Historical momentum: The market expanded from USD 1.58 billion in 2020 to nearly USD 1.94 billion in 2025, driven by recovering print volumes, adhesive demand in packaging and targeted industrial coatings requirements.
- Near‑term trajectory: Our base scenario projects the market crossing the USD 2.1 billion mark in 2026 and continuing to climb to roughly USD 2.58 billion by 2032 under a 4.18% CAGR—reflecting steady demand growth tempered by raw‑material headwinds and regulatory constraints.
- Supply‑side signals: Price announcements and feedstock shifts in early 2026—such as phenolic resin price adjustments—underscore persistent sensitivity to upstream commodity cycles. Concurrent operational compliance moves among manufacturers indicate a sector adapting to elevated safety and environmental scrutiny.
Competitive landscape — profiles and strategic posture
The RMPR competitive set blends regional specialists and internationally oriented manufacturers. Key players profiled in our research include:
Rosin Modified Phenolic Resin Market
- Tridev Resins (India) — Manufacturer and exporter focused on high‑quality RMPR for printing inks; strength in export channels and ink industry relationships. ( https://www.tridevresins.com)
- Atul Polychem (India) — High‑performance synthetic resin developer with capabilities aimed at demanding industrial applications; notable R&D depth and formulation expertise. ( https://atulpolychem.com)
- Foreverest Resources Ltd. (China) — Produces RMPR through condensation polymerization; emphasizes high‑polymer binders and technical product documentation that supports downstream formulation. ( https://foreverest.net)
- DRC Resins (India) — Known for grades optimized for offset printing (e.g., Dropol™ series), focusing on adhesion and print performance. ( https://drcresins.com)
- Bluebell Polymers Pvt. Ltd. (India) — ISO 9001 certified resins manufacturer serving paint, ink and adhesive sectors; operational quality credentials are a market differentiator.
- Sanvy Resins (India) — Supplier of high‑melting RMPR grades with emphasis on thermal stability and durability for coatings and specialty applications. ( https://www.sanvyresins.com)
- Resin Chemicals (China) — Offers planographic offset printing grades emphasizing hardness, fast drying and gloss—targeting the commercial print sector.
- Guangdong Komo / Komo Tac (China) — Produces high molecular weight RMPR and rosin derivatives; active in operational compliance and safety initiatives. ( https://komotac.com)
- Baolin Chemical (China) — Large‑scale specialist across RMPR and phenolic chemistries, positioned for volume supply and integrated resin portfolios. ( https://www.baolin-resin.com)
- Shuanghe Chemical (China) — Focus on acid resistance and heat‑resistant phenolic products for industrial applications.
Recent sector events—such as targeted price increases announced by major phenolic resin producers and public safety/certification activities by regional manufacturers—signal an industry balancing cost recovery, compliance and reputational risk management.
Strategic implications and recommended actions for 2026
Executives must translate market signals into a prioritized set of initiatives. Below are high‑impact actions grounded in the research:
- Supply diversification and strategic sourcing: Build multi‑sourced procurement strategies across gum rosin suppliers and consider long‑term contracts with staggered volumes to smooth price exposure. Evaluate upstream investments or JV options where feedstock access is critical.
- Portfolio rationalization with premiumization play: Segment your RMPR offerings into basic, performance and regulatory‑compliant tiers. Focus R&D on low‑VOC and high‑melting grades that command premium pricing in coatings and specialty prints.
- Regulatory compliance as go‑to‑market leverage: Invest in certifications, lifecycle documentation and VOC analytics. Early movers in compliant formulations will gain preferential access to regulated tenders and large institutional customers.
- Commercial and channel strategy: Strengthen technical service capabilities—formulation labs, on‑site support and customized blending—to convert ink and adhesive processors from transactional suppliers into strategic partners.
- M&A and partnership playbook: Target bolt‑on acquisitions to secure geographic penetration or technical capabilities rather than broad scale plays. Our screening matrix identifies acquisition targets with the strongest synergies in grade portfolio, distribution reach and production footprint.
- Cost and operations program: Benchmark CAPEX/OPEX across producers; implement modest capex in process efficiency and emissions control to reduce unit costs while meeting environmental targets.
- Scenario planning and stress testing: Create scenario plans (commodity shock, accelerated regulation, rapid demand shift) using the market model in this report to quantify upside/downside to earnings and inventory risk.
What the full PW Consulting report delivers (practical contents)
We designed the full study to be operationally actionable for investment committees, procurement leads, R&D heads and corporate development teams. Key deliverables include:
- Comprehensive market model (2020–2032) with demand drivers, pricing curves and three forward scenarios.
- Supplier scorecards and benchmarked manufacturing footprints—technical grade mapping, capacity timelines and reliability indices.
- Go‑to‑market playbooks for upstream (feedstock) and downstream (formulator) players including sample commercial term templates.
- Regulatory compliance checklist and low‑VOC formulation pathways with estimated time‑to‑market roadmaps.
- M&A screening matrix, target shortlists and deal impact modelling for accretion/dilution under multiple integration timelines.
- Working capital and inventory stress tests tied to commodity volatility scenarios and seasonality adjustments.
Final word — positioning for advantage in 2026
RMPR is a mature but dynamic segment: growth is steady, not meteoric, and value will accrue to firms that combine technical excellence with commercial agility. In 2026, the decisive factors will be feedstock resilience, regulatory preparedness and the ability to deliver differentiated grades to core end‑markets. PW Consulting’s full report provides the models, scorecards and playbooks to convert uncertainty into defensible strategy. For executives preparing 2026 budgets, capital plans and M&A pipelines, this research is intended as the single reference source for informed decision‑making.
To access the complete dataset, regional and application splits, granular supplier benchmarking and proprietary scenario outputs, please consult the full Rosin Modified Phenolic Resin Market report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Rosin Modified Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: cfDNA Testing Market Hits USD 7,550 Million in 2025, Poised for 13.6% CAGR Through 2032
By pmarketresearch, 2026-07-13
PW Consulting: Strategic Outlook — cfDNA Testing Market to Accelerate Through 2026 and Beyond with a 13.6% CAGR
PW Consulting today publishes an executive briefing from our forthcoming CfDNA Testing Market report (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032), offering senior leaders a decision-ready synthesis of trends that will shape capital allocation, product strategy, and partnership choices across diagnostics, life sciences, and healthcare delivery in 2026. Our high‑granularity market model projects sustained, double‑digit expansion (13.6% CAGR) through 2032 — reflecting a maturing clinical evidence base, expanded commercial reimbursement pockets, and rapid technology platform improvements — and positions cfDNA testing as a core growth domain for diagnostics and precision medicine portfolios.
Cfdna Testing Market
Why this matters for 2026 decision cycles
-
Investment timing: The market is at an inflection where platform investments (sequencing, automation, AI analytics) and commercial scale deliver differentiated unit economics. Companies deciding on CapEx, strategic partnerships, or early M&A in 2026 must reconcile technical scale with payer access and lab network reach.
Cfdna Testing Market -
Reimbursement and policy windows: Recent updates in payer guidance and Medicare coverage for select diagnostic uses create a narrow window for commercial rollout and clinical validation that materially affects near‑term revenue realization.
Cfdna Testing Market -
Clinical adoption levers: Consolidation of clinical guidelines and accruing prospective data are accelerating adoption in transplant monitoring, oncology (MRD/liquid biopsy), and prenatal screening — each requiring distinct evidence and commercialization playbooks.
High‑level market trajectory (what our model shows)
-
From a baseline established through 2025, our model indicates pronounced growth over 2026–2032. The market expands meaningfully year‑over‑year as sequencing economies improve and new clinical protocols diffuse into standard care pathways.
-
The market concentration is moderate-to-high: the top three players account for roughly 42.5% of market activity while the top five cluster at about 58.3% — a structure that favors scale players with integrated offerings (test menu + lab network + payer contracts), while leaving meaningful runway for specialist entrants and disruptive platform providers.
Primary growth dynamics and drivers
-
Technology scaling and cost per test decline: Improvements in NGS workflows, library prep kits, and automation suppliers are lowering unit costs and enabling broader use cases beyond traditional prenatal screening.
-
Cross‑modal analytics: Emerging multi‑modal AI models that combine longitudinal ctDNA signals, imaging, and clinical metadata are improving MRD stratification and therapy selection — a key differentiator for oncology offerings.
-
Payer landscape and guideline consolidation: Targeted Medicare coverage for select dd‑cfDNA transplant tests and updated prenatal screening guidance from major administrators are creating definable commercial pathways, but coverage remains use‑case specific and demands robust health economics evidence.
-
Operational complexity and labor: High‑quality cfDNA testing requires specialized lab labor and CLIA/CAP compliance. Labor cost and access to certified lab capacity remain gating factors for rapid geographic expansion.
Competitive landscape — strategic read on leading players
Our competitive benchmarking synthesizes positioning across technology, clinical depth, commercial reach, and strategic intent. In the current environment:
-
Natera, Inc. (Austin): Strength lies in a diversified test portfolio that spans prenatal, oncology (MRD), and transplant monitoring, combined with active investments in AI for longitudinal cfDNA analytics. Recent product launches and MRD modeling breakthroughs underscore a platform expansion approach.
-
Guardant Health (Palo Alto): Continues to lead in oncology‑focused liquid biopsy profiling and has emphasized screening and therapy selection use cases, leveraging commercial alliances with oncology stakeholders and pharma.
-
Illumina (San Diego): Acts as an enabling platform player; its sequencing systems and assay solutions remain critical to clinical labs scaling cfDNA workflows and to new entrants seeking clinical throughput.
-
CareDx (Brisbane): A specialist in transplant dd‑cfDNA monitoring with a clinical and reimbursement foothold; publicized coverage decisions for AlloSure demonstrate the value of targeted clinical utility evidence.
-
BillionToOne (Menlo Park): Rapidly expanding both prenatal and oncology fronts with targeted assay launches and product expansions that aim to capture niche, high‑value use cases.
-
Roche, Labcorp, Quest, Thermo Fisher, Myriad and other incumbents: These organizations play mixed roles — from reagent and instrumentation supply to test provision and lab services — and will influence standards, throughput economics, and channel dynamics.
Recent market movements that matter for 2026
-
Product launches and platform extensions by leading pure‑play cfDNA companies have continued into early 2026, indicating sustained R&D velocity and market expansion intent.
-
Clinical validation updates for transplant dd‑cfDNA assays are reducing uncertainty and supporting payer coverage conversations.
-
Regulatory and payer signals (guideline updates and selective Medicare coverage) are crystallizing reimbursement paths but also raising the bar for evidence generation and real‑world outcomes measurement.
What the PW Consulting report delivers (practical, transaction‑grade content)
-
Proprietary market model (2020–2032) with scenario analyses and sensitivities tailored to technology cost curves, reimbursement uptake, and adoption velocity.
-
Commercial playbooks for three principal use cases (prenatal screening, oncology MRD/liquid biopsy, transplant monitoring), including pricing levers, channel strategies, and recommended clinical partnerships.
-
Competitive scorecards and vendor capability matrices that map tech stack, regulatory posture, clinical evidence, and go‑to‑market reach.
-
Payer landscape and health economics templates for dossier preparation, coverage engagement strategies, and modeling of reimbursement scenarios.
-
Regulatory pathway mapping for major jurisdictions and a risk register for compliance, data governance, and lab accreditation considerations.
-
M&A and partnership playbook with target archetypes, valuation sensitivities, and integration checkpoints for buyers and sellers.
Strategic implications and recommended actions for 2026
-
Prioritize evidence that aligns to reimbursement triggers: Focus 2026 clinical investments on outcomes and health‑economics endpoints that payers use to define coverage (e.g., transplant rejection avoidance, avoided downstream costs in oncology).
-
Choose platform vs. niche strategies deliberately: Scale players should accelerate lab network and payer contracting; specialists should double down on narrowly defined use cases with defensible evidence and reimbursement defensibility.
-
Operationalize compliance and data governance early: CLIA/CAP readiness, genomic data privacy processes, and scalable lab staffing models are prerequisites to commercial expansion.
-
Leverage partnerships for distribution and scale: Instrument vendors, reference labs, and regional clinical networks can shorten commercialization timelines and reduce CapEx barriers.
-
Build modular commercialization templates: Standardized reimbursement dossiers, payer value narratives, and clinician education toolkits accelerate market access and reduce sales cycle friction.
Risks and watch points
-
Payer backlash or slow coverage expansion remains a top downside risk; companies must maintain adaptive pricing and evidence plans.
-
Labor availability and lab capacity constraints can become operational bottlenecks during rapid scaling; automation and outsourcing should be evaluated.
-
Regulatory shifts in data handling or genetic testing scope could alter commercialization paths; active regulatory monitoring and scenario planning are essential.
How executives should use this briefing in 2026 planning
-
Board and C‑suite: Use the market trajectory and concentration insights to prioritize portfolio allocation, evaluate M&A targets, and define capital deployment timelines for lab and platform investments.
-
Commercial teams: Adopt the playbooks for payer engagement and clinician uptake; use the template dossiers to compress time‑to‑coverage.
-
R&D and product: Align product roadmaps with the highest‑value clinical endpoints and interoperability requirements that accelerate adoption by integrated delivery networks and reference labs.
Accessing the full intelligence
This release intentionally highlights the high‑value, actionable intelligence contained in PW Consulting’s CfDNA Testing Market report while withholding detailed segment‑level dollar and percentage splits to preserve the report’s exclusive analytical value. The full report includes detailed regional and application breakouts, vendor financial estimates, downloadable model workbooks, and an exhaustive list of primary sources — resources designed to directly support transaction diligence, product launches, and payer negotiations.
To access the comprehensive dataset, scenario models, and vendor scorecards that underpin this briefing — and to arrange a strategy workshop with PW Consulting’s cfDNA practice — please visit our report page or contact your PW Consulting representative.
PW Consulting’s CfDNA Testing Market report is crafted for executives who must translate evolving science into defensible commercial outcomes in 2026. Our analysis shows the market is large, growing, and contestable — but the winners will be those who pair scientific differentiation with operational scale, payer strategy, and disciplined evidence generation.
For detailed analysis of this topic, please visit the official page: Cfdna Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Hectorite Clays Market Poised to Reach USD 1,646.01 Million by 2032
By pmarketresearch, 2026-07-13
Hectorite Clays Market — Strategic Outlook for 2026: Why this Commodity Matters to Industrial and Specialty Chemical Decision‑Makers
As global manufacturers recalibrate product portfolios for resilience, sustainability and margin recovery, hectorite clays have re‑emerged as a high‑leverage material in several specialty value chains. PW Consulting’s Hectorite Clays Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—provides the actionable intelligence procurement, product, and corporate strategy teams need to convert mineral endowments into commercial advantage in 2026 and beyond.
Hectorite Clays Market
Headline market trajectory (what we measured)
Our analysis shows the hectorite market has moved from the mid‑single hundreds of USD million in the early 2020s into a structurally larger market by 2025, and continues to expand through the forecast window at a compound annual growth rate (CAGR) of roughly 4.8%. This steady growth masks meaningful near‑term variability driven by formulation trends in cosmetics and coatings, drilling demand cycles, and the evolving balance between natural and synthetic supply sources.
Hectorite Clays Market
Why this matters for 2026 decision cycles
- Procurement and supply security: Hectorite’s supply base is concentrated and differentiated by source type. Firms with exposure to formulations sensitive to trace minerals, or those operating in regulated end markets, need a procurement playbook that recognises both geological constraints and the premium for sustainably sourced natural material.
- Product formulation and NPD prioritisation: New product development decisions in personal care, coatings and specialty adhesives will hinge on rheological performance versus sustainability claims. Manufacturers must test trade‑offs between synthetic and modified natural clays to optimise cost, performance and marketing position.
- M&A and partnership focus: Market concentration is material and buying patterns favour near‑specialist producers. Strategic buyers and investors should prioritise targets that (a) control high‑purity natural feedstock, (b) offer proprietary modification platforms, or (c) bring formulation R&D that shortens customer validation cycles.
- Regulatory and sustainability compliance: 2026 will see more procurement contracts and product launches conditioned on transparent sourcing and lower life‑cycle impacts. Companies that can document both responsible extraction and low‑carbon processing will enjoy preferential access to premium channels.
What the data implies for 2026 strategies
At a macro level, the market’s CAGR near 4.8% indicates predictable expansion rather than explosive disruption—an environment suited to deliberate, capability‑building moves rather than speculative bets. Tactical implications include:
Hectorite Clays Market
- Hedge with dual sourcing: Where formulations permit, maintain both natural and engineered supply routes to manage price and availability shocks.
- Invest in application validation: Allocate R&D budget to head‑to‑head performance testing (suspension, texture, spreadability, shear recovery) and to generate claims‑supporting data for regulated end markets like cosmetics.
- Prioritise sustainability KPIs: Embed supplier environmental performance and mine rehabilitation metrics into procurement scorecards to reduce transition risk as downstream customers intensify ESG demands.
- Monitor concentration indicators: The market exhibits meaningful top‑tier concentration; buyers should track supplier stability and contingency capacity closely as part of their 2026 vendor risk assessments.
Competitive landscape — who matters and why
The hectorite value chain is populated by a mix of vertically integrated miners, specialty formulators, and additives companies that convert raw mineral into application‑ready rheology modifiers. Key players we profile and monitor include global mineral majors, specialty additives groups, and regional producers that feed local coatings and cosmetics supply chains.
- Elementis plc (UK/USA) — Controls the world’s principal high‑grade natural hectorite deposit and packages it into industry‑recognised brands. Their recent product introductions and focus on naturally activated lines highlight a strategy to capture premium formulation space while leveraging a unique upstream asset.
- China‑based specialty producers — Several manufacturers supply synthetic and organoclay variants targeted at drilling, paints and cosmetics. Their strengths are cost competitiveness, scale for regional markets, and fast product customisation cycles.
- Global additives and chemicals groups — Established additives players incorporate hectorite variants into broader portfolios, offering formulation services and global distribution—valuable to multinational end users seeking single‑vendor simplification.
- Specialist suppliers and processors — Smaller firms focus on niche organo‑modified grades or customer‑specific processing capabilities; they are important partners for co‑development in high‑value segments.
Recent product launches and technical advances provide real signals about where competition is heading. New “all‑in‑one” hectorite blends aimed at personal care formulations and targeted demonstrations of natural activation indicate a combined strategy of premiumisation and technical differentiation. Separately, academic and industrial research into mesoporous and steam‑assisted synthesis routes signals a longer‑term trend toward engineered microstructures with improved adsorption and rheology control.
Supply fundamentals and regulatory context
Hectorite’s upstream picture is atypical for a clay mineral: globally important natural feedstock is concentrated in a small number of deposits, with at least one major commercial mine offering a long resource life. That geological efficiency lowers the number of independent natural suppliers relative to other minerals, and it increases the strategic value of secure offtake and long‑term sourcing agreements.
Regulatory frameworks relevant to 2026 decisions include cosmetics safety assessments and evolving environmental standards for mineral extraction. Long‑established safety assessments support the use of certain modified hectorite grades in cosmetic formulations under specified concentration limits, which facilitates product development but does not remove the need for traceability and supplier documentation. Meanwhile, tightening environmental expectations in major markets are nudging both formulators and miners toward demonstrable stewardship practices.
What the PW Consulting report delivers (practical content you can use)
- Actionable market sizing and demand scenarios (2020–2025 historical base plus a 2026–2032 forecast) to underpin budgeting and MRP decisions.
- A supplier risk matrix and procurement playbook that includes contracting templates, recommended hedging approaches, and inventory buffers calibrated to application criticality.
- Competitive dossiers with capability maps for the major producers, including proprietary product positioning and go‑to‑market strengths.
- Segment‑level demand drivers (cosmetics, drilling, coatings, adhesives and other industrial uses) linked to actionable KPIs for pricing and formulation teams—presented as qualitative signals and decision rules rather than raw tables in this preview.
- Regulatory and sustainability roadmaps highlighting compliance triggers and low‑cost measures to capture green premium opportunities.
- M&A and JV opportunity assessment with shortlist criteria that reflect resource access, formulation IP and route‑to‑market synergies.
To respect strategic confidentiality and drive verification, the report’s full quantitative regional and application splits, vendor market shares and transaction models are provided exclusively in the source document and supporting data annexes.
Risks, leading indicators and monitoring framework
- Supply disruption risk: Concentrated natural supply increases exposure to operational outages. Leading indicators: mine operating reports, shipment lead times, and new capacity announcements from synthetic producers.
- Demand volatility: End‑market cyclicality (notably drilling and industrial coatings) can shift volumes quickly. Leading indicators: OEM orderbooks, construction activity indices, and seasonality in consumer personal care launches.
- Regulatory shift risk: Revisions to cosmetic ingredient guidance or mineral extraction permitting could change sourcing preferences. Leading indicators: regulatory advisory committee agendas and major market ESG procurement policies.
- Technology disruption: Advances in engineered hectorite or alternative rheology systems could alter value capture. Leading indicators: patent filings, peer‑reviewed material science publications and strategic partnerships between additives firms and research institutions.
How to use this insight in 90 days (recommended next steps)
- Commission formulation head‑to‑head tests to validate switching costs between natural and synthetic hectorite in core SKUs.
- Run supplier stress tests using the procurement playbook included in our report (simulate 30‑ and 90‑day supply shortfalls to quantify margin impact).
- Prioritise a shortlist of strategic suppliers for multi‑year agreements and negotiate environmental performance clauses tied to price adjustments.
- Brief your M&A committee on acquisition criteria that capture resource access, downstream formulation capability, and customer contracts.
Conclusion — the strategic takeaway
Hectorite is no longer just an obscure rheology additive; it is a strategically relevant mineral whose sourcing, modification and certification can materially affect product performance, brand claims, and margin outcomes. For 2026 planning cycles, decision‑makers should treat hectorite as a component that requires integrated sourcing, R&D and sustainability strategies. PW Consulting’s Hectorite Clays Market report delivers the quantitative forecast, supplier intelligence and execution templates needed to turn market structure into an advantage—while reserving the proprietary segmentation tables and supplier share datasets for the full report.
For access to the full dataset, regional and application splits, supplier shares, and downloadable procurement tools, please refer to the PW Consulting report landing page linked in our distribution materials.
For detailed analysis of this topic, please visit the official page: Hectorite Clays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Security MCU Market to Reach USD 8,896.97 Million by 2032 on an 8.2% CAGR (Base Year: 2025)
By pmarketresearch, 2026-07-13
Security Microcontroller (MCU) Market — 2026 Strategic Bulletin
PW Consulting’s latest market intelligence shows the global security microcontroller market at a pivotal inflection point. Using 2025 as the base year and a verified historical series from 2020–2025, our report projects the market to expand at a compound annual growth rate (CAGR) of 8.2% over the 2026–2032 forecast window. That trajectory reflects accelerating demand across connected devices, payment and identity infrastructure, and safety-critical systems — even as suppliers and buyers navigate acute supply-side stress, regulatory friction, and rapid security technology evolution.
Security Microcontroller Mcu Market
Why this briefing matters to enterprise leaders in 2026
-
Procurement and supply-chain leaders face price volatility and lead-time risk. In 2026 several major suppliers announced price adjustments and foundry and package capacity remains constrained — dynamics that materially affect sourcing strategy, working capital, and inventory policies for any program that embeds security MCUs.
Security Microcontroller Mcu Market -
Product and embedded-systems teams must reconcile trade-offs among security architectures (hardware secure elements, Trusted Execution Environments, and security-enabled standard MCUs) while preserving time-to-market. Design choices made now will determine certification timelines, upgrade paths for post-quantum cryptography, and overall device trustworthiness.
Security Microcontroller Mcu Market -
C-suite decisionmakers (CTO/CPO/CISO/CFO) need an integrated view that maps regulatory exposure (e.g., export controls affecting international sourcing), pricing trajectory, and vendor concentration—because these factors drive capital allocation, M&A screening, and strategic partnerships in 2026 and beyond.
What PW Consulting’s Security MCU Market Report delivers (practical, board-ready outputs)
-
Market sizing and forecast model (2020–2032) with transparent assumptions and scenario toggles. The report uses 2025 as the validation point and provides a base-case projection for the 2026–2032 period consistent with an 8.2% CAGR.
-
Actionable supplier scorecards and a vendor risk matrix that combine technology maturity, certification footprint, supply-chain resilience, and commercial posture—designed for sourcing negotiations and preferred-vendor decisions.
-
Security-architecture decision framework that helps engineering teams choose between hardware secure elements, TEEs, and security-enabled standard MCUs according to threat model, cost-to-implement, certification timelines, and upgradeability for emerging crypto standards.
-
Procurement playbook: hedging and dual-sourcing templates, inventory thresholds tied to lead-time scenarios, and pricing-index clauses calibrated for the 2026 supplier pricing environment.
-
Regulatory and geopolitical impact assessment including export-control sensitivity matrices and a compliance checklist for cross-border programs.
-
M&A and partnership screening toolkit that flags targets for capability gaps (e.g., post-quantum crypto IP, secure element manufacturing, embedded secure OS) and calculates integration risk-adjusted returns.
-
Scenario analyses covering: aggressive capacity tightening, rapid post-quantum adoption in high-value verticals, and progressive certification demands — each with tailored mitigation playbooks.
Competitive landscape — concise, strategic takeaways
The security MCU market exhibits moderate concentration: the top-three suppliers account for a meaningful share of revenues, and the top-five further increase concentration. This structure creates both stability (large suppliers with deep certification and channel reach) and strategic risk (supplier-specific constraints can propagate across multiple OEM programs).
-
NXP Semiconductors — Strong in payment, eID, and multi-application secure elements. NXP’s SmartMX3 family and EdgeLock portfolio deliver integrated security building blocks that favor customers needing certified, long-life credential solutions. Expect NXP to continue leveraging cryptographic acceleration and card-grade credentials as differentiation in regulated verticals.
-
Infineon Technologies — Broad portfolio spanning automotive-grade MCUs (safety + security) and dedicated security controllers. Infineon’s roadmap emphasizes hardware root-of-trust and high-assurance automotive/industrial solutions; partners will value its safety-security co-design capabilities for ADAS and industrial control uses.
-
STMicroelectronics — A hybrid play across secure elements and mainstream STM32 families, with recent product introductions in 2026 aimed at entry-level secure MCUs that meet SESIP/PSA benchmarks. ST’s strength is its ecosystem: developer tools, connectivity options, and a clear certification pathway for IoT and industrial customers.
-
Microchip Technology — Offers pragmatic, cost-sensitive secure MCU options suitable for industrial and consumer applications that require straightforward secure boot, crypto accelerators, and robust peripheral integration. Microchip is a steady choice where predictable supply and long product lifecycles matter.
-
Renesas Electronics — Focused on automotive and embedded systems with integrated security and functional-safety capabilities. Renesas is strategically positioned for partners needing combined cybersecurity and ISO 26262-style safety assurances.
-
Texas Instruments — Strong in industrial and edge compute segments, offering Arm-based MCUs with hardware crypto and a value-oriented approach for high-reliability applications.
Recent industry movements have tangible strategic consequences: STMicroelectronics’ 2026 launch and product showcase of new entry-level secure MCUs signals intensified competition at the lower-cost secure MCU tier. Separately, deployments of post-quantum enabled secure microcontrollers have moved from R&D into active field trials, indicating early commercialization of quantum-resilient platforms. These trends heighten the need for firms to plan for multiple generational transitions in secure firmware and key management.
Contextual risks and near-term market drivers (must-track)
-
Export controls and geopolitics: Ongoing restrictions on advanced semiconductor exports continue to complicate cross-border procurement and strategic sourcing — particularly for programs that span North America, Europe, and Asia.
-
Supply-side pressure: Capacity constraints at foundries and packaging facilities, intensified by AI-driven demand for advanced nodes, are lengthening lead times and elevating inventory risk for MCU programs.
-
Price volatility: Several leading suppliers announced price increases in 2026, directly affecting BOM assumptions and necessitating faster cost pass-through or renegotiation strategies for OEMs.
Recommended actions for 2026 (prioritized)
-
Next 3–6 months: Execute supplier-risk audits for all programs containing security MCUs. Institute binding supply clauses (lead-time/KPIs) and commence targeted dual-sourcing where certification timelines allow. Recast last-mile inventory buffers for critical program milestones.
-
6–18 months: Rationalize product roadmaps to modularize security components (support swappable secure element modules or OTA-upgradable TEEs). Begin proofs-of-concept for post-quantum key management in parallel with existing cryptographic stacks to avoid forked upgrade paths.
-
18–36 months: Consider strategic partnerships or tuck-in acquisitions to secure IP in quantum-resistant cryptography or to vertically integrate critical secure-element manufacturing. Embed certification timelines and supply constraints into R&D gating and commercial forecasts.
How boards and executive committees should use this report
Share the report’s executive model in board packs to quantify the financial impact of supply-side scenarios and to calibrate contingency funding for procurement and certification. Use the vendor scorecards in vendor-review cycles, and apply the M&A screening toolkit to assess acquisition targets that accelerate secure-architecture roadmaps. Security and engineering leadership should adopt the architecture decision framework as the canonical reference during product design sprints.
Where we withhold detail — and why
In this release we intentionally present market-level sizing, CAGR, and strategic highlights to establish context and immediate decision levers. We have withheld granular regional, type, and application split numbers and proprietary vendor scoring metrics in order to preserve the report’s proprietary value and to encourage direct access to the full datasets. The full report includes downloadable models, interactive scenario sliders, and the detailed segmentation tables that enterprise teams use for contract negotiations and program costing.
Next steps
PW Consulting’s Security Microcontroller MCU Market report is designed as an operational toolkit for 2026 decision cycles. For access to the full report, interactive models, and bespoke advisory support — including a supplier risk workshop or a tailored scenario run for your product portfolio — please visit our research portal or contact your PW Consulting account lead. The full intelligence package includes the datasets and segment-level analysis necessary to convert the strategic directions in this bulletin into executable plans.
For detailed analysis of this topic, please visit the official page: Security Microcontroller Mcu Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com