

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: cfDNA Testing Market Hits USD 7,550 Million in 2025, Poised for 13.6% CAGR Through 2032

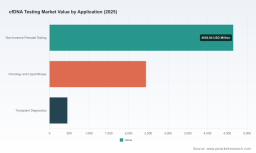
PW Consulting: Strategic Outlook — cfDNA Testing Market to Accelerate Through 2026 and Beyond with a 13.6% CAGR
PW Consulting today publishes an executive briefing from our forthcoming CfDNA Testing Market report (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032), offering senior leaders a decision-ready synthesis of trends that will shape capital allocation, product strategy, and partnership choices across diagnostics, life sciences, and healthcare delivery in 2026. Our high‑granularity market model projects sustained, double‑digit expansion (13.6% CAGR) through 2032 — reflecting a maturing clinical evidence base, expanded commercial reimbursement pockets, and rapid technology platform improvements — and positions cfDNA testing as a core growth domain for diagnostics and precision medicine portfolios.
Cfdna Testing Market
Why this matters for 2026 decision cycles
-
Investment timing: The market is at an inflection where platform investments (sequencing, automation, AI analytics) and commercial scale deliver differentiated unit economics. Companies deciding on CapEx, strategic partnerships, or early M&A in 2026 must reconcile technical scale with payer access and lab network reach.
Cfdna Testing Market -
Reimbursement and policy windows: Recent updates in payer guidance and Medicare coverage for select diagnostic uses create a narrow window for commercial rollout and clinical validation that materially affects near‑term revenue realization.
Cfdna Testing Market -
Clinical adoption levers: Consolidation of clinical guidelines and accruing prospective data are accelerating adoption in transplant monitoring, oncology (MRD/liquid biopsy), and prenatal screening — each requiring distinct evidence and commercialization playbooks.
High‑level market trajectory (what our model shows)
-
From a baseline established through 2025, our model indicates pronounced growth over 2026–2032. The market expands meaningfully year‑over‑year as sequencing economies improve and new clinical protocols diffuse into standard care pathways.
-
The market concentration is moderate-to-high: the top three players account for roughly 42.5% of market activity while the top five cluster at about 58.3% — a structure that favors scale players with integrated offerings (test menu + lab network + payer contracts), while leaving meaningful runway for specialist entrants and disruptive platform providers.
Primary growth dynamics and drivers
-
Technology scaling and cost per test decline: Improvements in NGS workflows, library prep kits, and automation suppliers are lowering unit costs and enabling broader use cases beyond traditional prenatal screening.
-
Cross‑modal analytics: Emerging multi‑modal AI models that combine longitudinal ctDNA signals, imaging, and clinical metadata are improving MRD stratification and therapy selection — a key differentiator for oncology offerings.
-
Payer landscape and guideline consolidation: Targeted Medicare coverage for select dd‑cfDNA transplant tests and updated prenatal screening guidance from major administrators are creating definable commercial pathways, but coverage remains use‑case specific and demands robust health economics evidence.
-
Operational complexity and labor: High‑quality cfDNA testing requires specialized lab labor and CLIA/CAP compliance. Labor cost and access to certified lab capacity remain gating factors for rapid geographic expansion.
Competitive landscape — strategic read on leading players
Our competitive benchmarking synthesizes positioning across technology, clinical depth, commercial reach, and strategic intent. In the current environment:
-
Natera, Inc. (Austin): Strength lies in a diversified test portfolio that spans prenatal, oncology (MRD), and transplant monitoring, combined with active investments in AI for longitudinal cfDNA analytics. Recent product launches and MRD modeling breakthroughs underscore a platform expansion approach.
-
Guardant Health (Palo Alto): Continues to lead in oncology‑focused liquid biopsy profiling and has emphasized screening and therapy selection use cases, leveraging commercial alliances with oncology stakeholders and pharma.
-
Illumina (San Diego): Acts as an enabling platform player; its sequencing systems and assay solutions remain critical to clinical labs scaling cfDNA workflows and to new entrants seeking clinical throughput.
-
CareDx (Brisbane): A specialist in transplant dd‑cfDNA monitoring with a clinical and reimbursement foothold; publicized coverage decisions for AlloSure demonstrate the value of targeted clinical utility evidence.
-
BillionToOne (Menlo Park): Rapidly expanding both prenatal and oncology fronts with targeted assay launches and product expansions that aim to capture niche, high‑value use cases.
-
Roche, Labcorp, Quest, Thermo Fisher, Myriad and other incumbents: These organizations play mixed roles — from reagent and instrumentation supply to test provision and lab services — and will influence standards, throughput economics, and channel dynamics.
Recent market movements that matter for 2026
-
Product launches and platform extensions by leading pure‑play cfDNA companies have continued into early 2026, indicating sustained R&D velocity and market expansion intent.
-
Clinical validation updates for transplant dd‑cfDNA assays are reducing uncertainty and supporting payer coverage conversations.
-
Regulatory and payer signals (guideline updates and selective Medicare coverage) are crystallizing reimbursement paths but also raising the bar for evidence generation and real‑world outcomes measurement.
What the PW Consulting report delivers (practical, transaction‑grade content)
-
Proprietary market model (2020–2032) with scenario analyses and sensitivities tailored to technology cost curves, reimbursement uptake, and adoption velocity.
-
Commercial playbooks for three principal use cases (prenatal screening, oncology MRD/liquid biopsy, transplant monitoring), including pricing levers, channel strategies, and recommended clinical partnerships.
-
Competitive scorecards and vendor capability matrices that map tech stack, regulatory posture, clinical evidence, and go‑to‑market reach.
-
Payer landscape and health economics templates for dossier preparation, coverage engagement strategies, and modeling of reimbursement scenarios.
-
Regulatory pathway mapping for major jurisdictions and a risk register for compliance, data governance, and lab accreditation considerations.
-
M&A and partnership playbook with target archetypes, valuation sensitivities, and integration checkpoints for buyers and sellers.
Strategic implications and recommended actions for 2026
-
Prioritize evidence that aligns to reimbursement triggers: Focus 2026 clinical investments on outcomes and health‑economics endpoints that payers use to define coverage (e.g., transplant rejection avoidance, avoided downstream costs in oncology).
-
Choose platform vs. niche strategies deliberately: Scale players should accelerate lab network and payer contracting; specialists should double down on narrowly defined use cases with defensible evidence and reimbursement defensibility.
-
Operationalize compliance and data governance early: CLIA/CAP readiness, genomic data privacy processes, and scalable lab staffing models are prerequisites to commercial expansion.
-
Leverage partnerships for distribution and scale: Instrument vendors, reference labs, and regional clinical networks can shorten commercialization timelines and reduce CapEx barriers.
-
Build modular commercialization templates: Standardized reimbursement dossiers, payer value narratives, and clinician education toolkits accelerate market access and reduce sales cycle friction.
Risks and watch points
-
Payer backlash or slow coverage expansion remains a top downside risk; companies must maintain adaptive pricing and evidence plans.
-
Labor availability and lab capacity constraints can become operational bottlenecks during rapid scaling; automation and outsourcing should be evaluated.
-
Regulatory shifts in data handling or genetic testing scope could alter commercialization paths; active regulatory monitoring and scenario planning are essential.
How executives should use this briefing in 2026 planning
-
Board and C‑suite: Use the market trajectory and concentration insights to prioritize portfolio allocation, evaluate M&A targets, and define capital deployment timelines for lab and platform investments.
-
Commercial teams: Adopt the playbooks for payer engagement and clinician uptake; use the template dossiers to compress time‑to‑coverage.
-
R&D and product: Align product roadmaps with the highest‑value clinical endpoints and interoperability requirements that accelerate adoption by integrated delivery networks and reference labs.
Accessing the full intelligence
This release intentionally highlights the high‑value, actionable intelligence contained in PW Consulting’s CfDNA Testing Market report while withholding detailed segment‑level dollar and percentage splits to preserve the report’s exclusive analytical value. The full report includes detailed regional and application breakouts, vendor financial estimates, downloadable model workbooks, and an exhaustive list of primary sources — resources designed to directly support transaction diligence, product launches, and payer negotiations.
To access the comprehensive dataset, scenario models, and vendor scorecards that underpin this briefing — and to arrange a strategy workshop with PW Consulting’s cfDNA practice — please visit our report page or contact your PW Consulting representative.
PW Consulting’s CfDNA Testing Market report is crafted for executives who must translate evolving science into defensible commercial outcomes in 2026. Our analysis shows the market is large, growing, and contestable — but the winners will be those who pair scientific differentiation with operational scale, payer strategy, and disciplined evidence generation.
For detailed analysis of this topic, please visit the official page: Cfdna Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com