

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insights: Paper Laminates Market Poised for 5.48% CAGR (2026–2032)

Paper Laminates Market 2026: Strategic Signals and Action Roadmap — PW Consulting Preview
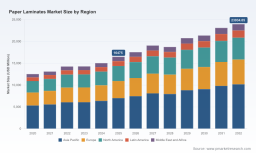
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise yet incisive preview of our full Paper Laminates Market research report. The industry is entering a decisive phase: after expanding from roughly USD 12,510 million in 2020 to USD 16,475 million in 2025, global demand is forecast to continue growing at a compounded annual growth rate (CAGR) of 5.48% through our 2026–2032 forecast horizon. By 2032 the market is projected to approach the mid‑twenty billion USD mark. These macro dynamics, combined with accelerating regulatory pressure and raw material volatility, mean that 2026 will be a pivotal year for strategic moves — and the full report provides the operational intelligence executives need to act with conviction.
Paper Laminates Market
Why this preview matters to executives planning for 2026
- It synthesizes the most consequential market signals: steady overall growth, fragmented supplier structure, and intensifying regulatory mandates that shift the economics of lamination choices.
- It highlights actionable frameworks — not just descriptive statistics — that procurement, product, and M&A leaders can apply immediately to scenario planning, supply‑chain hedging, and portfolio rebalancing.
- It follows a “teaser” approach: we show you the analytical depth and the decision-grade outputs while withholding the proprietary segmentation matrices and granular figures that you’ll find in the full report.
Market trajectory and structure — what the headlines reveal
The paper laminates market has moved from recovery into a structural upswing. After a mid‑cycle plateau in 2023, the sector regained momentum in 2024–2025 driven by renewed demand in packaging and construction applications and an uptick in sustainable-lamination adoption. The 5.48% CAGR we forecast for 2026–2032 incorporates both near-term cyclical effects and medium-term structural shifts toward recyclable and bio‑based laminates.
Paper Laminates Market
One important competitive signal: the market remains moderately fragmented. The combined share of the top three and top five providers indicates that no single player dominates — creating opportunity for targeted consolidation, technology differentiation and scale plays in logistics or specialty barrier solutions.
Paper Laminates Market
What the full report contains — practical, executable deliverables
PW Consulting’s full report is designed as a toolkit for practitioners. Key deliverables include:
- Strategic growth playbooks by demand cluster — frameworks to prioritize segments based on margin resilience, regulatory exposure, and supplier leverage.
- Supply‑chain risk matrix and sourcing heatmap — supplier concentration, raw material exposure, and lead‑time scenarios to support procurement hedging and near‑shoring choices.
- Regulatory impact scoring model — scoring and scenario stress‑tests for major markets that translate upcoming mandates into P&L and product‑design implications.
- Cost sensitivity and pass‑through modeling — multi‑factor simulations incorporating pulp and polymer feedstock price shocks, logistics disruptions, and potential carbon pricing.
- M&A and partnership heatmaps — tactical targets and capability gaps by technology (e.g., extrusion lamination, barrier coatings, aseptic systems) with suggested deal rationale and integration risks.
- Go‑to‑market playbooks — channel strategies for converters, laminators, and end‑users with differentiated pricing, certification roadmaps and circularity communications.
Regulatory and input‑cost dynamics shaping 2026 choices
Two regulatory vectors and two input‑cost realities will disproportionately influence vendor and buyer strategies in 2026:
- Regulatory pressure toward recycled content and circularity. The European Packaging and Packaging Waste Regulation’s recycled‑content mandates, California’s Extended Producer Responsibility (EPR) requirements already in effect, and single‑use plastic restrictions collectively raise the stakes for meeting minimum recycled content thresholds and for delivering demonstrably recyclable laminate constructions. These requirements translate into reformulation costs, chain‑of‑custody considerations, and labeling complexity — all of which are modeled in our regulatory impact scoring tool.
- EPR and compliance costs are forcing brand owners to re‑evaluate paper versus plastic lamination trade‑offs. Legal and reputational risks favor paper‑dominant or recyclable hybrid constructions, but the cost delta and functional barriers (e.g., moisture and oxygen barrier performance) require careful technical and commercial trade‑offs.
- Raw material price volatility. Recent price markers we track — such as bleached hardwood kraft pulp averaging near USD 820/metric ton (Q4 2025) and LDPE resin prices observed around USD 1,250/metric ton in Asia‑Pacific markets (Q1 2026) — create immediate margin pressure for extrusion‑laminated constructions and for any solution that relies on polymer films. These dynamics are embedded in our cost‑sensitivity models and supplier negotiation playbooks.
- Availability and certification of recycled feedstock. Access to certified recycled fibers and mass‑balanced production streams is an increasingly scarce advantage that some early movers have secured to meet incoming mandates; our supplier capability benchmarking highlights which partners have credible scale and certification readiness.
Competitive landscape — who’s moving and what their plays mean for 2026 strategy
The report provides a non‑exhaustive competitive analysis of leading paper and packaging players who are materially shaping market direction. Below are high‑level profiles and strategic observations.
- Mondi Group (Vienna, Austria — https://www.mondigroup.com) : Mondi’s innovation cadence around recyclable flexible packaging (for example, its 2025 PEEL & SEAL paper‑based laminate launch) positions it to capture demand from brands seeking mono‑material solutions. Their R&D and production scale make them a natural partner for co‑development — particularly for premium food applications where seal integrity matters.
- WestRock Company (Atlanta, USA — https://www.westrock.com) : WestRock’s extrusion coating capabilities and recent exhibition of fiber-based, high‑barrier laminates at trade shows signal an emphasis on defending folding carton and flexible packaging share by improving barrier performance while retaining recyclability claims.
- Smurfit Kappa Group (Dublin, Ireland — https://www.smurfitkappa.com) : Progress on certification (e.g., ISCC PLUS for recycled content) reinforces Smurfit Kappa’s value proposition for customers under recycled‑content mandates. Expect them to push integrated carton‑plus‑laminate solutions for retail and liquid packaging.
- International Paper Company (Memphis, USA — https://www.internationalpaper.com) : With capabilities in corrugated and specialty laminates, International Paper is positioned to monetize demand in logistics‑sensitive packaging chains where lamination enhances durability and stackability.
- DS Smith plc (London, UK — https://www.dssmith.com) : Their sustainability‑first positioning and extrusion‑laminated offerings target e‑commerce and food sectors, where single‑use plastic restrictions and consumer scrutiny are greatest.
- Tetra Laval / Tetra Pak (Pully, Switzerland — https://www.tetrapak.com) : As a specialist in multi‑layer aseptic cartons, Tetra Pak’s technical moat in PE and aluminum foil laminates for liquid packaging keeps it central to any discussion on high‑performance paper laminates for beverages.
- Stora Enso Oyj (Helsinki, Finland — https://www.storaenso.com) : Stora Enso’s mass‑balanced production and investments in renewable barrier coatings underscore a longer‑term transition to polymer‑alternative laminates — a key consideration for brands targeting plastic reduction commitments.
Recent corporate moves — product launches, certification achievements and capacity additions during 2025 and early 2026 — are not random. They reflect a common strategic response: secure feedstock and certification, raise technical performance of paper‑based laminates, and use marketing claims to capture brands shifting away from traditional plastic laminates. Our competitive heatmap ranks these initiatives by strategic significance and replicability, helping executives prioritize partnerships or defensive investments.
Actionable priorities for 2026
Based on our synthesis, organizations should prioritize the following in 2026:
- Conduct a rapid regulatory gap analysis and reprice SKUs that will bear EPR costs or require reformulation; treat compliance as a product development imperative rather than a back‑office cost.
- Secure access to certified recycled fiber and mass‑balance production capacity to avoid late‑stage reformulation bottlenecks; consider strategic contracts, minority equity plays, or supply agreements tied to certification milestones.
- Invest selectively in barrier innovation (coatings, AL foil hybridization, or advanced extrusion) to maintain functional parity with polymer laminates where needed; offset the investment with premium positioning or cost engineering elsewhere.
- Use CR3/CR5 fragmentation to pursue bolt‑on M&A in regions or technologies where scale will yield logistics or procurement advantage, but validate synergies via our M&A playbook before committing capital.
- Embed raw‑material price stress tests into pricing algorithms; implement dynamic clauses or indexation in supplier and customer contracts where feasible.
How PW Consulting’s report converts insight into decisions
This report is structured to move users from insight to execution within 90 days. Deliverables include a prioritized action list customized to buyer or supplier archetypes, an editable financial model with raw‑material scenarios, and a supplier‑selection tool that combines capacity, certification and proximity. Importantly, we provide an M&A decision framework with valuation sensitivities and integration checklists specific to paper‑laminate assets.
Next step — where to get the full intelligence
This preview maps the strategic landscape and highlights the specific actions that will determine winners and laggards in 2026. For the full dataset, proprietary segmentation matrices, interactive models and supplier rankings, access to the complete PW Consulting Paper Laminates Market report is required. The full report contains the granular regional, application and type splits, as well as the scenario outputs that are critical for formal board or investment committee approval.
Contact PW Consulting to obtain the comprehensive report and associated implementation toolkit. Our team stands ready to convert this market intelligence into a tailored 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Paper Laminates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com