

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Trial Process Management System Market Poised for 13.18% CAGR from 2026–2032

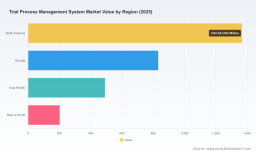
Trial Process Management System Market — Strategic Outlook for 2026 (PW Consulting)
Executive teaser
As enterprises finalize technology budgets and vendor roadmaps for 2026, the Trial Process Management System market stands at an inflection point. Our new PW Consulting report—anchored on 2025 as the base year—shows the market reaching roughly USD 2,892.6 million (revenue unit: Million USD) in 2025, with a sustained compound annual growth rate (CAGR) of 13.18% through our 2026–2032 forecast horizon. By 2032, PW Consulting projects the market to approach the multi‑billion dollar threshold that will reframe how sponsors, CROs and research sites budget for clinical operations and data orchestration.
Trial Process Management System Market
Why this research matters for 2026 decisions
-
Speed vs. compliance: Sponsors and CROs face intensifying pressure to compress timelines while meeting stricter regulatory expectations—forcing tradeoffs in platform selection, validation cadence and operational staffing.
Trial Process Management System Market -
AI and orchestration are no longer optional: Leading vendors are embedding AI companions, virtual twins and orchestration layers into CTMS suites. Assessing maturity and production readiness of these capabilities is central to 2026 procurement decisions.
Trial Process Management System Market -
Cybersecurity/regulatory tightening: Proposed updates to the HIPAA Security Rule (target final action May 2026) introduce mandatory controls—encryption, biannual vulnerability scanning and annual penetration testing—that materially affect vendor selection, contracting and total cost of ownership.
-
Consolidation dynamics: Market concentration indicates room for scale advantages—our concentration analysis shows the top three vendors account for a meaningful portion of market activity (CR3 ≈ 38.45%) and the top five increase that share (CR5 ≈ 54.12%)—but specialist and site‑centric vendors remain strategically important for niche workflows.
What the PW Consulting report delivers (practical, executable content)
-
Decision frameworks: A vendor due‑diligence matrix calibrated for enterprise sponsors, mid‑sized CROs and research sites—covering functional fit, API openness, AI readiness, validation evidence and commercial terms.
-
TCO & ROI models: Dynamic templates that translate license, implementation, hosting and ongoing labor into multi‑year scenarios; sensitivity analysis for cloud storage/ingress, integration complexity and validation labor.
-
Procurement playbook: Contract archetypes with mandatory clauses (data residency, encryption at rest/in transit, audit rights, BAA requirements) and negotiation levers for pilot‑to‑enterprise transitions.
-
Implementation & change management: A practical 90–180 day implementation checklist, validation IQ/OQ/PQ templates aligned with 21 CFR Part 11, training curricula and site on‑boarding sequences that minimize subject and site burden.
-
Risk and compliance mapping: Crosswalks that map HIPAA, GDPR (Article 25: data protection by design and by default), and FDA/EMA computerized systems expectations to specific technical and organizational controls.
-
Vendor selection scenarios: Playbooks optimized for three archetypes—enterprise consolidation, best‑of‑breed interoperability and site‑led adoption—each with sample KPIs and governance constructs.
Market dynamics: what the macro numbers imply
The macro trajectory—near‑term market growth from a 2025 base of approximately USD 2.9 billion at a 13.18% CAGR—signals robust investment appetite. Buyers should interpret this as a window to secure strategic leverage: with significant expansion ahead, early adopters of maturity‑enhancing capabilities (advanced analytics, orchestrated AI, integrated EHR/EDC workflows) will capture disproportionate operational ROI, while laggards face escalating migration and integration costs. The documented concentration (CR3/CR5) reflects dominant platform footprints but also underscores an expanding middle market where specialist vendors compete on functionality, lower total cost and site friendliness.
Competitive landscape — how to read vendor signals
-
Veeva Systems — Enterprise‑grade CTMS with a growing push toward site enablement (recent SiteVault CTMS and eISF/eConsent integrations). Useful for sponsors prioritizing end‑to‑end Vault ecosystems and tight sponsor‑site data flows.
-
Medidata (Dassault Systèmes) — Emphasizing AI orchestration and virtual twins; strategic partnerships and AI companions position the platform for protocol optimization and real‑time study execution acceleration.
-
Oracle — Siebel/Clinical One heritage with deep EHR/EDC integration credentials; recognized by industry assessments for lifecycle integration and enterprise governance.
-
Advarra — Site and academic center focus with strong capabilities in financial management, billing and regulatory workflow automation—a go‑to where institutional billing and compliance complexity dominate.
-
Parexel, IQVIA — CRO‑anchored CTMS offerings that bundle operational services and informatics; attractive for sponsors seeking integrated service + tech propositions.
-
Clario, RealTime, ArisGlobal, MasterControl — Specialists offering differentiated strengths (endpoint integration, site workflow efficiency, pharmacovigilance integration, quality‑centric CTMS) and are frequently the tactical choice for niche trials or regulated device programs.
Recent vendor moves in 2025–2026 illustrate strategic priorities: Medidata’s AI ecosystem and partnership announcements (early 2026) underscore investment in orchestration; Veeva’s site‑centric SiteVault launch signals a push to lower site friction; Advarra’s product enhancements highlight the competitive focus on analytics and automation for sites; and Oracle’s recognition reaffirms enterprise integration leadership. Buyers should evaluate these moves not as isolated PR events but as directional indicators of where product roadmaps and partner ecosystems will mature through 2026.
Regulatory and operational headwinds that must be budgeted
-
Regulatory controls: Anticipate mandatory technical controls linked to HIPAA Security Rule updates (encryption, scheduled vulnerability scanning, annual penetration testing) and contractually defined BAAs under the HIPAA Privacy Rule. GDPR Article 25 will continue to require demonstrable data protection‑by‑design in clinical systems.
-
Validation obligations: FDA 21 CFR Part 11 and EMA expectations require rigorous validation artifacts—automation does not eliminate documentation; it changes the shape of validation and continuous compliance evidence.
-
Labor and hosting costs: The primary operational cost drivers remain specialist labor for configuration, validation and compliance monitoring, plus cloud hosting fees driven by data volume and integration breadth.
Investment priorities for 2026 — recommended focus areas
-
Prioritize modular, API‑first platforms that reduce integration risk and provide graceful migration paths.
-
Require explicit AI governance and reliability SLAs for any vendor marketing ML/AI features; demand production case studies and failure‑mode assessments.
-
Budget for compliance operationalization: penetration testing, formal vulnerability scanning cadence, and a validation sustainment team—these are non‑optional line items in 2026.
-
Negotiate BAAs, data residency and exit provisions up front; include obligations for de‑identification/pseudonymization and data export mechanisms to avoid later disputes.
-
Invest in site enablement: low/no‑cost site offerings (where available) and training can materially reduce time‑to‑enrollment and site turnover.
Six‑month strategic checklist for procurement & implementation leads
-
Assemble a cross‑functional steering committee (clinical operations, IT/security, regulatory, finance, and site representation).
-
Run a TCO sensitivity analysis across best‑and‑worst‑case scenarios for integration complexity, validation labor and cloud costs.
-
Execute vendor pilots that include security testing, API interoperability proof‑points and an AI feature acceptance test where applicable.
-
Include contractual safeguards: clear SLAs, compliance attestations, audit rights, BAA language, and defined exit/transition services.
-
Define KPIs tied to operational outcomes (subject enrollment velocity, monitoring efficiency, site query resolution time) and instrument progress into vendor compensation where appropriate.
Why PW Consulting’s Trial Process Management System report is essential now
For 2026 strategy, tactical vendor selection is inseparable from long‑term operational design. Our report blends macro forecasting (market sizing and trajectory through 2032), concentration analysis and proprietary procurement frameworks with hands‑on tools—TCO templates, contract archetypes, validation checklists and implementation playbooks—that are immediately actionable. To preserve the strategic value of the full dataset, PW Consulting intentionally presents high‑level insights here while withholding granular subsegment tables and region/application splits. Those detailed breakdowns, vendor scorecards and downloadable templates are available in the full report and accompanying data annex.
If your 2026 roadmap includes a CTMS refresh, cloud migration, AI pilot or an enterprise consolidation program, this PW Consulting research will shorten your decision cycle and reduce downstream cost and compliance surprises. Access the full report to view the proprietary segmentation, vendor scorecards, downloadable procurement models and the complete dataset that support the strategic recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com