

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Undercarriage Parts Market Poised to Grow at a 5.2% CAGR During 2026–2032
By pmarketresearch, 2026-07-13
Undercarriage Parts Market 2026: Strategic Intelligence Briefing — Why This Report Will Shape Your Next Move
PW Consulting today releases a focused industry briefing drawn from our full Undercarriage Parts Market research. As capital allocation cycles reset across OEMs, aftermarket specialists, and private equity players in 2026, the choices you make this year will determine supply chain resilience, margin capture, and market share for the next business cycle. This briefing explains how the market is evolving, the near-term levers that matter, and why our full report is essential for board-level and commercial decisions in 2026.
Undercarriage Parts Market
Market snapshot — directional scale and trajectory
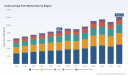
After sustained recovery from cyclical headwinds, the global undercarriage parts market reached approximately USD 8.5 billion in 2025 and is modeled to surpass USD 9.0 billion in 2026. Our proprietary forecast, covering 2026–2032, indicates a compound annual growth rate (CAGR) of 5.2% over the horizon — a pace that reflects a mix of replacement-driven aftermarket demand, OEM production scaling, and pockets of accelerated investment in mining and infrastructure projects.
Undercarriage Parts Market
The trajectory is non-linear: the market has grown materially since 2020, but is exposed to episodic pressures — raw-material volatility, regulatory shifts, and localized project cycles — that can compress margins or temporarily re-route demand between OEM and aftermarket channels. PW Consulting’s scenario overlays capture these oscillations and translate them into decision-ready implications.
Undercarriage Parts Market
Why 2026 is a strategic inflection point
- Capital deployment windows are tightening. Several OEMs and large aftermarket players announced capacity investments in 2024–2026 intended to secure supply and capture growth pockets. These moves mean capacity footprints will be materially different by the end of 2026.
- Input-cost dynamics are reshaping profit pools. Steel price volatility — with U.S. hot-rolled coil topping the USD 1,000/ton mark in early 2026 and cumulative double-digit increases in key markets in the two years before 2025 — is increasing production costs and forcing supplier price realignments and sourcing shifts.
- Regulation and performance demands are raising the bar. Emissions and safety regulations are accelerating the adoption of more durable, lighter, and efficient undercarriage configurations. This trend favors suppliers that combine metallurgy, surface treatment, and design expertise.
Core competitive dynamics (what we found)
The market remains moderately consolidated: the top three firms account for a significant share of revenue, while the top five firms control close to 60% of the market. This structure creates a bifurcated opportunity set — incumbents can leverage scale and integrated offerings, while nimbler challengers can win on specialization and localized cost advantages.
- Caterpillar Inc. — Continues to play as an integrated OEM champion, expanding capacity and product breadth. Its recent USD 500 million investment to increase undercarriage production capacity underscores a strategic bet on securing OEM and large aftermarket volumes.
- Komatsu Ltd. — Focused on system-level innovation. Product previews in 2026 emphasized updated undercarriage configurations that improve durability and ride quality — a signal that Komatsu is prioritizing lifecycle performance as a differentiation lever.
- Specialist manufacturers and aftermarket leaders (e.g., Berco/Thyssenkrupp, ITR/USCO, Topy, Dozco) — Compete on manufacturing depth, material science, and channel relationships. Recent M&A and capacity expansions among regionally-focused suppliers reflect a strategy to capture aftermarket replacement cycles closer to end users.
- OEM/integrated suppliers (e.g., Hitachi, John Deere, Liebherr, Volvo CE) — Continue to prioritize product integration and dealer-led aftermarket capture, investing in service offerings and parts availability to lock in total-cost-of-ownership advantages.
Recent signals to watch
- Komatsu’s CONEXPO‑CON/AGG 2026 previews of next‑generation dozers indicate a renewed OEM focus on undercarriage survivability and operator ride quality — features that will influence aftermarket specifications and replacement cycles.
- Caterpillar’s 2025 production-capacity investment demonstrates a pre-emptive approach to tightening supply and potential vertical integration of key components.
- Regional consolidation and greenfield expansions by specialist manufacturers (including acquisitions in 2025) suggest a two-track market: scale-driven incumbency in core markets and aggressive regional plays in emerging markets.
Strategic implications for executive teams in 2026
- Sourcing and input-cost hedging must be prioritized. With steel costs elevated and volatile, procurement strategies that combine multi-sourcing, long-term contracts, and localized production will reduce margin risk and improve delivery resilience.
- Differentiate through system-level performance, not just unit price. Product strategies that emphasize lifecycle cost, wear performance, and serviceability will command premium pricing and defend aftermarket share.
- Invest selectively in capacity or partnerships. Greenfield investments are capital intensive; in many cases, capacity-sharing agreements, tolling arrangements, or targeted acquisitions deliver faster returns and lower execution risk.
- Monetize aftermarket intelligence. Companies that build predictive maintenance services and parts-as-a-service offerings will generate sticky revenue and improve lifetime customer value.
- Scenario planning is table stakes. Plan for flanking scenarios including sustained steel inflation, a short-term slump in construction zones, and accelerated electrification/automation in heavy equipment that can alter wear patterns.
What PW Consulting’s full report delivers (practical, executable outputs)
- Proprietary market sizing and 2026–2032 forecast models (granular by type, application, and region) with downloadable datasets and sensitivity toggles.
- Competitive-positioning maps and a CR-based concentration analysis to identify white spaces and consolidation targets.
- Supplier due-diligence frameworks and EBITDA accretion models for M&A or JV scenarios.
- Raw-material impact matrices quantifying margin exposure across product types and mitigation playbooks (pricing pass-through, alloy substitution, and tactical inventory strategies).
- Commercial playbooks for OEMs and aftermarket specialists, including SKU rationalization, channel optimization, and service-program design.
- A three-year investment roadmap and a prioritized set of KPIs for operations, procurement, and sales aligned to multiple market scenarios.
- Interactive strategic dashboards and board-level presentation templates to accelerate decision-making.
Risk factors and surveillance triggers
Key risk vectors include continued raw-material inflation, disruptive new entrants with low-cost manufacturing footprints, and regulatory shifts that alter machine specifications. PW Consulting’s report builds in real-time surveillance triggers — thresholds for steel price moves, capacity announcements, and new OEM product launches — that convert market signals into tactical playbook updates.
How to use this report in Q2–Q4 2026 decision cycles
- Board strategy sessions: Use the report’s scenario outputs to stress-test capital plans and M&A pipelines.
- Procurement and operations: Implement the raw-material impact matrices and hedging recommendations to stabilize margins.
- Commercial leadership: Adopt the service and aftermarket playbooks to convert replacement cycles into higher-margin annuity streams.
- Investors and PE sponsors: Leverage the due-diligence frameworks to value regional consolidation targets and model post-close synergies.
Final read — what this briefing omits (and why)
In keeping with the “preview” principle, this briefing highlights directional scale, competitive posture, and action-oriented implications without disclosing proprietary segment-level datasets and region/application splits. Those granular inputs — including detailed type-by-application forecasts, SKU-level margin scenarios, and interactive dashboards that power our valuation and playbook models — are available exclusively in the PW Consulting full report and data package. That level of detail is required to translate the strategic signals above into executable plans with quantified ROI.
Call to action
For boards, strategy teams, and commercial leaders planning 2026 capital and go-to-market moves: the PW Consulting Undercarriage Parts Market report is designed as an operational guidebook. Book a briefing with our senior analysts to review model sensitivities, test M&A cases, and receive a tailored executive summary aligned with your strategic priorities.
Contact PW Consulting to schedule a private walkthrough of the full dataset and scenario models — and ensure your 2026 decisions are powered by market-grade intelligence rather than surface-level signals.
For detailed analysis of this topic, please visit the official page: Undercarriage Parts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glycerophosphoric Acid Calcium Salt Market Valued at USD 240.0 Million in 2025 — 2026–2032 Outlook Released
By pmarketresearch, 2026-07-13
Glycerophosphoric Acid Calcium Salt Market — 2026 Strategic Preview from PW Consulting
PW Consulting today releases a strategic preview of our forthcoming Glycerophosphoric Acid Calcium Salt market study, timed to inform board-level and commercial decisions across 2026. The ingredient market has expanded steadily from USD 184.15 Million in 2020 to USD 240.0 Million in 2025 and—according to PW Consulting’s scenario-weighted base case—is projected to grow at a compound annual growth rate (CAGR) of 5.42% through our forecast window (2026–2032), reaching an anticipated USD 347.27 Million by 2032. This preview highlights the decision-useful insights in the full report, while reserving proprietary granular segmentation and price curves to the report itself.
Glycerophosphoric Acid Calcium Salt Market
Why 2026 Is an Inflection Year
-
Consolidation and concentration: The market is moderately concentrated (CR3 ~41.3%; CR5 ~56.8%), creating both competitive pressures and opportunities for scale-driven margin expansion. Buyers and investors should expect targeted M&A to remain an active lever for accelerating growth or securing supply.
Glycerophosphoric Acid Calcium Salt Market -
Regulatory clarity is lowering adoption friction: Recent regulatory confirmations—most notably continued GRAS recognition and Food Chemicals Codex alignment—have reduced uncertainty for food, supplement, and some pharmaceutical applications. Peripheral approvals (e.g., cosmetic anti‑plaque listings) are widening addressable use cases.
Glycerophosphoric Acid Calcium Salt Market -
Product form and route-to-market innovation: Liquid 50% solutions, pharmaceutical GMP grades, and tailored food/infant nutrition specifications are driving premiumization. Companies that control formulation know-how and certification pathways are winning prioritized supplier status.
-
Supply-side technicalities matter: The ingredient’s manufacture—typically neutralizing glycerophosphoric acid with calcium hydroxide or calcium carbonate—creates specific raw-material and process risk vectors that influence cost, quality, and sustainability footprints.
What the PW Consulting Report Delivers (Practical, Transaction-Ready)
-
Actionable market model: A transparent, auditable market-sizing model (2020–2032) with scenario toggles for demand shocks, regulatory changes, and price swings.
-
Decision-focused segmentation: Comprehensive breakouts by geography, grade, and application to support portfolio prioritization and commercial planning (note: granular segment tables are included in the paid report).
-
Supply chain and margin maps: Cost-to-serve benchmarks for powder vs. liquid formats, lead-time sensitivity analysis, and an input-cost tracker highlighting the most impactful upstream variables.
-
Competitor benchmarking and capability scorecards: Profiles, certification matrices, capacity snapshots, and go-to-market strengths for the leading producers and distributors in the space.
-
Regulatory tracker and risk register: Live-regulation monitoring, common compliance failure modes, and mitigation playbooks for food, pharma, infant nutrition, and cosmetic pathways.
-
M&A and commercial playbooks: Valuation templates, integration checklists, and revenue-synergy calculators tailored to the ingredient sector.
-
Customizable dashboards and workshop deliverables: Ready-to-use slides and spreadsheets for internal alignment and investor conversations.
Competitive Landscape — Strategic Takeaways
Our competitive analysis underscores a mix of vertically integrated manufacturers and specialist ingredient suppliers. Key players include established producers from India and Europe, several US-based suppliers supporting food and pharma customers, and niche outfits offering specialized grades and liquid formats. Across this competitive set, strategic differentiators include:
-
Certifications and regulatory credentials — USDMF/EU-GMP/ANSM/GMP‑pharma designations act as market access keys for infant nutrition and pharmaceutical formulations.
-
Product portfolio breadth — suppliers offering both dry powders and 50% liquid solutions capture different value pools and command differentiated price points.
-
Geographic footprint and logistics — proximity to end-market clusters (e.g., oral care, dietary supplement hubs) materially reduces cost-to-serve and shortens innovation cycles.
-
Customer intimacy and formulation support — players that provide technical application labs, regulatory dossiers, and joint development capabilities secure longer-term contracts.
Representative participants cited in the report include leading manufacturers and suppliers that serve pharmaceutical, nutraceutical, food, and oral care segments. Their profiles—summarized in the report—illustrate contrasting strategies: from export-focused commodity manufacturers to regulated‑grade specialists with premium positioning. For deal teams, these profiles enable rapid screening and prioritization of acquisition targets or sourcing partners.
Regulatory and Market Signals to Monitor in 2026
-
GRAS and pharmacopeia alignment: Ongoing FDA confirmations and Food Chemicals Codex compliance continue to underpin food and supplement adoption. This regulatory stability is a catalyst for formulators seeking clean-label calcium fortification options.
-
Pharma and infant nutrition pathways: GMP‑pharma certifications and pharmacopeial compliance open higher-margin corridors but require sustained quality systems and documentation. ISALTIS’ recent pharma-grade credentials and cosmetic listings are examples of how certification pays off in new application wins.
-
Novel use cases and claim substantiation: Regulatory acceptance of anti‑plaque claims and related oral care functions is expanding the product roadmap for manufacturers; brands should prepare dossier-level evidence for substantiated claims.
-
Raw-material volatility and supply risk: The chemistry of production concentrates risk in a handful of upstream inputs; hedging strategies and supplier qualification are essential parts of 2026 procurement planning.
Concrete Recommendations for 2026 Decision-Makers
-
For ingredient manufacturers: Fast-track GMP and pharmacopeial certifications where commercial ROI justifies the investment. Simultaneously, develop liquid 50% formulations and co‑packaging capabilities to capture incremental share in oral care and pharma channels.
-
For food and supplement brands: Use the regulatory stability to expand calcium-fortified SKUs, but require supplier audit evidence and stability data. Negotiate tiered long-term agreements to secure capacity without forfeiting price flexibility.
-
For oral care companies: Integrate clinical claim development as a front‑loaded investment. Partnerships with certified suppliers will accelerate product approvals and market launches.
-
For investors and M&A teams: Target accretive bolt-ons that add regulated-grade capabilities or geographic depth. Use the report’s valuation templates and synergies model to screen targets quickly.
-
For procurement and supply-chain leaders: Implement a dual-sourcing strategy, formalize quality scorecards, and model cost exposure to the principal chemical inputs; stress-test contracts for lead-time and quality disruption scenarios.
How PW Consulting’s Report Will Be Used by Clients in 2026
Clients are already using the full PW Consulting deliverable to support 2026 planning cycles: global ingredient suppliers deploy our procurement scenarios to set raw-material hedge parameters; CPG brands use our claim and dossier templates to accelerate product launches; private equity firms apply the M&A playbooks during diligence to validate deal theses. The report’s combination of an auditable market model, competitor scorecards, and regulatory tracker makes it a compact yet comprehensive decision tool.
Note: this press release intentionally highlights the report’s strategic value and selected macro facts. Detailed segmentation tables, proprietary price curves, region-by-region demand forecasts, and company-specific scorecards are available only within the full report and associated deliverables.
Next Steps — Accessing the Full Intelligence
Decision-makers who require the complete dataset, downloadable dashboards, and a complementary 60‑minute briefing with PW Consulting’s senior analyst team should contact our research sales desk or visit the PW Consulting reports page. The full report contains the granular regional and application-level analytics necessary to convert 2026 plans into executable programs—pricing schedules, supplier shortlists, and regulatory dossiers included.
PW Consulting remains available to conduct tailored workshops and rapid due diligence engagements to translate the report’s insights into concrete, near-term actions. In a market growing steadily at mid-single digits and accompanied by active regulatory and product innovation signals, timely access to high-fidelity intelligence will separate winners from followers in 2026.
For detailed analysis of this topic, please visit the official page: Glycerophosphoric Acid Calcium Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrocracker Market to Climb from USD 75,690 Million in 2025 to USD 110.1 Billion by 2032 at a 5.5% CAGR — Asia Pacific Leads with USD 34,566.5M
By pmarketresearch, 2026-07-13
Hydrocracker Market Outlook 2026 — Strategic Imperatives for Refiners, Licensors and Catalyst Suppliers
PW Consulting’s new Hydrocracker Market report (base year 2025) synthesizes five years of historical dynamics and a seven‑year forecast (2026–2032) into a single decision-grade playbook for executives making capital, technology and procurement choices in 2026. The global hydrocracker market reached USD 75,690 Million in 2025 and — driven by regulatory tightening, heavier crude slates and increasing crude‑to‑chemicals integration — is projected to expand at a compound annual growth rate (CAGR) of 5.5% through the forecast period, approaching USD 110,117 Million by 2032. This release is structured as an executive trailer: we demonstrate the rigor of our methods and the practical value of our findings while intentionally withholding detailed segment tables and unit‑level figures to guide readers to the full report for transaction‑ready data.
Hydrocracker Market
Why 2026 matters: an inflection point for strategy
-
Policy and product quality constraints are converging. Tightened clean‑fuel standards and maritime sulfur caps continue to force refineries to prioritize middle‑distillate yields and ultra‑low‑sulfur products — a core hydrocracker value proposition.
Hydrocracker Market -
Feedstock economics have shifted. Larger flows of heavy and extra‑heavy crudes into key refining hubs are intensifying demand for conversion technologies that maximize distillates and naphtha from low‑value residues.
Hydrocracker Market -
Integration with petrochemicals is reshaping unit economics. Crude‑to‑chemicals strategies are increasingly leveraging hydrocracking to flex production toward naphtha when margins favor petrochemical feeds.
-
Technology and supply consolidation are creating differentiated supplier profiles. Our concentration metrics show a market where leading licensors and catalyst suppliers command a meaningful but not absolute share, which creates opportunities for strategic alliances and targeted competition.
Market trajectory at a glance (what the numbers say)
Between 2020 and 2025 the hydrocracker market expanded meaningfully from its pandemic trough into a recovery driven by refinery upgrades and catalyst replacement cycles. By 2025 the global market size stood at USD 75,690 Million. Our baseline forecast for 2026 anticipates continued expansion, with the market surpassing USD 81,000 Million in the near term and following a steady path to roughly USD 110,117 Million by 2032 under the central scenario (CAGR 5.5%).
These headline figures mask important optionality. Scenario and sensitivity layers in the report show how outcomes diverge under different hydrogen supply cost curves, crude slates, and regulatory intensities — inputs every board and project sponsor must stress‑test before sanctioning large hydrocracker investments in 2026.
What the PW Consulting report delivers (practical, actionable modules)
-
Forward‑looking demand model with scenario toggles for hydrogen pricing, fuel standards and crude slate shifts — designed to translate macro drivers into plant‑level throughput and product mix implications.
-
Capex and Opex benchmarking for single‑stage, two‑stage and ebullated‑bed configurations, with unit‑type decision trees to support FEED and early‑stage FID choices.
-
Procurement playbook for licensing, EPC and catalyst sourcing, including a vendor‑selection matrix tied to reliability, conversion performance and total cost of ownership.
-
Project tracker and M&A heatmap identifying greenfield and revamp opportunities by timing and development risk — built to prioritize 12‑ and 36‑month action lists for investors and operators.
-
Operational risk register and mitigation schedules covering hydrogen security, catalyst life‑cycle management, and process integration with hydrotreating and petrochemical units.
Competitive landscape — how incumbents and challengers are positioned
The hydrocracker value chain spans licensors, catalyst manufacturers, refiners with in‑house capability and EPC/owner‑operators. Our qualitative and quantitative assessment shows distinct strategic archetypes among the sector’s most active players:
-
Licensors with integrated catalyst portfolios (e.g., Honeywell UOP, Axens, Topsoe) : These players pair proven process designs with proprietary catalysts, enabling quicker performance validation for licensors and a bundled procurement option for refiners. Their strength is in enabling high‑conversion strategies and tailored residue solutions, but pricing power varies by feed flexibility and local supply agreements.
-
Global refiners and technology owners (e.g., ExxonMobil, Chevron Lummus Global) : Operating their own large hydrocrackers provides them with experiential advantages in reliability and process know‑how. Their licensing and technology alliances are often used to monetize that know‑how, especially in markets building new conversion capacity.
-
Catalyst specialists and chemical majors (e.g., Albemarle, BASF, Johnson Matthey, Shell Catalysts & Technologies) : These firms compete on catalyst activity, selectivity and life. Contract wins are increasingly tied to total cost of ownership (TCO) metrics rather than upfront price, which changes negotiation dynamics for long‑term supply contracts.
-
Regionally scaled manufacturers (e.g., Sinopec Catalyst) : Local production capability and proximity to large integrated complexes grant them speed‑to‑market advantages in Asia and other growth regions. Strategic partnerships with licensors and EPCs accelerate project delivery.
Recent industry moves underline these dynamics. Notable project commissioning and contract awards in 2024–2025 reflect a mix of large public‑sector and private expansions: new unit startups in integrated complexes, multi‑year catalyst supply contracts, and large ebullated‑bed residue projects. These illustrate where technology selection, catalyst reliability and licensing terms become determinants of project success.
Implications for 2026 decision‑makers
-
Refiners: Prioritize flexibility. Configurations that permit product slate switching (diesel ↔ naphtha) will protect margins in volatile petrochemical pricing regimes. Validate hydrogen sourcing and storage strategies before committing to high‑conversion builds.
-
Catalyst suppliers: Shift commercial terms toward TCO and performance guarantees tied to catalyst life and regeneration cycles. Develop flexible supply agreements for emerging markets where demand timing is uncertain.
-
Licensors and EPCs: Offer modular revamp packages and accelerated FEED options to capture near‑term retrofit opportunities. Emphasize integration capability with petrochemical off‑takes when pitching to crude‑to‑chemicals projects.
-
Investors and M&A sponsors: Focus due diligence on hydrogen resilience, feedstock optionality and contractual exposure to product quality regulations. Mid‑market consolidation and strategic bolt‑ons in catalyst production are likely near‑term targets.
Operational priorities — the 90‑day to 18‑month checklist
-
Conduct a rapid hydrogen security audit: assess electrolyzer vs. SMR economics under your region’s power pricing scenarios.
-
Stress‑test any planned hydrocracker FID against low/high petrochemical margin scenarios; quantify breakeven product yields and payback horizons.
-
Lock in catalyst trials and reagent supply contracts with performance‑linked clauses to minimize lifecycle uncertainty.
-
Negotiate licensing terms that preserve optionality for mid‑cycle throughput adjustments and secondary product optimization.
The PW Consulting edge — why this report matters to 2026 strategy
Our hydrocracker study combines plant‑level engineering cost curves, vendor scorecards, and a proprietary demand model calibrated to five years of market behavior. It translates macro drivers into actionable project‑level outcomes and a prioritized pipeline by risk and timing. For executives facing 2026 FIDs or procurement cycles, the report is a practical tool to de‑risk supplier selection, refine contractual KPIs and model upside/downside margin scenarios without rebuilding models from scratch.
We have deliberately kept this announcement at the strategic level. The full PW Consulting Hydrocracker Market report contains the unit‑level data, segmentation tables, vendor scoring matrices, and project trackers necessary to execute on the recommendations above. Accessing the complete report will provide the confidential segment breakouts, plant lists and contract comparators that underpin FID‑level decisions.
Next steps
-
Download the full report and accompanying data pack from PW Consulting to obtain the detailed segmentation and project database referenced here.
-
Schedule a briefing with our Hydrocracker practice to run your project through our scenario tool and obtain a customized action plan for 2026.
Contact PW Consulting’s Hydrocracker team for an institutional briefing and to receive a sample methodology appendix demonstrating how our demand scenarios, capex benchmarks and vendor scorecards were constructed.
For detailed analysis of this topic, please visit the official page: Hydrocracker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motor Control Centers Market Poised to Expand at 6.2% CAGR, Surpassing USD 10.97 Billion by 2032
By pmarketresearch, 2026-07-13
Motor Control Centers (MCC) Market — PW Consulting Strategic Brief (2026 Outlook)
Executive snapshot
PW Consulting today publishes a strategic industry brief accompanying our comprehensive Motor Control Centers (MCC) Market report (base year 2025; historical series 2020–2025; forecast period 2026–2032). The brief distills implications that matter to executive decision-makers in 2026: capital planners, product leaders, procurement heads, system integrators and investors. Our analysis projects the global MCC market to expand at a compound annual growth rate (CAGR) of 6.2% through the forecast window, continuing the recovery and digitalization-driven expansion seen since 2020. By 2025 the market had surpassed the multi‑billion-dollar threshold and is on a trajectory to approach the low double‑digit billion range by 2032, reflecting a durable demand profile across industrial, oil & gas and infrastructure end markets.
Motor Control Centers Mcc Market
Why this report matters for 2026 strategic decisions
-
Investment timing — Understand when to accelerate CAPEX for retrofit versus incremental upgrades as digital MCCs and arc‑resistant designs move from early adoption to mainstream procurement.
Motor Control Centers Mcc Market -
Product roadmaps — Align R&D and platform strategies to prioritize embedded intelligence, cybersecurity, withdrawable architectures and renewable-integration features that buyers increasingly request.
Motor Control Centers Mcc Market -
Supply‑chain resilience — Quantify and mitigate exposure to raw material volatility and labor inflation that can erode margins and delivery lead times.
-
Regulatory compliance & safety — Prepare for tightened IEC/industry requirements that raise baseline specifications for arc‑flash protection and metering.
-
M&A and partnership playbooks — Identify accretive targets and collaboration models that rapidly expand capabilities in IoT, predictive maintenance and software-driven service revenue.
Core macro signals shaping 2026 decisions
-
Stable market expansion: Our consolidated forecast (2026–2032) at ~6.2% CAGR signals steady demand. This favors staged investment strategies rather than all‑or‑nothing large‑scale plant overhauls.
-
Digitalization alignment: Sector analysis shows a meaningful share of new MCC installs already include IoT connectivity, pushing buyers to demand real‑time diagnostics and lifecycle services from suppliers.
-
Raw material and cost pressure: Supply constraints and commodity moves — exemplified by recent copper price escalation — materially increase the cost baseline for busbars and enclosures. Procurement teams must adopt hedging and design-for-cost alternatives.
-
Standards & safety uplift: New and enforced rules for arc‑flash protection (higher kA requirements and testing) are driving specification changes that can shift total ownership economics and supplier selection.
-
Workforce economics: Rising skilled labor costs and localized wage inflation require simpler installation designs, better remote commissioning tools and improved vendor service models.
What’s inside the full PW Consulting report (practical, action-oriented)
-
Market sizing and forecast models (bottom‑up and top‑down) with scenario runs for differing macro assumptions and commodity paths.
-
Demand-driver matrices by application cluster, including retrofit cycles, OEM project pipelines and greenfield activity.
-
Technology adoption roadmap — timelines for smart MCC features, communications stacks, cybersecurity controls and predictive algorithms.
-
Cost‑to‑serve and bill‑of‑materials models highlighting sensitivity to copper, steel and electronic component pricing.
-
Supply‑chain heat maps and recommended sourcing strategies to shorten lead times and reduce single‑point supplier risk.
-
Competitive vendor scorecards and go‑to-market playbooks for different buyer segments (industrial, oil & gas, utilities), including distribution and aftermarket strategies.
-
M&A screening model and valuation comparables for targets that accelerate digital service capabilities.
-
Implementation checklists, procurement templates and a customizable dashboard for quarterly strategic reviews.
Competitive landscape — leading vendors and strategic implications
Our sector analysis profiles the market leaders and their strategic moves. The market remains moderately concentrated: the three largest vendors together account for roughly half of industry revenues, while the top five capture a clear majority. That concentration creates both stability and strategic inflection points for challengers.
-
ABB (Zurich) — Strength: integrated low‑voltage systems with evolving AI/predictive maintenance overlays. Recent trade‑show demonstrations highlight ABB’s push to fuse hardware platforms with analytics packages; buyers should expect ongoing bundling of services and longer lifecycle contracts.
-
Siemens (Munich) — Strength: motor management suites with increasing emphasis on cybersecurity and digital integration. Their recent product launches position Siemens to capture procurement that prioritizes comprehensive diagnostics and secure remote access.
-
Schneider Electric (Rueil‑Malmaison) — Strength: robust modular platforms and compliance credentials. Recent certification work signals leadership in meeting tightened regulatory specifications; Schneider is well‑positioned with customers focused on compliance and standardized architectures.
-
Eaton (Dublin) — Strength: arc‑resistant, connectivity‑ready platforms and renewables support. Their trade‑show demonstrations suggest a targeted play to integrate MCCs with distributed generation and microgrid applications.
-
Rockwell Automation, GE Vernova and Mitsubishi Electric — Each maintains differentiated positions: vertically integrated automation suites, ruggedized solutions for harsh environments, and PLC‑embedded MCCs respectively. All are advancing software and services to capture aftermarket value.
Strategic implication: incumbents will increasingly compete on software‑enabled uptime guarantees and service contracts rather than hardware alone. New entrants must either partner with incumbents or demonstrate distinctive cost or functional advantages to disrupt procurement cycles.
Regulatory, material and labor dynamics — immediate operational impacts
-
Standards enforcement: Higher arc‑flash protection requirements and updated testing protocols compel specification revisions, testing programs and potential product requalification — factors that lengthen product development timelines and influence certification planning.
-
Raw materials: Recent commodity shifts have increased the baseline cost for critical components (notably copper used in busbars), compressing gross margins unless offset by design optimizations or pricing strategies.
-
Labor: In markets where skilled electrician wages have risen materially, buyers show preference for withdrawable, modular MCC designs and remote commissioning support to reduce on‑site labor hours.
-
Industry 4.0 pull: A significant portion of new installations now include IoT connectivity from day one. This raises requirements for compatibility with OT/IT stacks and cybersecurity controls.
Recommended moves for stakeholders in 2026
-
OEMs and suppliers — Fast‑track modularization and software monetization. Prioritize platform architectures that reduce BOM sensitivity to copper and enable incremental feature activation (software licenses, remote diagnostics).
-
End‑users (operators) — Reassess retrofit timelines: where reliability is paramount, shift to service agreements that transfer uptime risk to vendors; for cost‑sensitive sites, enforce total cost of ownership metrics in RFPs.
-
System integrators — Build cybersecurity and cloud integration competencies; bundle commissioning and remote‑support services to capture long‑term margins as installations become connected.
-
Investors — Screen targets for software/service revenue potential and supply‑chain robustness. Companies with clear pathways to recurring revenue and diversified suppliers will outperform on valuation.
Methodology and transparency
The report is grounded in a mixed‑methods approach: bottom‑up reconciliations of equipment shipments and average selling prices, top‑down macro assumptions, primary interviews with OEMs and end‑users, field surveys, trade‑show intelligence, and financial statement analysis. The historical series (2020–2025) establishes demand baselines and cyclicality; multiple forecast scenarios (conservative, base, and upside) model sensitivity to commodity moves and regulatory enforcement. The public brief highlights directional conclusions; the full report contains the underlying tables, segment and regional breakdowns, and the detailed models used for scenario analysis.
How to access the full intelligence
This brief is a strategic preview designed to establish context and prioritize questions for your 2026 roadmap. The complete Motor Control Centers (MCC) Market report contains the granular segment and regional data, downloadable models, full vendor profiles and a set of executable playbooks. For executive summaries, licensing options, or to commission a tailored workshop that applies the findings to your portfolio, contact PW Consulting’s Industry Practice or visit our report landing page.
Final thought
2026 is a decision‑dense year for MCC stakeholders. Structural growth at an approximate mid‑single‑digit CAGR, a clear shift toward connected and safety‑compliant architectures, and heightened cost pressures create both risk and opportunity. Those who combine design simplification, digital services and procurement sophistication will capture the most durable margin expansion. PW Consulting’s full report equips leaders with the scenarios, supplier intelligence and implementation tools needed to convert that market trajectory into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Motor Control Centers Mcc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Steering Wheel Adjustment Motor Market to Hit USD 2,110.88 Million by 2032, Growing at a 6.19% CAGR — Asia Pacific Leads with USD 574.23 Million
By pmarketresearch, 2026-07-13
Automotive Steering Wheel Adjustment Motor Market — Strategic Outlook and 2026 Decision Playbook
PW Consulting today publishes an executive briefing extracted from our full Automotive Steering Wheel Adjustment Motor Market report (base year 2025, forecast 2026–2032). The briefing frames the strategic choices OEMs, Tier‑1 suppliers, investors and procurement leaders must make as the market moves from incremental electrification toward architecture‑level change. Our high‑level finding: the market has expanded steadily through 2020–2025 and, under our central scenario, continues to grow at a compound annual growth rate (CAGR) of 6.19% during the 2026–2032 forecast window — rising from a mid‑2020s baseline to just over USD 2.1 billion (USD Million) by 2032. This briefing explains where the value pools will be in 2026, what to watch for, and the tactical options that preserve optionality while preparing for deeper electrification and steer‑by‑wire uptake.
Automotive Steering Wheel Adjustment Motor Market
Market trajectory and why 2026 is an inflection year
Steering wheel adjustment motors — once a relatively simple electromechanical product — sit at the intersection of several powerful trends: vehicle architecture electrification, interior ergonomics and customization, advanced driver assistance and the first commercial deployments of steer‑by‑wire. These forces are changing required product attributes (torque density, NVH, crash performance, integration capability) and expanding the scope of supplier responsibilities (software, functional safety, mechatronic integration).
Automotive Steering Wheel Adjustment Motor Market
Concurrently, upstream raw material and supply dynamics are reweighting competitive economics. The emergence in 2025 of new domestic NdPr supply chains and qualifying of U.S.‑produced NdFeB magnet feedstocks has begun to change procurement calculus for compact high‑torque actuators — reducing single‑source exposure but also introducing near‑term price and qualification volatility. Regulatory work on steer‑by‑wire system safety (ISO 19725) likewise raises the bar for suppliers seeking OEM qualification for actuator and column subsystems. Taken together, these developments make 2026 a decisive year for contracting, product development prioritization, and partnership choices.
Automotive Steering Wheel Adjustment Motor Market
What the PW report delivers — actionable content for 2026 execution
- Robust market sizing and scenario forecasting: Topline market scale through 2025 and modeled trajectories under three demand scenarios for 2026–2032 (central CAGR 6.19%).
- Proven methodology: Transparent triangulation of OEM production forecasts, vehicle architecture roadmaps, and supplier shipping data — enabling traceable assumptions for procurement and strategic planning.
- Supplier benchmarking and scorecards: Commercial, technical and operational profiles for the leading global suppliers, with gap analyses against anticipated OEM requirements for 2026–2028.
- Supply‑chain risk heatmap: Raw material concentration, qualification timelines for magnet substitutes and domestic feedstock, logistics bottlenecks and mitigation options (vertical integration, multi‑sourcing, hedging constructs).
- Technology and integration playbooks: Design patterns for steer‑by‑wire and stowable column applications, safety architecture alignment with ISO 19725, and NVH/cost tradeoffs for brushed vs. brushless topologies.
- Commercial levers: Contract templates, price‑protection mechanisms against magnet price swings, and procurement timelines tied to production ramps and OEM program milestones.
- Financial models and M&A screening: Valuation sensitivities to magnet price, software/IP intensity, and customer concentration, plus indicators identifying targets for bolt‑on or capability acquisition.
Competitive landscape — concentration and strategic posture
The supplier field demonstrates moderate concentration: the top three players account for a substantial share of the market (CR3 48.5%), and the top five increase that concentration further (CR5 62.3%). This structure creates asymmetric opportunities — incumbent suppliers can leverage scale and OEM relationships, while challengers with differentiated integration capabilities or supply independence can capture premium niches.
- Johnson Electric (Hong Kong): Strength in dedicated column adjuster motors with advanced ingress/egress and smart‑cabin functions — a natural fit for EV interiors and feature‑rich memory modes. Strategic implication: favors OEMs targeting turnkey adjuster modules with software features.
- Bosch Mobility (Germany): Offers AHC‑D series adjustment drives focused on low noise, crash resilience and dual‑voltage operation — positioned for global platforms and fleet applications. Strategic implication: competition on system reliability and integration with body electronics.
- NSK (Japan): Brings proven tilt/telescopic column solutions and material engineering (impact‑absorbing plastics) that reduce weight while preserving safety performance. Strategic implication: advantageous for programs prioritizing lightweight cost‑effective columns.
- thyssenkrupp (Germany): Targets premium segments with infinitely variable electric adjustment using lightweight aluminum/magnesium — an axis play into luxury OEMs and architectures emphasizing interior flexibility. Strategic implication: premium pricing and differentiation via material engineering.
- Brose Fahrzeugteile (Germany): Integrates steering‑column adjusters within a broader electric motors portfolio — relevant where a unified motor supplier can deliver system integration economies.
- Nexteer Automotive (U.S.): Emphasizes integration for steer‑by‑wire and stowable column technologies — a strategic partner for OEMs pursuing radical interior packaging and autonomy‑enabled features.
- JTEKT (Japan): Combines steering system expertise and electronic power steering platforms with adjustment components — valuable where tuning and system interaction matter.
Recent ecosystem moves underscore momentum and risk vectors. A 2025 series production launch of a steer‑by‑wire system with stowable column capabilities signals OEM readiness to architect interiors around actuators rather than mechanical linkages. Parallel supply agreements and domestic magnet qualification in 2025 illustrate a bifurcating supply environment: increasing regional sourcing options co‑exists with near‑term price pressure and qualification lead times.
Strategic implications and recommended 2026 actions
For OEMs
- Prioritize architectural options that preserve modularity: design mechanical interfaces and electronic control boundaries such that steering adjuster modules can be sourced from multiple suppliers without reengineering the cabin production line.
- Negotiate magnet and actuator supply agreements with staged price/volume clauses to balance cost certainty and supplier qualification timelines.
- Embed ISO 19725 compliance requirements (or equivalent safety targets) into supplier qualification gates to compress program timing post‑standard publication.
For Tier‑1 suppliers
- Invest selectively in software and mechatronic integration capabilities that enable memory, ingress/egress and steer‑by‑wire functions — software differentiation reduces vulnerability to pure component commoditization.
- Pursue strategic partnering with magnet producers or consider partial vertical integration for high‑risk components where volume economics justify capital outlay.
- Expand qualification teams and reduce single‑source exposure via dual‑sourcing strategies tailored to critical magnet grades.
For investors and corporate development teams
- Screen targets that combine mechanical systems know‑how with controls/software — these assets will command multiples as OEMs consolidate sourcing for integrated actuator + control solutions.
- Monitor supplier balance sheets for vulnerabilities tied to magnet cost inflation or customer program delays — consolidation activity is likely where mid‑sized players lack scale to absorb input price shocks.
- Evaluate near‑term value creation through tuck‑ins that add qualification capacity or magnet supply resilience rather than purely revenue synergies.
Signals to watch in 2026
- Publication and OEM adoption timelines for ISO 19725 and related steer‑by‑wire guidance — a regulatory trigger that will accelerate supplier re‑engineering work.
- Magnet price trajectory and conversion capacity for NdPr‑based NdFeB grades; look for commercial availability of domestically produced high‑performance magnet feedstock and the cadence of qualifying runs.
- Volume ramps from early steer‑by‑wire production programs — these will validate the business case for stowable columns and open new interior packaging opportunities.
- Supplier contract awards and multi‑year agreements that reveal OEM preference for integrated partners versus component diversification.
How to use this intelligence in 2026 planning cycles
Use our market forecast and supplier scorecards as inputs to three core enterprise processes in 2026: (1) program sourcing strategy (who to pre‑qualify and when), (2) product development roadmaps (which actuator topologies and software features to prioritize), and (3) corporate development (M&A and strategic investments to secure supply resilience and IP). The PW report provides scenario‑based decision trees and procurement templates that map directly to calendarized OEM program milestones so teams can align contracting windows with production start‑of‑volume requirements and magnet qualification timelines.
This briefing is designed to provide a strategic lens; the full PW Consulting market report contains the granular regional, motor‑type and vehicle‑type segmentation, supplier scorecards, and financial sensitivity models required to act. If your 2026 decisions will touch procurement, sourcing, product roadmaps or corporate development in the steering/actuator space, the full dataset and playbooks will materially shorten your time to a defensible contract and reduce execution risk.
Contact PW Consulting to download the full Automotive Steering Wheel Adjustment Motor Market report and obtain access to the accompanying financial models, supplier RFP templates and scenario playbooks required to operationalize these insights.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Adjustment Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beard Shave Formula Market to Rise from USD 8,412.55 Million in 2025 to USD 11,719.43 Million by 2032, Driven by 4.85% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Beard Shave Formula Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
PW Consulting today releases a strategic industry brief on the Beard Shave Formula market that translates robust market modeling into practical, board-level guidance for 2026 decision-making. Built on primary interviews, proprietary demand modeling and a full forecast through 2032, the brief identifies where value will be captured, which risks will shape margins, and what competitive moves are most likely to matter in the next 18–36 months.
Beard Shave Formula Market
Executive snapshot: growth, structure and strategic signal
-
Market trajectory: The Beard Shave Formula market exhibits steady expansion, rising from roughly USD 6.65 billion in 2020 to an estimated USD 8.41 billion in our 2025 base year, with a compound annual growth rate of approximately 4.85% over the forecast horizon. Our modeling projects continued growth through 2032, when the market is expected to approach the low double‑digit‑billion range.
Beard Shave Formula Market -
Market structure: Concentration metrics indicate a market where leading incumbents retain meaningful scale—three‑firm concentration at the mid‑40s percent and five‑firm concentration approaching the high‑50s percent—creating an environment where national and multi‑national brands influence pricing, distribution access and innovation cadence, while specialty and indie players continue to capture premium niches.
Beard Shave Formula Market -
Report value: This brief is designed as a directional, strategic instrument for 2026 planning cycles. It surfaces high‑impact scenarios, supplier risk matrices, and go‑to‑market playbooks. Full, segment‑level datasets and model access are gated in the complete report to preserve proprietary segmentation detail and to support tailored client engagements.
What the numbers mean for corporate strategy in 2026
For C‑suite executives and GMs preparing budgets and capital allocation plans for 2026, three practical implications follow from our macro findings and industry diagnostics:
-
Prioritize margin resilience over volume chasing. Moderate, sustained growth combined with volatile natural‑oil feedstocks signals that product mix and input hedging will matter more than absolute share moves. Expect input cost swings to compress margins in premium natural formulations unless counterbalanced by pricing discipline, value‑added SKUs, or direct‑to‑consumer (DTC) strategies that recover margin.
-
Invest selectively in premiumization and formulation differentiation. Consumers are increasingly willing to pay for natural, skin‑friendly, beard‑softening preparations. Brands that can credibly demonstrate botanically derived efficacy, transparent sourcing and low irritation profiles will command price premiums—provided supply risk is actively managed.
-
Embed regulatory scenario planning into product and channel strategy. Recent and pending grooming policy updates in institutional purchasers—most notably guidance issued across U.S. defense services—create near‑term demand volatility in some institutional channels. Firms with diversified channel mixes and rapid reallocation capability will be better positioned to absorb localized shocks.
Report contents — practical, deployable modules
The full PW Consulting report goes beyond headline forecasts and offers modular deliverables intended for immediate operational use:
-
Executive decision playbook: trade‑offs for pricing, promotion cadence, and SKU rationalization under three demand scenarios for 2026–2028.
-
Channel optimization model: revenue and margin simulations across e‑commerce, mass retail, specialty grooming, and professional barber channels with recommended allocation strategies by maturity and capital intensity.
-
Supply‑chain and raw‑material risk matrix: supplier concentration mapping, critical natural‑oil exposure analysis, and contingency procurement playbooks to manage volatility in argan, jojoba and other botanical inputs.
-
Product roadmaps and formulation playbooks: ingredient prioritization (natural vs. synthetic tradeoffs), regulatory readiness checklist, and time‑to‑market sequencing for premium and value tiers.
-
M&A and partnership playbook: valuation heuristics for strategic acquisitions, licensing, and co‑developments—especially relevant given a market structure that favors scale while leaving growth pockets for niche specialists.
-
Consumer and pricing intelligence: buyer personas, elasticity testing recommendations, and sample A/B frameworks for premiumization experiments and subscription bundling.
Competition and capability: what market leaders are doing
Our competitive analysis synthesizes public positioning and capability vectors across major incumbents and prominent specialists. The market’s structure—where a handful of global players maintain material scale—creates both barriers and fertile ground for disruption.
-
Procter & Gamble (Gillette / King C. Gillette): Scale advantages in manufacturing and global retail relationships, combined with deep R&D in skin‑protective formulations, make P&G the anchor competitor. Strategic moves to watch: premium sub‑brand extensions and increased bundling in grooming kits.
-
Unilever (Dollar Shave Club and others): Strength in value‑to‑performance positioning and subscription channels. Unilever’s playbook typically emphasizes direct consumer reach and aggressive digital acquisition economics—an important model for players seeking rapid scale.
-
L’Oréal (Men Expert Barber Club): Emphasis on precision shaving and skin protection, leveraging salon‑to‑retail migration. L’Oréal is likely to double down on clinically validated claims and barber channel influence.
-
The Art of Shaving: Luxury positioning with pre‑shave oils and ritualized experiences. Opportunities for incumbents include brand partnerships or white‑labeling for premium hospitality and high‑end retailers.
-
Beiersdorf (Nivea Men) and Edgewell (Schick): Strong legacy retail placements and formulations focused on skin comfort. Their strategic advantage lies in combined mass and value offerings with stable distribution frameworks.
-
Independent and craft specialists (e.g., Honest Amish, Beardbrand, Proraso, Cremo): These brands continue to capture premium, ingredient‑led consumer segments and influence innovation—especially in botanical and artisanal formulations. They are also the likeliest targets for bolt‑on M&A as larger players seek credibility in the natural premium space.
Collectively, these competitors create a dynamic where scale, brand authenticity, and supply resilience determine who wins in premium and mainstream tiers. The report drills into capability gaps—R&D, supply diversification, DTC logistics, and clinical claim substantiation—and maps tactical responses for 2026.
Regulatory and channel dynamics shaping near‑term demand
Two non‑market forces are particularly material for 2026 planning:
-
Policy shifts in institutional purchasers. Recent guidance across U.S. defense services has tightened the rules around long‑term facial hair accommodations, producing discontinuities in institutional procurement. While the direct share of institutional demand is modest relative to consumer sales, the signaling effect—heightened scrutiny of grooming standards and medical‑exemption protocols—can alter demand for specialized shaving solutions in niche verticals.
-
Raw‑material volatility. Supply instability in key natural‑oil inputs (argan, jojoba and similar botanicals) continues to exert upward pressure on costs for natural‑ingredient formulations. Firms that proactively secure diversified suppliers, invest in ingredient substitutes, or optimize formulations for cost‑to‑performance will protect margins and preserve premium positioning.
Recommended actions for 2026 planning
-
Run a margin‑first SKU rationalization. Use SKU profitability dashboards to cull low‑margin items and reallocate shelf, digital real estate and marketing to high‑margin formulations.
-
Lock in supply and hedge input risk. Negotiate multi‑year contracts with tiered pricing, explore strategic inventory buffers for critical botanical inputs, and evaluate partial vertical integration where scale supports it.
-
Double down on DTC premium plays. Use subscription bundles and experiential content to monetize lifetime value and improve margins versus traditional retail channels.
-
Prepare regulatory playbooks. Ensure product claims, clinical substantiation and labeling are aligned to evolving institutional and consumer protection standards, especially in jurisdictions with active grooming policy changes.
-
Target bolt‑on M&A selectively. Seek specialty brands that provide access to premium ingredient portfolios, authentic branding, and engaged community followings rather than scale alone.
Why PW Consulting’s brief is a 2026 strategic asset
Our brief does more than present numbers— it translates scenarios into actionable options. Senior strategy teams will find the report useful for capital allocation conversations, for aligning R&D roadmaps with consumer willingness to pay, and for stress‑testing distribution strategies under supply‑side shocks and regulatory shifts. The underlying forecast runs through 2032, enabling multi‑year financial planning and scenario analysis tied to operational levers.
To preserve the signal value of the segmentation models and to support customized client work, we present headline macro metrics and concentration measures here while detailed segment tables, regional splits and application‑level revenue schedules are available in the full report package. Readers who require the complete datasets, downloadable models, and consulting‑grade playbooks are encouraged to access the full Beard Shave Formula Market report on PW Consulting’s research portal.
Contact and next steps
PW Consulting is scheduling briefings for corporate strategy, M&A, supply‑chain and product‑innovation teams in Q3 and Q4 2026. For corporations preparing their 2026 budgets, our analysts can provide tailored scenario workshops, margin impact simulations and a strategic roadmap aligned with your risk tolerance and growth ambitions.
Access to the full report unlocks the granular segmentation, supplier network maps, and competitive scorecards that are intentionally withheld from this briefing to preserve analytic integrity and support consultative engagements.
For detailed analysis of this topic, please visit the official page: Beard Shave Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Waste Paper Reuse Market Poised to Expand at a 5.2% CAGR
By pmarketresearch, 2026-07-13
Waste Paper Reuse Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
PW Consulting’s latest market study on Waste Paper Reuse (base year 2025) shows a market that has rebounded from the pandemic-era volatility into a structurally growing sector. The global market reached approximately USD 48.5 billion (revenue unit: Million USD) in 2025 and, under our central scenario, is forecast to expand at a compound annual growth rate (CAGR) of 5.2% through the 2026–2032 horizon. Our model highlights accelerating demand for recovered fiber across packaging, tissue and specialty paper applications, while supply-side dynamics, regulatory shifts and trade restrictions create differentiated regional opportunities and risks.
Waste Paper Reuse Market
Why this briefing matters for 2026 corporate decision-making
- Timing for capital allocation: 2026 is a pivot year — near-term capacity additions, recycling-plant upgrades and new collection mandates will determine who secures feedstock and margin expansion into the next decade.
- Policy-driven demand shifts: Extended Producer Responsibility (EPR) schemes and stricter import controls are already changing material flows and cost structures; companies that map these regulatory vectors will avoid costly sourcing shocks.
- Supply security and pricing: Raw-material cost signals and processing capacity investments are converging. Firms that establish diversified sourcing, offtake agreements and localized processing will lower volatility exposure.
- M&A and vertical moves: Low market concentration at the top makes targeted consolidation, niche bolt-ons and controlled vertical integration attractive strategies for market-share and margin capture.
What the PW Consulting report delivers (practical, decision-ready content)
- Scenario-based demand forecasts (2026–2032) with downside, base, and upside pathways tied to policy outcomes, economic growth and packaging demand curves.
- End-to-end supply chain mapping: collection systems, MRF/processing capacities, logistics choke points, and hot-spot overlays for feedstock availability.
- Risk register and regulatory matrix: state- and country-level EPR timelines, import restriction summaries (incl. contamination thresholds), permitting friction and likely near-term policy shifts.
- Commercial playbooks: procurement tactics, dynamic pricing clauses, recycled-fiber offtake frameworks, and plant-siting decision criteria informed by feedstock and energy cost modeling.
- Investment case studies: capital sizing, payback ranges and sensitivity analyses for recycling facilities, deinking lines and containerboard expansions.
- Competitive intelligence: company profiles, capability benchmarking, M&A target screening and partnership archetypes — emphasizing capabilities, network reach and integration risks.
- Data appendices and primary-source validation: longitudinal market-size data (2020–2025), price-series inputs, and methodological transparency for board-level scrutiny.
Note: this public brief intentionally omits the full regional and end-use split and the granular segment tables — these are available in the full report.
Waste Paper Reuse Market
Competitive landscape — who matters and why
The waste paper reuse market remains fragmented relative to many commodity industries. The top three players account for roughly 18.5% of the market, and the top five about 24.2%, leaving substantial room for regional leaders and agile specialists. This competitive structure creates a two-track dynamic: global-scale firms competing for integrated positions, and nimble local specialists exploiting collection and service niches.
Waste Paper Reuse Market
- Integrated global producers — International Paper, Smurfit Westrock, Mondi, Stora Enso, UPM and Sappi. These players blend upstream recovered-fiber sourcing with downstream containerboard and packaging capabilities. Their strategic advantages include vertical procurement, long-term offtakes and scale efficiencies; their risks include exposure to feedstock price swings and decarbonization capital needs.
- Recycling and MRF operators — Waste Management, Republic Services, Veolia and Sonoco Recycling. These companies control collection and initial processing, making them critical gatekeepers for quality and supply continuity. Their investment cadence in MRF capacity upgrades is a leading indicator of feedstock availability for mills and converters.
- Regional champions and 100% recycled models — Nine Dragons Paper, Pratt Industries and Cascades. These firms show how proximity to fiber sources, import strategies, and local policy alignment can underpin rapid capacity scaling and price resilience.
- Specialist differentiators — DS Smith and other corrugated specialists who combine design-for-recyclability, closed-loop programs and customer-facing takeback services to lock in recycled content premiums.
Recent corporate actions underscore strategic intent: large recycling network expansions and new recycled-fiber facilities point to firms locking supply and responding to rising sustainable packaging mandates. These moves create near-term opportunity for suppliers of sorting and decontamination equipment, and longer-term incentives for brand owners to formalize recycled-content sourcing strategies.
Market dynamics, noise and regulatory context
Several concurrent dynamics will shape operational decisions in 2026:
- Policy acceleration: Multiple US states have enacted comprehensive EPR laws for packaging; fee obligations and reporting will affect product cost structures and reverse-logistics obligations through 2025–2026. In Europe, recycling rates are high and policy levers continue to push recycled content and collection performance.
- Trade and quality controls: A number of Asian import markets enforce strict contamination thresholds for waste paper, constraining certain export flows and increasing the premium on domestically-processed, higher-quality recovered fiber.
- Price and cost signals: Recent commodity-price indicators and producer-price indices show upward pressure, driven by localized feedstock tightness and higher processing demand. These signals make short-term procurement flexibility and index-linked contracts important risk mitigants.
- Capacity investments: Leading players and major waste managers are rolling out processing capacity upgrades and new plants — an indicator that feedstock logistics and MRF throughput will be central to competitiveness.
- Recycling performance: Broad industry statistics (e.g., national recycling rates and tonnage movements) continue to improve in many geographies, but collection inefficiencies and contamination remain the dominant constraints to converting potential volumes into usable mill feedstock.
Strategic implications and recommended 2026 playbook
For corporate leaders evaluating strategy in 2026, the PW Consulting report recommends a multi-layered approach:
- Secure feedstock through diversified contracts: pursue a mix of long-term offtakes, spot purchases and partnerships with MRF operators; include quality metrics, escalators and flexibility clauses tied to EPR outcomes.
- Invest selectively in processing capacity: prioritize upgrades that reduce contamination risk (deinking, optical sorting) and lower logistics costs; prefer modular investments that can be scaled against validated demand pathways.
- Design for circularity: work with brand and packaging teams to reduce mixed-material laminates, improve recyclability and capture recycled-content premiums — this reduces end-of-life sorting burden and stabilizes feedstock quality.
- Active policy engagement: map EPR and import-rule timelines by jurisdiction, engage proactively on fee design and compliance mechanisms, and position to benefit from producer-funded collection systems.
- Pursue targeted M&A and partnerships: identify regional MRFs, deinking specialists and logistics providers for bolt-on acquisitions; target firms that close value-chain gaps and provide feedstock control without full vertical integration risk.
- Deploy data and commercial analytics: implement real-time collection-to-mill traceability, quality analytics, and dynamic pricing models to arbitrate between local and traded recovered-fiber supplies.
How PW Consulting’s report supports boardroom decisions
Boards and executive teams will find three areas where the report delivers immediate, action-ready value:
- Investment prioritization: calibrated CAPEX and opex scenarios with sensitivity to feedstock price and regulatory scenarios, enabling robust capital-allocation decisions.
- Commercial negotiation support: benchmarked contracting templates, offtake structures and risk-sharing clauses tuned for current market volatility.
- M&A playbooks: screened target lists, integration risk matrices and value-capture modelling for consolidation and capacity-securement strategies.
Call to action
This briefing is a strategic preview. The full PW Consulting Waste Paper Reuse Market report contains the detailed breakdowns, regional and end-use segmentations, company-level financials and proprietary scenario model that boards and strategy teams need to act in 2026. To access the complete dataset, segmentation tables and executable playbooks, please download the full report from our website or contact our industry desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Waste Paper Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Polyurethane Adhesive for Shoes Market Poised to Expand at a 5.85% CAGR During 2026–2032, New Report Finds
By pmarketresearch, 2026-07-13
Polyurethane Adhesive For Shoes Market — Strategic Outlook for 2026
Executive summary
PW Consulting today releases a forward-looking industry brief derived from our full Polyurethane Adhesive For Shoes Market report (base year: 2025, forecast: 2026–2032). The market has expanded steadily through the 2020–2025 period and, on the trajectory captured in our study, is forecast to grow at a compound annual growth rate (CAGR) of 5.85% over 2026–2032. This steady upward trend takes total market revenues from roughly USD 1.8 billion in 2025 toward a multi-billion dollar market by 2032.
Polyurethane Adhesive For Shoes Market
This release is designed as a strategic “trailer”: it shares high‑signal, decision‑relevant insights to inform corporate planning for 2026 while intentionally withholding granular segment tables and proprietary split analytics that are available only in the full report. The content below synthesizes the practical implications we expect to drive procurement, product, and go‑to‑market decisions next year.
Polyurethane Adhesive For Shoes Market
Market trajectory and the 2026 inflection
After a period of measured expansion between 2020 and 2025, polyurethane adhesives for footwear enter 2026 with two defining characteristics: resilient underlying demand and a shifting cost/regulatory environment. Footwear producers continue to prioritize higher-performance adhesives that support lightweight constructions, multi‑material bonding (textiles, knit uppers, engineered leathers, and technical midsoles), and faster line speeds. At the same time, raw material volatility and regulatory headwinds are reshaping supply economics.
Polyurethane Adhesive For Shoes Market
Because the market is projected to grow at a mid‑single‑digit CAGR (5.85%) through 2032, 2026 becomes a pivotal year for companies to convert market momentum into structural advantage. Firms that act early on supply risk management, targeted product innovation (low‑VOC, waterborne, bio‑sourced chemistries), and selective manufacturing or sourcing shifts will capture outsized upside as unit demand and price structures normalize.
What the PW Consulting report delivers — practical content for 2026 decisions
- Validated market sizing and a transparent forecasting model calibrated to 2025 (base year) with scenario pathways to 2032 — enabling rapid sensitivity analyses under alternative raw material and tariff scenarios.
- Demand drivers and elasticity analysis by shoe technology and manufacturing model, with actionable recommendations for product managers and sales leaders on where to prioritize portfolio investment for 2026.
- Supply‑side deep dive covering global adhesive producers, contract manufacturers, and raw material suppliers; includes risk‑indexed supplier scorecards and a procurement playbook to stabilize margins under MDI/TDI price volatility.
- Regulatory and sustainability matrix mapping regional policy trajectories (REACH, low‑VOC mandates, Green Deal implications) to product roadmaps and compliance timelines.
- Technology trends and adoption curves — waterborne and hot‑melt polyurethane systems, thermoplastic PU innovations, and bio‑based polyol integration — paired with an IP/partnering decision framework for R&D and licensing teams.
- Commercial playbook for 2026: pricing tactics, co‑development partnership structures with OEMs and brands, and a channel strategy that balances direct sales with regional distributors.
- 50+ company profiles, strategic SWOTs, and M&A/partnership scenarios built from primary interviews with manufacturers, formulators, brand R&D heads, and procurement leads.
Competitive landscape — who matters and why
The market is characterised by a mixed ecosystem of large chemical suppliers, global adhesives specialists, and regional formulators. In the short list of strategic suppliers, we examine how each player is positioning for the next cycle:
- Henkel AG & Co. KGaA (Düsseldorf) — Focused on polyurethane hot melt (PURHM) and waterborne adhesives for athletic footwear, Henkel’s value proposition centers on line productivity gains (reduced process steps and energy), and bonding solutions for complex substrate combinations. Their recent product emphasis reflects a pragmatic approach to lowering manufacturing cost per pair while improving durability.
- H.B. Fuller Company (St. Paul) — A longstanding partner in footwear assembly, H.B. Fuller competes on a combination of performance adhesives and broad technical service capabilities. The company is a likely co‑development partner for brands seeking custom formulations that balance adhesion with process window robustness.
- BASF SE (Ludwigshafen) — Through waterborne polyurethane dispersions, BASF targets formulators and OEMs seeking adaptable chemistry platforms. Their dispersion technology is particularly relevant for new footwear materials used in lightweight and breathable constructions.
- Covestro AG (Leverkusen) — A critical upstream supplier of TPU and other polyurethane raw materials; Covestro’s offerings are foundational for downstream adhesive formulators, especially in thermoplastic and powder‑based systems.
- Arkema/Bostik (Colombes) — Positioned on sustainable bonding solutions, Bostik is active in the shift to low‑VOC and water‑based adhesives and is engaged with footwear brands emphasizing eco‑claims and supply chain transparency.
- Taiwan and China‑based formulators (e.g., NANPAO, TPUCO, GRECO, Xuchuan, Sinograce) — These regional specialists combine deep footwear application know‑how with proximity to major OEM clusters. Several have shown early wins on hydrolysis resistance and green certifications important to brand buyers.
- Ingredient and specialty suppliers (Lubrizol, etc.) — Provide TPU and bio‑sourced feedstocks for hot melt and solvent systems; portfolio expansions into bio‑based TPUs and performance additives are creating new routes to lower carbon intensity adhesives.
Recent product and positioning moves — from Henkel’s March 2025 emphasis on labor and energy reductions to Lubrizol’s introduction of bio‑sourced TPU grades — illustrate two parallel competitive pathways: performance differentiation (durability, bonding of mixed substrates) and sustainability differentiation (low VOCs, bio‑content). Both pathways are commercially relevant for 2026.
Market dynamics and near‑term risks
- Raw material volatility: MDI and TDI price swings tied to crude cycles continue to transmit through to adhesive formulators. 2026 procurement strategies must include index‑linked contracts, multi‑sourcing, and pass‑through pricing clauses to protect margins.
- Regulatory and green procurement pressure: Stricter emissions and chemical policies are accelerating conversion from solvent‑based systems to waterborne and low‑VOC technologies. Brands are simultaneously demanding lower carbon footprints, accelerating adoption of bio‑based polyols where performance permits.
- Trade and tariff shifts: Post‑2025 tariff changes on certain polyols and isocyanates have already increased landed costs in some regions. Manufacturers with flexible sourcing or regional formulation centers will fare better in 2026.
- Consolidation and supplier concentration: The market is supplied by a mix of global majors and strong regional players. Expect continued tie‑ups, co‑development partnerships, and selective M&A as firms seek scale in R&D and distribution.
Strategic playbook for 2026 — what leading companies should do now
We translate our analysis into five executable moves companies can implement in 2026 to secure competitive advantage:
- Hedge and diversify raw material exposure: Negotiate multi‑year supply agreements with price collars, create alternative formulations tolerant to polyol seed variations, and qualify secondary suppliers in low‑tariff jurisdictions.
- Prioritize waterborne and low‑VOC investments: Accelerate commercialization of waterborne and thermoplastic PU systems for segments where brands demand sustainability claims, while protecting premium performance niches with targeted solvent‑reduction roadmaps.
- Deploy modular manufacturing footprints: Shift towards smaller, flexible formulation hubs near major OEM clusters to reduce landed costs and improve responsiveness to design changes.
- Lock strategic OEM partnerships: Offer co‑development programs that bundle adhesive chemistry with application engineering and in‑line process consulting — a high barrier to switching for brand partners.
- Design a disciplined M&A and partnership approach: Target regional formulators with strong application know‑how or specialty tech (hydrolysis resistance, fast‑curing PURHM) to accelerate time‑to‑market in adjacent geographies.
How procurement, R&D and commercial teams should use the report
Procurement can use our supply‑risk indices and pricing scenarios to rework supplier contracts and build contingency inventories. R&D teams will find the technology adoption curves and regulatory timelines essential for prioritizing formulation roadmaps. Commercial teams can deploy the go‑to‑market playbook to structure multi‑year co‑development agreements and value‑based pricing models for brand customers.
Why PW Consulting’s analysis matters for 2026
Our methodology combines primary interviews across the footwear supply chain, bottom‑up build‑ups of adhesive demand per shoe type, and supplier‑level cost modeling that incorporates raw material price paths and tariff scenarios. The result is a pragmatic, executable set of insights that translate a mid‑single‑digit CAGR outlook into concrete operational and commercial actions. For organizations planning capital, R&D, procurement, or M&A moves in 2026, the difference between acting early or lagging behind will be decided on supply resilience and the ability to deliver validated sustainable chemistries at scale.
Accessing the full intelligence
This release highlights strategic takeaways and omitted granular splits by region, type, and application that are available in the full PW Consulting Polyurethane Adhesive For Shoes Market report. The complete report includes the proprietary segment matrices, supplier scorecards, and scenario models necessary to operationalize the 2026 playbook. Contact PW Consulting to obtain the full dataset and a tailored briefing for your business unit.
For detailed analysis of this topic, please visit the official page: Polyurethane Adhesive For Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com