

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Waste Paper Reuse Market Poised to Expand at a 5.2% CAGR

Waste Paper Reuse Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
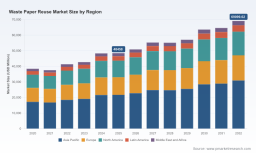
PW Consulting’s latest market study on Waste Paper Reuse (base year 2025) shows a market that has rebounded from the pandemic-era volatility into a structurally growing sector. The global market reached approximately USD 48.5 billion (revenue unit: Million USD) in 2025 and, under our central scenario, is forecast to expand at a compound annual growth rate (CAGR) of 5.2% through the 2026–2032 horizon. Our model highlights accelerating demand for recovered fiber across packaging, tissue and specialty paper applications, while supply-side dynamics, regulatory shifts and trade restrictions create differentiated regional opportunities and risks.
Waste Paper Reuse Market
Why this briefing matters for 2026 corporate decision-making
- Timing for capital allocation: 2026 is a pivot year — near-term capacity additions, recycling-plant upgrades and new collection mandates will determine who secures feedstock and margin expansion into the next decade.
- Policy-driven demand shifts: Extended Producer Responsibility (EPR) schemes and stricter import controls are already changing material flows and cost structures; companies that map these regulatory vectors will avoid costly sourcing shocks.
- Supply security and pricing: Raw-material cost signals and processing capacity investments are converging. Firms that establish diversified sourcing, offtake agreements and localized processing will lower volatility exposure.
- M&A and vertical moves: Low market concentration at the top makes targeted consolidation, niche bolt-ons and controlled vertical integration attractive strategies for market-share and margin capture.
What the PW Consulting report delivers (practical, decision-ready content)
- Scenario-based demand forecasts (2026–2032) with downside, base, and upside pathways tied to policy outcomes, economic growth and packaging demand curves.
- End-to-end supply chain mapping: collection systems, MRF/processing capacities, logistics choke points, and hot-spot overlays for feedstock availability.
- Risk register and regulatory matrix: state- and country-level EPR timelines, import restriction summaries (incl. contamination thresholds), permitting friction and likely near-term policy shifts.
- Commercial playbooks: procurement tactics, dynamic pricing clauses, recycled-fiber offtake frameworks, and plant-siting decision criteria informed by feedstock and energy cost modeling.
- Investment case studies: capital sizing, payback ranges and sensitivity analyses for recycling facilities, deinking lines and containerboard expansions.
- Competitive intelligence: company profiles, capability benchmarking, M&A target screening and partnership archetypes — emphasizing capabilities, network reach and integration risks.
- Data appendices and primary-source validation: longitudinal market-size data (2020–2025), price-series inputs, and methodological transparency for board-level scrutiny.
Note: this public brief intentionally omits the full regional and end-use split and the granular segment tables — these are available in the full report.
Waste Paper Reuse Market
Competitive landscape — who matters and why
The waste paper reuse market remains fragmented relative to many commodity industries. The top three players account for roughly 18.5% of the market, and the top five about 24.2%, leaving substantial room for regional leaders and agile specialists. This competitive structure creates a two-track dynamic: global-scale firms competing for integrated positions, and nimble local specialists exploiting collection and service niches.
Waste Paper Reuse Market
- Integrated global producers — International Paper, Smurfit Westrock, Mondi, Stora Enso, UPM and Sappi. These players blend upstream recovered-fiber sourcing with downstream containerboard and packaging capabilities. Their strategic advantages include vertical procurement, long-term offtakes and scale efficiencies; their risks include exposure to feedstock price swings and decarbonization capital needs.
- Recycling and MRF operators — Waste Management, Republic Services, Veolia and Sonoco Recycling. These companies control collection and initial processing, making them critical gatekeepers for quality and supply continuity. Their investment cadence in MRF capacity upgrades is a leading indicator of feedstock availability for mills and converters.
- Regional champions and 100% recycled models — Nine Dragons Paper, Pratt Industries and Cascades. These firms show how proximity to fiber sources, import strategies, and local policy alignment can underpin rapid capacity scaling and price resilience.
- Specialist differentiators — DS Smith and other corrugated specialists who combine design-for-recyclability, closed-loop programs and customer-facing takeback services to lock in recycled content premiums.
Recent corporate actions underscore strategic intent: large recycling network expansions and new recycled-fiber facilities point to firms locking supply and responding to rising sustainable packaging mandates. These moves create near-term opportunity for suppliers of sorting and decontamination equipment, and longer-term incentives for brand owners to formalize recycled-content sourcing strategies.
Market dynamics, noise and regulatory context
Several concurrent dynamics will shape operational decisions in 2026:
- Policy acceleration: Multiple US states have enacted comprehensive EPR laws for packaging; fee obligations and reporting will affect product cost structures and reverse-logistics obligations through 2025–2026. In Europe, recycling rates are high and policy levers continue to push recycled content and collection performance.
- Trade and quality controls: A number of Asian import markets enforce strict contamination thresholds for waste paper, constraining certain export flows and increasing the premium on domestically-processed, higher-quality recovered fiber.
- Price and cost signals: Recent commodity-price indicators and producer-price indices show upward pressure, driven by localized feedstock tightness and higher processing demand. These signals make short-term procurement flexibility and index-linked contracts important risk mitigants.
- Capacity investments: Leading players and major waste managers are rolling out processing capacity upgrades and new plants — an indicator that feedstock logistics and MRF throughput will be central to competitiveness.
- Recycling performance: Broad industry statistics (e.g., national recycling rates and tonnage movements) continue to improve in many geographies, but collection inefficiencies and contamination remain the dominant constraints to converting potential volumes into usable mill feedstock.
Strategic implications and recommended 2026 playbook
For corporate leaders evaluating strategy in 2026, the PW Consulting report recommends a multi-layered approach:
- Secure feedstock through diversified contracts: pursue a mix of long-term offtakes, spot purchases and partnerships with MRF operators; include quality metrics, escalators and flexibility clauses tied to EPR outcomes.
- Invest selectively in processing capacity: prioritize upgrades that reduce contamination risk (deinking, optical sorting) and lower logistics costs; prefer modular investments that can be scaled against validated demand pathways.
- Design for circularity: work with brand and packaging teams to reduce mixed-material laminates, improve recyclability and capture recycled-content premiums — this reduces end-of-life sorting burden and stabilizes feedstock quality.
- Active policy engagement: map EPR and import-rule timelines by jurisdiction, engage proactively on fee design and compliance mechanisms, and position to benefit from producer-funded collection systems.
- Pursue targeted M&A and partnerships: identify regional MRFs, deinking specialists and logistics providers for bolt-on acquisitions; target firms that close value-chain gaps and provide feedstock control without full vertical integration risk.
- Deploy data and commercial analytics: implement real-time collection-to-mill traceability, quality analytics, and dynamic pricing models to arbitrate between local and traded recovered-fiber supplies.
How PW Consulting’s report supports boardroom decisions
Boards and executive teams will find three areas where the report delivers immediate, action-ready value:
- Investment prioritization: calibrated CAPEX and opex scenarios with sensitivity to feedstock price and regulatory scenarios, enabling robust capital-allocation decisions.
- Commercial negotiation support: benchmarked contracting templates, offtake structures and risk-sharing clauses tuned for current market volatility.
- M&A playbooks: screened target lists, integration risk matrices and value-capture modelling for consolidation and capacity-securement strategies.
Call to action
This briefing is a strategic preview. The full PW Consulting Waste Paper Reuse Market report contains the detailed breakdowns, regional and end-use segmentations, company-level financials and proprietary scenario model that boards and strategy teams need to act in 2026. To access the complete dataset, segmentation tables and executable playbooks, please download the full report from our website or contact our industry desk for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Waste Paper Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com