

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrocracker Market to Climb from USD 75,690 Million in 2025 to USD 110.1 Billion by 2032 at a 5.5% CAGR — Asia Pacific Leads with USD 34,566.5M

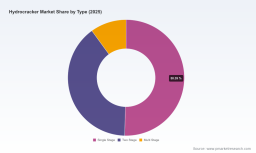
Hydrocracker Market Outlook 2026 — Strategic Imperatives for Refiners, Licensors and Catalyst Suppliers
PW Consulting’s new Hydrocracker Market report (base year 2025) synthesizes five years of historical dynamics and a seven‑year forecast (2026–2032) into a single decision-grade playbook for executives making capital, technology and procurement choices in 2026. The global hydrocracker market reached USD 75,690 Million in 2025 and — driven by regulatory tightening, heavier crude slates and increasing crude‑to‑chemicals integration — is projected to expand at a compound annual growth rate (CAGR) of 5.5% through the forecast period, approaching USD 110,117 Million by 2032. This release is structured as an executive trailer: we demonstrate the rigor of our methods and the practical value of our findings while intentionally withholding detailed segment tables and unit‑level figures to guide readers to the full report for transaction‑ready data.
Hydrocracker Market
Why 2026 matters: an inflection point for strategy
-
Policy and product quality constraints are converging. Tightened clean‑fuel standards and maritime sulfur caps continue to force refineries to prioritize middle‑distillate yields and ultra‑low‑sulfur products — a core hydrocracker value proposition.
Hydrocracker Market -
Feedstock economics have shifted. Larger flows of heavy and extra‑heavy crudes into key refining hubs are intensifying demand for conversion technologies that maximize distillates and naphtha from low‑value residues.
Hydrocracker Market -
Integration with petrochemicals is reshaping unit economics. Crude‑to‑chemicals strategies are increasingly leveraging hydrocracking to flex production toward naphtha when margins favor petrochemical feeds.
-
Technology and supply consolidation are creating differentiated supplier profiles. Our concentration metrics show a market where leading licensors and catalyst suppliers command a meaningful but not absolute share, which creates opportunities for strategic alliances and targeted competition.
Market trajectory at a glance (what the numbers say)
Between 2020 and 2025 the hydrocracker market expanded meaningfully from its pandemic trough into a recovery driven by refinery upgrades and catalyst replacement cycles. By 2025 the global market size stood at USD 75,690 Million. Our baseline forecast for 2026 anticipates continued expansion, with the market surpassing USD 81,000 Million in the near term and following a steady path to roughly USD 110,117 Million by 2032 under the central scenario (CAGR 5.5%).
These headline figures mask important optionality. Scenario and sensitivity layers in the report show how outcomes diverge under different hydrogen supply cost curves, crude slates, and regulatory intensities — inputs every board and project sponsor must stress‑test before sanctioning large hydrocracker investments in 2026.
What the PW Consulting report delivers (practical, actionable modules)
-
Forward‑looking demand model with scenario toggles for hydrogen pricing, fuel standards and crude slate shifts — designed to translate macro drivers into plant‑level throughput and product mix implications.
-
Capex and Opex benchmarking for single‑stage, two‑stage and ebullated‑bed configurations, with unit‑type decision trees to support FEED and early‑stage FID choices.
-
Procurement playbook for licensing, EPC and catalyst sourcing, including a vendor‑selection matrix tied to reliability, conversion performance and total cost of ownership.
-
Project tracker and M&A heatmap identifying greenfield and revamp opportunities by timing and development risk — built to prioritize 12‑ and 36‑month action lists for investors and operators.
-
Operational risk register and mitigation schedules covering hydrogen security, catalyst life‑cycle management, and process integration with hydrotreating and petrochemical units.
Competitive landscape — how incumbents and challengers are positioned
The hydrocracker value chain spans licensors, catalyst manufacturers, refiners with in‑house capability and EPC/owner‑operators. Our qualitative and quantitative assessment shows distinct strategic archetypes among the sector’s most active players:
-
Licensors with integrated catalyst portfolios (e.g., Honeywell UOP, Axens, Topsoe) : These players pair proven process designs with proprietary catalysts, enabling quicker performance validation for licensors and a bundled procurement option for refiners. Their strength is in enabling high‑conversion strategies and tailored residue solutions, but pricing power varies by feed flexibility and local supply agreements.
-
Global refiners and technology owners (e.g., ExxonMobil, Chevron Lummus Global) : Operating their own large hydrocrackers provides them with experiential advantages in reliability and process know‑how. Their licensing and technology alliances are often used to monetize that know‑how, especially in markets building new conversion capacity.
-
Catalyst specialists and chemical majors (e.g., Albemarle, BASF, Johnson Matthey, Shell Catalysts & Technologies) : These firms compete on catalyst activity, selectivity and life. Contract wins are increasingly tied to total cost of ownership (TCO) metrics rather than upfront price, which changes negotiation dynamics for long‑term supply contracts.
-
Regionally scaled manufacturers (e.g., Sinopec Catalyst) : Local production capability and proximity to large integrated complexes grant them speed‑to‑market advantages in Asia and other growth regions. Strategic partnerships with licensors and EPCs accelerate project delivery.
Recent industry moves underline these dynamics. Notable project commissioning and contract awards in 2024–2025 reflect a mix of large public‑sector and private expansions: new unit startups in integrated complexes, multi‑year catalyst supply contracts, and large ebullated‑bed residue projects. These illustrate where technology selection, catalyst reliability and licensing terms become determinants of project success.
Implications for 2026 decision‑makers
-
Refiners: Prioritize flexibility. Configurations that permit product slate switching (diesel ↔ naphtha) will protect margins in volatile petrochemical pricing regimes. Validate hydrogen sourcing and storage strategies before committing to high‑conversion builds.
-
Catalyst suppliers: Shift commercial terms toward TCO and performance guarantees tied to catalyst life and regeneration cycles. Develop flexible supply agreements for emerging markets where demand timing is uncertain.
-
Licensors and EPCs: Offer modular revamp packages and accelerated FEED options to capture near‑term retrofit opportunities. Emphasize integration capability with petrochemical off‑takes when pitching to crude‑to‑chemicals projects.
-
Investors and M&A sponsors: Focus due diligence on hydrogen resilience, feedstock optionality and contractual exposure to product quality regulations. Mid‑market consolidation and strategic bolt‑ons in catalyst production are likely near‑term targets.
Operational priorities — the 90‑day to 18‑month checklist
-
Conduct a rapid hydrogen security audit: assess electrolyzer vs. SMR economics under your region’s power pricing scenarios.
-
Stress‑test any planned hydrocracker FID against low/high petrochemical margin scenarios; quantify breakeven product yields and payback horizons.
-
Lock in catalyst trials and reagent supply contracts with performance‑linked clauses to minimize lifecycle uncertainty.
-
Negotiate licensing terms that preserve optionality for mid‑cycle throughput adjustments and secondary product optimization.
The PW Consulting edge — why this report matters to 2026 strategy
Our hydrocracker study combines plant‑level engineering cost curves, vendor scorecards, and a proprietary demand model calibrated to five years of market behavior. It translates macro drivers into actionable project‑level outcomes and a prioritized pipeline by risk and timing. For executives facing 2026 FIDs or procurement cycles, the report is a practical tool to de‑risk supplier selection, refine contractual KPIs and model upside/downside margin scenarios without rebuilding models from scratch.
We have deliberately kept this announcement at the strategic level. The full PW Consulting Hydrocracker Market report contains the unit‑level data, segmentation tables, vendor scoring matrices, and project trackers necessary to execute on the recommendations above. Accessing the complete report will provide the confidential segment breakouts, plant lists and contract comparators that underpin FID‑level decisions.
Next steps
-
Download the full report and accompanying data pack from PW Consulting to obtain the detailed segmentation and project database referenced here.
-
Schedule a briefing with our Hydrocracker practice to run your project through our scenario tool and obtain a customized action plan for 2026.
Contact PW Consulting’s Hydrocracker team for an institutional briefing and to receive a sample methodology appendix demonstrating how our demand scenarios, capex benchmarks and vendor scorecards were constructed.
For detailed analysis of this topic, please visit the official page: Hydrocracker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com