

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
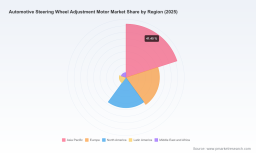
PW Consulting: Automotive Steering Wheel Adjustment Motor Market to Hit USD 2,110.88 Million by 2032, Growing at a 6.19% CAGR — Asia Pacific Leads with USD 574.23 Million

Automotive Steering Wheel Adjustment Motor Market — Strategic Outlook and 2026 Decision Playbook
PW Consulting today publishes an executive briefing extracted from our full Automotive Steering Wheel Adjustment Motor Market report (base year 2025, forecast 2026–2032). The briefing frames the strategic choices OEMs, Tier‑1 suppliers, investors and procurement leaders must make as the market moves from incremental electrification toward architecture‑level change. Our high‑level finding: the market has expanded steadily through 2020–2025 and, under our central scenario, continues to grow at a compound annual growth rate (CAGR) of 6.19% during the 2026–2032 forecast window — rising from a mid‑2020s baseline to just over USD 2.1 billion (USD Million) by 2032. This briefing explains where the value pools will be in 2026, what to watch for, and the tactical options that preserve optionality while preparing for deeper electrification and steer‑by‑wire uptake.
Automotive Steering Wheel Adjustment Motor Market
Market trajectory and why 2026 is an inflection year
Steering wheel adjustment motors — once a relatively simple electromechanical product — sit at the intersection of several powerful trends: vehicle architecture electrification, interior ergonomics and customization, advanced driver assistance and the first commercial deployments of steer‑by‑wire. These forces are changing required product attributes (torque density, NVH, crash performance, integration capability) and expanding the scope of supplier responsibilities (software, functional safety, mechatronic integration).
Automotive Steering Wheel Adjustment Motor Market
Concurrently, upstream raw material and supply dynamics are reweighting competitive economics. The emergence in 2025 of new domestic NdPr supply chains and qualifying of U.S.‑produced NdFeB magnet feedstocks has begun to change procurement calculus for compact high‑torque actuators — reducing single‑source exposure but also introducing near‑term price and qualification volatility. Regulatory work on steer‑by‑wire system safety (ISO 19725) likewise raises the bar for suppliers seeking OEM qualification for actuator and column subsystems. Taken together, these developments make 2026 a decisive year for contracting, product development prioritization, and partnership choices.
Automotive Steering Wheel Adjustment Motor Market
What the PW report delivers — actionable content for 2026 execution
- Robust market sizing and scenario forecasting: Topline market scale through 2025 and modeled trajectories under three demand scenarios for 2026–2032 (central CAGR 6.19%).
- Proven methodology: Transparent triangulation of OEM production forecasts, vehicle architecture roadmaps, and supplier shipping data — enabling traceable assumptions for procurement and strategic planning.
- Supplier benchmarking and scorecards: Commercial, technical and operational profiles for the leading global suppliers, with gap analyses against anticipated OEM requirements for 2026–2028.
- Supply‑chain risk heatmap: Raw material concentration, qualification timelines for magnet substitutes and domestic feedstock, logistics bottlenecks and mitigation options (vertical integration, multi‑sourcing, hedging constructs).
- Technology and integration playbooks: Design patterns for steer‑by‑wire and stowable column applications, safety architecture alignment with ISO 19725, and NVH/cost tradeoffs for brushed vs. brushless topologies.
- Commercial levers: Contract templates, price‑protection mechanisms against magnet price swings, and procurement timelines tied to production ramps and OEM program milestones.
- Financial models and M&A screening: Valuation sensitivities to magnet price, software/IP intensity, and customer concentration, plus indicators identifying targets for bolt‑on or capability acquisition.
Competitive landscape — concentration and strategic posture
The supplier field demonstrates moderate concentration: the top three players account for a substantial share of the market (CR3 48.5%), and the top five increase that concentration further (CR5 62.3%). This structure creates asymmetric opportunities — incumbent suppliers can leverage scale and OEM relationships, while challengers with differentiated integration capabilities or supply independence can capture premium niches.
- Johnson Electric (Hong Kong): Strength in dedicated column adjuster motors with advanced ingress/egress and smart‑cabin functions — a natural fit for EV interiors and feature‑rich memory modes. Strategic implication: favors OEMs targeting turnkey adjuster modules with software features.
- Bosch Mobility (Germany): Offers AHC‑D series adjustment drives focused on low noise, crash resilience and dual‑voltage operation — positioned for global platforms and fleet applications. Strategic implication: competition on system reliability and integration with body electronics.
- NSK (Japan): Brings proven tilt/telescopic column solutions and material engineering (impact‑absorbing plastics) that reduce weight while preserving safety performance. Strategic implication: advantageous for programs prioritizing lightweight cost‑effective columns.
- thyssenkrupp (Germany): Targets premium segments with infinitely variable electric adjustment using lightweight aluminum/magnesium — an axis play into luxury OEMs and architectures emphasizing interior flexibility. Strategic implication: premium pricing and differentiation via material engineering.
- Brose Fahrzeugteile (Germany): Integrates steering‑column adjusters within a broader electric motors portfolio — relevant where a unified motor supplier can deliver system integration economies.
- Nexteer Automotive (U.S.): Emphasizes integration for steer‑by‑wire and stowable column technologies — a strategic partner for OEMs pursuing radical interior packaging and autonomy‑enabled features.
- JTEKT (Japan): Combines steering system expertise and electronic power steering platforms with adjustment components — valuable where tuning and system interaction matter.
Recent ecosystem moves underscore momentum and risk vectors. A 2025 series production launch of a steer‑by‑wire system with stowable column capabilities signals OEM readiness to architect interiors around actuators rather than mechanical linkages. Parallel supply agreements and domestic magnet qualification in 2025 illustrate a bifurcating supply environment: increasing regional sourcing options co‑exists with near‑term price pressure and qualification lead times.
Strategic implications and recommended 2026 actions
For OEMs
- Prioritize architectural options that preserve modularity: design mechanical interfaces and electronic control boundaries such that steering adjuster modules can be sourced from multiple suppliers without reengineering the cabin production line.
- Negotiate magnet and actuator supply agreements with staged price/volume clauses to balance cost certainty and supplier qualification timelines.
- Embed ISO 19725 compliance requirements (or equivalent safety targets) into supplier qualification gates to compress program timing post‑standard publication.
For Tier‑1 suppliers
- Invest selectively in software and mechatronic integration capabilities that enable memory, ingress/egress and steer‑by‑wire functions — software differentiation reduces vulnerability to pure component commoditization.
- Pursue strategic partnering with magnet producers or consider partial vertical integration for high‑risk components where volume economics justify capital outlay.
- Expand qualification teams and reduce single‑source exposure via dual‑sourcing strategies tailored to critical magnet grades.
For investors and corporate development teams
- Screen targets that combine mechanical systems know‑how with controls/software — these assets will command multiples as OEMs consolidate sourcing for integrated actuator + control solutions.
- Monitor supplier balance sheets for vulnerabilities tied to magnet cost inflation or customer program delays — consolidation activity is likely where mid‑sized players lack scale to absorb input price shocks.
- Evaluate near‑term value creation through tuck‑ins that add qualification capacity or magnet supply resilience rather than purely revenue synergies.
Signals to watch in 2026
- Publication and OEM adoption timelines for ISO 19725 and related steer‑by‑wire guidance — a regulatory trigger that will accelerate supplier re‑engineering work.
- Magnet price trajectory and conversion capacity for NdPr‑based NdFeB grades; look for commercial availability of domestically produced high‑performance magnet feedstock and the cadence of qualifying runs.
- Volume ramps from early steer‑by‑wire production programs — these will validate the business case for stowable columns and open new interior packaging opportunities.
- Supplier contract awards and multi‑year agreements that reveal OEM preference for integrated partners versus component diversification.
How to use this intelligence in 2026 planning cycles
Use our market forecast and supplier scorecards as inputs to three core enterprise processes in 2026: (1) program sourcing strategy (who to pre‑qualify and when), (2) product development roadmaps (which actuator topologies and software features to prioritize), and (3) corporate development (M&A and strategic investments to secure supply resilience and IP). The PW report provides scenario‑based decision trees and procurement templates that map directly to calendarized OEM program milestones so teams can align contracting windows with production start‑of‑volume requirements and magnet qualification timelines.
This briefing is designed to provide a strategic lens; the full PW Consulting market report contains the granular regional, motor‑type and vehicle‑type segmentation, supplier scorecards, and financial sensitivity models required to act. If your 2026 decisions will touch procurement, sourcing, product roadmaps or corporate development in the steering/actuator space, the full dataset and playbooks will materially shorten your time to a defensible contract and reduce execution risk.
Contact PW Consulting to download the full Automotive Steering Wheel Adjustment Motor Market report and obtain access to the accompanying financial models, supplier RFP templates and scenario playbooks required to operationalize these insights.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Adjustment Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com