

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Polyurethane Adhesive for Shoes Market Poised to Expand at a 5.85% CAGR During 2026–2032, New Report Finds

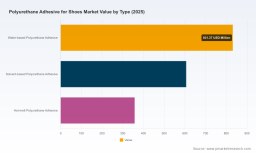
Polyurethane Adhesive For Shoes Market — Strategic Outlook for 2026
Executive summary
PW Consulting today releases a forward-looking industry brief derived from our full Polyurethane Adhesive For Shoes Market report (base year: 2025, forecast: 2026–2032). The market has expanded steadily through the 2020–2025 period and, on the trajectory captured in our study, is forecast to grow at a compound annual growth rate (CAGR) of 5.85% over 2026–2032. This steady upward trend takes total market revenues from roughly USD 1.8 billion in 2025 toward a multi-billion dollar market by 2032.
Polyurethane Adhesive For Shoes Market
This release is designed as a strategic “trailer”: it shares high‑signal, decision‑relevant insights to inform corporate planning for 2026 while intentionally withholding granular segment tables and proprietary split analytics that are available only in the full report. The content below synthesizes the practical implications we expect to drive procurement, product, and go‑to‑market decisions next year.
Polyurethane Adhesive For Shoes Market
Market trajectory and the 2026 inflection
After a period of measured expansion between 2020 and 2025, polyurethane adhesives for footwear enter 2026 with two defining characteristics: resilient underlying demand and a shifting cost/regulatory environment. Footwear producers continue to prioritize higher-performance adhesives that support lightweight constructions, multi‑material bonding (textiles, knit uppers, engineered leathers, and technical midsoles), and faster line speeds. At the same time, raw material volatility and regulatory headwinds are reshaping supply economics.
Polyurethane Adhesive For Shoes Market
Because the market is projected to grow at a mid‑single‑digit CAGR (5.85%) through 2032, 2026 becomes a pivotal year for companies to convert market momentum into structural advantage. Firms that act early on supply risk management, targeted product innovation (low‑VOC, waterborne, bio‑sourced chemistries), and selective manufacturing or sourcing shifts will capture outsized upside as unit demand and price structures normalize.
What the PW Consulting report delivers — practical content for 2026 decisions
- Validated market sizing and a transparent forecasting model calibrated to 2025 (base year) with scenario pathways to 2032 — enabling rapid sensitivity analyses under alternative raw material and tariff scenarios.
- Demand drivers and elasticity analysis by shoe technology and manufacturing model, with actionable recommendations for product managers and sales leaders on where to prioritize portfolio investment for 2026.
- Supply‑side deep dive covering global adhesive producers, contract manufacturers, and raw material suppliers; includes risk‑indexed supplier scorecards and a procurement playbook to stabilize margins under MDI/TDI price volatility.
- Regulatory and sustainability matrix mapping regional policy trajectories (REACH, low‑VOC mandates, Green Deal implications) to product roadmaps and compliance timelines.
- Technology trends and adoption curves — waterborne and hot‑melt polyurethane systems, thermoplastic PU innovations, and bio‑based polyol integration — paired with an IP/partnering decision framework for R&D and licensing teams.
- Commercial playbook for 2026: pricing tactics, co‑development partnership structures with OEMs and brands, and a channel strategy that balances direct sales with regional distributors.
- 50+ company profiles, strategic SWOTs, and M&A/partnership scenarios built from primary interviews with manufacturers, formulators, brand R&D heads, and procurement leads.
Competitive landscape — who matters and why
The market is characterised by a mixed ecosystem of large chemical suppliers, global adhesives specialists, and regional formulators. In the short list of strategic suppliers, we examine how each player is positioning for the next cycle:
- Henkel AG & Co. KGaA (Düsseldorf) — Focused on polyurethane hot melt (PURHM) and waterborne adhesives for athletic footwear, Henkel’s value proposition centers on line productivity gains (reduced process steps and energy), and bonding solutions for complex substrate combinations. Their recent product emphasis reflects a pragmatic approach to lowering manufacturing cost per pair while improving durability.
- H.B. Fuller Company (St. Paul) — A longstanding partner in footwear assembly, H.B. Fuller competes on a combination of performance adhesives and broad technical service capabilities. The company is a likely co‑development partner for brands seeking custom formulations that balance adhesion with process window robustness.
- BASF SE (Ludwigshafen) — Through waterborne polyurethane dispersions, BASF targets formulators and OEMs seeking adaptable chemistry platforms. Their dispersion technology is particularly relevant for new footwear materials used in lightweight and breathable constructions.
- Covestro AG (Leverkusen) — A critical upstream supplier of TPU and other polyurethane raw materials; Covestro’s offerings are foundational for downstream adhesive formulators, especially in thermoplastic and powder‑based systems.
- Arkema/Bostik (Colombes) — Positioned on sustainable bonding solutions, Bostik is active in the shift to low‑VOC and water‑based adhesives and is engaged with footwear brands emphasizing eco‑claims and supply chain transparency.
- Taiwan and China‑based formulators (e.g., NANPAO, TPUCO, GRECO, Xuchuan, Sinograce) — These regional specialists combine deep footwear application know‑how with proximity to major OEM clusters. Several have shown early wins on hydrolysis resistance and green certifications important to brand buyers.
- Ingredient and specialty suppliers (Lubrizol, etc.) — Provide TPU and bio‑sourced feedstocks for hot melt and solvent systems; portfolio expansions into bio‑based TPUs and performance additives are creating new routes to lower carbon intensity adhesives.
Recent product and positioning moves — from Henkel’s March 2025 emphasis on labor and energy reductions to Lubrizol’s introduction of bio‑sourced TPU grades — illustrate two parallel competitive pathways: performance differentiation (durability, bonding of mixed substrates) and sustainability differentiation (low VOCs, bio‑content). Both pathways are commercially relevant for 2026.
Market dynamics and near‑term risks
- Raw material volatility: MDI and TDI price swings tied to crude cycles continue to transmit through to adhesive formulators. 2026 procurement strategies must include index‑linked contracts, multi‑sourcing, and pass‑through pricing clauses to protect margins.
- Regulatory and green procurement pressure: Stricter emissions and chemical policies are accelerating conversion from solvent‑based systems to waterborne and low‑VOC technologies. Brands are simultaneously demanding lower carbon footprints, accelerating adoption of bio‑based polyols where performance permits.
- Trade and tariff shifts: Post‑2025 tariff changes on certain polyols and isocyanates have already increased landed costs in some regions. Manufacturers with flexible sourcing or regional formulation centers will fare better in 2026.
- Consolidation and supplier concentration: The market is supplied by a mix of global majors and strong regional players. Expect continued tie‑ups, co‑development partnerships, and selective M&A as firms seek scale in R&D and distribution.
Strategic playbook for 2026 — what leading companies should do now
We translate our analysis into five executable moves companies can implement in 2026 to secure competitive advantage:
- Hedge and diversify raw material exposure: Negotiate multi‑year supply agreements with price collars, create alternative formulations tolerant to polyol seed variations, and qualify secondary suppliers in low‑tariff jurisdictions.
- Prioritize waterborne and low‑VOC investments: Accelerate commercialization of waterborne and thermoplastic PU systems for segments where brands demand sustainability claims, while protecting premium performance niches with targeted solvent‑reduction roadmaps.
- Deploy modular manufacturing footprints: Shift towards smaller, flexible formulation hubs near major OEM clusters to reduce landed costs and improve responsiveness to design changes.
- Lock strategic OEM partnerships: Offer co‑development programs that bundle adhesive chemistry with application engineering and in‑line process consulting — a high barrier to switching for brand partners.
- Design a disciplined M&A and partnership approach: Target regional formulators with strong application know‑how or specialty tech (hydrolysis resistance, fast‑curing PURHM) to accelerate time‑to‑market in adjacent geographies.
How procurement, R&D and commercial teams should use the report
Procurement can use our supply‑risk indices and pricing scenarios to rework supplier contracts and build contingency inventories. R&D teams will find the technology adoption curves and regulatory timelines essential for prioritizing formulation roadmaps. Commercial teams can deploy the go‑to‑market playbook to structure multi‑year co‑development agreements and value‑based pricing models for brand customers.
Why PW Consulting’s analysis matters for 2026
Our methodology combines primary interviews across the footwear supply chain, bottom‑up build‑ups of adhesive demand per shoe type, and supplier‑level cost modeling that incorporates raw material price paths and tariff scenarios. The result is a pragmatic, executable set of insights that translate a mid‑single‑digit CAGR outlook into concrete operational and commercial actions. For organizations planning capital, R&D, procurement, or M&A moves in 2026, the difference between acting early or lagging behind will be decided on supply resilience and the ability to deliver validated sustainable chemistries at scale.
Accessing the full intelligence
This release highlights strategic takeaways and omitted granular splits by region, type, and application that are available in the full PW Consulting Polyurethane Adhesive For Shoes Market report. The complete report includes the proprietary segment matrices, supplier scorecards, and scenario models necessary to operationalize the 2026 playbook. Contact PW Consulting to obtain the full dataset and a tailored briefing for your business unit.
For detailed analysis of this topic, please visit the official page: Polyurethane Adhesive For Shoes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com