

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Undercarriage Parts Market Poised to Grow at a 5.2% CAGR During 2026–2032

Undercarriage Parts Market 2026: Strategic Intelligence Briefing — Why This Report Will Shape Your Next Move
PW Consulting today releases a focused industry briefing drawn from our full Undercarriage Parts Market research. As capital allocation cycles reset across OEMs, aftermarket specialists, and private equity players in 2026, the choices you make this year will determine supply chain resilience, margin capture, and market share for the next business cycle. This briefing explains how the market is evolving, the near-term levers that matter, and why our full report is essential for board-level and commercial decisions in 2026.
Undercarriage Parts Market
Market snapshot — directional scale and trajectory
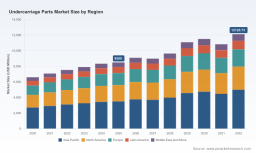
After sustained recovery from cyclical headwinds, the global undercarriage parts market reached approximately USD 8.5 billion in 2025 and is modeled to surpass USD 9.0 billion in 2026. Our proprietary forecast, covering 2026–2032, indicates a compound annual growth rate (CAGR) of 5.2% over the horizon — a pace that reflects a mix of replacement-driven aftermarket demand, OEM production scaling, and pockets of accelerated investment in mining and infrastructure projects.
Undercarriage Parts Market
The trajectory is non-linear: the market has grown materially since 2020, but is exposed to episodic pressures — raw-material volatility, regulatory shifts, and localized project cycles — that can compress margins or temporarily re-route demand between OEM and aftermarket channels. PW Consulting’s scenario overlays capture these oscillations and translate them into decision-ready implications.
Undercarriage Parts Market
Why 2026 is a strategic inflection point
- Capital deployment windows are tightening. Several OEMs and large aftermarket players announced capacity investments in 2024–2026 intended to secure supply and capture growth pockets. These moves mean capacity footprints will be materially different by the end of 2026.
- Input-cost dynamics are reshaping profit pools. Steel price volatility — with U.S. hot-rolled coil topping the USD 1,000/ton mark in early 2026 and cumulative double-digit increases in key markets in the two years before 2025 — is increasing production costs and forcing supplier price realignments and sourcing shifts.
- Regulation and performance demands are raising the bar. Emissions and safety regulations are accelerating the adoption of more durable, lighter, and efficient undercarriage configurations. This trend favors suppliers that combine metallurgy, surface treatment, and design expertise.
Core competitive dynamics (what we found)
The market remains moderately consolidated: the top three firms account for a significant share of revenue, while the top five firms control close to 60% of the market. This structure creates a bifurcated opportunity set — incumbents can leverage scale and integrated offerings, while nimbler challengers can win on specialization and localized cost advantages.
- Caterpillar Inc. — Continues to play as an integrated OEM champion, expanding capacity and product breadth. Its recent USD 500 million investment to increase undercarriage production capacity underscores a strategic bet on securing OEM and large aftermarket volumes.
- Komatsu Ltd. — Focused on system-level innovation. Product previews in 2026 emphasized updated undercarriage configurations that improve durability and ride quality — a signal that Komatsu is prioritizing lifecycle performance as a differentiation lever.
- Specialist manufacturers and aftermarket leaders (e.g., Berco/Thyssenkrupp, ITR/USCO, Topy, Dozco) — Compete on manufacturing depth, material science, and channel relationships. Recent M&A and capacity expansions among regionally-focused suppliers reflect a strategy to capture aftermarket replacement cycles closer to end users.
- OEM/integrated suppliers (e.g., Hitachi, John Deere, Liebherr, Volvo CE) — Continue to prioritize product integration and dealer-led aftermarket capture, investing in service offerings and parts availability to lock in total-cost-of-ownership advantages.
Recent signals to watch
- Komatsu’s CONEXPO‑CON/AGG 2026 previews of next‑generation dozers indicate a renewed OEM focus on undercarriage survivability and operator ride quality — features that will influence aftermarket specifications and replacement cycles.
- Caterpillar’s 2025 production-capacity investment demonstrates a pre-emptive approach to tightening supply and potential vertical integration of key components.
- Regional consolidation and greenfield expansions by specialist manufacturers (including acquisitions in 2025) suggest a two-track market: scale-driven incumbency in core markets and aggressive regional plays in emerging markets.
Strategic implications for executive teams in 2026
- Sourcing and input-cost hedging must be prioritized. With steel costs elevated and volatile, procurement strategies that combine multi-sourcing, long-term contracts, and localized production will reduce margin risk and improve delivery resilience.
- Differentiate through system-level performance, not just unit price. Product strategies that emphasize lifecycle cost, wear performance, and serviceability will command premium pricing and defend aftermarket share.
- Invest selectively in capacity or partnerships. Greenfield investments are capital intensive; in many cases, capacity-sharing agreements, tolling arrangements, or targeted acquisitions deliver faster returns and lower execution risk.
- Monetize aftermarket intelligence. Companies that build predictive maintenance services and parts-as-a-service offerings will generate sticky revenue and improve lifetime customer value.
- Scenario planning is table stakes. Plan for flanking scenarios including sustained steel inflation, a short-term slump in construction zones, and accelerated electrification/automation in heavy equipment that can alter wear patterns.
What PW Consulting’s full report delivers (practical, executable outputs)
- Proprietary market sizing and 2026–2032 forecast models (granular by type, application, and region) with downloadable datasets and sensitivity toggles.
- Competitive-positioning maps and a CR-based concentration analysis to identify white spaces and consolidation targets.
- Supplier due-diligence frameworks and EBITDA accretion models for M&A or JV scenarios.
- Raw-material impact matrices quantifying margin exposure across product types and mitigation playbooks (pricing pass-through, alloy substitution, and tactical inventory strategies).
- Commercial playbooks for OEMs and aftermarket specialists, including SKU rationalization, channel optimization, and service-program design.
- A three-year investment roadmap and a prioritized set of KPIs for operations, procurement, and sales aligned to multiple market scenarios.
- Interactive strategic dashboards and board-level presentation templates to accelerate decision-making.
Risk factors and surveillance triggers
Key risk vectors include continued raw-material inflation, disruptive new entrants with low-cost manufacturing footprints, and regulatory shifts that alter machine specifications. PW Consulting’s report builds in real-time surveillance triggers — thresholds for steel price moves, capacity announcements, and new OEM product launches — that convert market signals into tactical playbook updates.
How to use this report in Q2–Q4 2026 decision cycles
- Board strategy sessions: Use the report’s scenario outputs to stress-test capital plans and M&A pipelines.
- Procurement and operations: Implement the raw-material impact matrices and hedging recommendations to stabilize margins.
- Commercial leadership: Adopt the service and aftermarket playbooks to convert replacement cycles into higher-margin annuity streams.
- Investors and PE sponsors: Leverage the due-diligence frameworks to value regional consolidation targets and model post-close synergies.
Final read — what this briefing omits (and why)
In keeping with the “preview” principle, this briefing highlights directional scale, competitive posture, and action-oriented implications without disclosing proprietary segment-level datasets and region/application splits. Those granular inputs — including detailed type-by-application forecasts, SKU-level margin scenarios, and interactive dashboards that power our valuation and playbook models — are available exclusively in the PW Consulting full report and data package. That level of detail is required to translate the strategic signals above into executable plans with quantified ROI.
Call to action
For boards, strategy teams, and commercial leaders planning 2026 capital and go-to-market moves: the PW Consulting Undercarriage Parts Market report is designed as an operational guidebook. Book a briefing with our senior analysts to review model sensitivities, test M&A cases, and receive a tailored executive summary aligned with your strategic priorities.
Contact PW Consulting to schedule a private walkthrough of the full dataset and scenario models — and ensure your 2026 decisions are powered by market-grade intelligence rather than surface-level signals.
For detailed analysis of this topic, please visit the official page: Undercarriage Parts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com