

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High Purity Methyl Acetate Market to Reach USD 309.62 Million by 2032, Backed by a 5.48% CAGR (2026–2032)

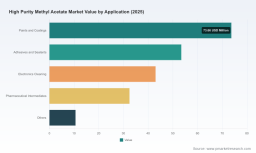
PW Consulting: High Purity Methyl Acetate Market — Strategic Imperatives for 2026
PW Consulting today publishes a strategic briefing accompanying our forthcoming full-market study on the High Purity Methyl Acetate market. The briefing distills the implications senior executives must internalize in 2026: the market recorded USD 213.12 Million in 2025 and — under our central case — is expected to expand at a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window, approaching roughly USD 310 million by 2032. These headline numbers mask structural shifts in feedstock economics, purity-driven value capture, and supplier concentration that will determine winners and losers over the next planning horizon.
High Purity Methyl Acetate Market
Why this briefing matters for 2026 decision-makers
- Translate macro growth into operational choices: Is your 2026 capex roadmap aligned to where value is concentrated (purity, specialty applications, or geographic advantage)?
- Protect margins against feedstock volatility: With methanol and acetic acid representing the majority of production cost, procurement and hedging strategies will materially influence competitiveness.
- Decide where to compete — and where to partner: High-purity grades command significant price premiums and require different production and quality infrastructure than commodity acetate.
- Use regulatory and sustainability positioning as a market lever: VOC-exempt status and biodegradability can be converted into commercial advantage in coatings, adhesives, and cleaning formulations.
Market dynamics and drivers
Three dynamics dominate the high-purity methyl acetate landscape in 2026: feedstock cost sensitivity, purity-driven pricing, and concentration among established suppliers. Production of high-purity grades is materially more capital- and energy-intensive than standard acetate because of advanced purification steps; this increases sensitivity to feedstock swings. Methanol and acetic acid together account for roughly 60–70% of production costs for methyl acetate, so changes in those markets transmit quickly to plant margins and short-term pricing.
High Purity Methyl Acetate Market
Recent market signals in China illustrate the risk profile: operating rate adjustments and methanol feedstock pressure produced upward movement in acetic acid spot values early in 2026, with further material increases observed through Q1. Those movements have immediate implications for contract pricing negotiations and working-capital planning for producers and buyers alike.
High Purity Methyl Acetate Market
On the demand side, high-purity methyl acetate benefits from multiple structural tailwinds. Its VOC-exempt status under relevant U.S. regulations supports substitution into environmentally focused coatings, adhesives, and cleaning formulations. More importantly for margin capture, true high-purity and ultra-high-purity grades — required by pharmaceutical intermediates, electronics cleaning, and premium coating systems — command meaningful price differentials versus commodity grades, driven by stricter quality specifications and the cost of advanced purification technologies.
Competitive landscape — where strategic advantage resides
The market exhibits moderate concentration: the top three players capture a meaningful share of market revenue and the top five increase that share substantially, which creates both barriers and opportunities for new entrants and regional challengers. Competitive advantage today is built on six capabilities:
- Purification and quality assurance — capacity to deliver electronic- and pharma-grade product.
- Feedstock integration and procurement scale — lowering exposure to spot swings through vertical integration or long-term feedstock contracts.
- Regulatory and certification footprint — ISO/REACH, pharma GMP-equivalent controls, and lab-validated analytics.
- Customer channel depth in coatings, adhesives, electronics, and pharma intermediates.
- Geographic production flexibility — ability to shift volumes or source nearer to demand hubs quickly.
- Cost and environmental profile — energy efficiency, emissions intensity, and biodegradability claims that influence buyer preferences.
Leading firms exemplify distinct strategic positions:
- Eastman Chemical Company: Positions its high-purity methyl acetate as a fast-evaporating, low-odor solvent tailored for coatings, 2-K polyurethane systems, adhesives, and pharmaceutical intermediates. The combination of VOC-exempt status and biodegradability provides Eastman a commercialization angle for environmentally oriented formulators.
- Celanese Corporation: Competes on purity leadership and broad industrial application set — from pharmaceutical intermediates to specialty coatings and foam blowing agents. Celanese’s emphasis on the highest purity available in the market targets customers where specification-driven pricing is less elastic.
- BASF SE and Wacker Chemie AG: Both leverage deep specialty-chemical portfolios and global customer footprints to supply high-purity grades to coatings and adhesive value chains; their differentiation leans on integrated solutions and formulation know-how.
- Merck KGaA (MilliporeSigma) and Thermo Fisher Scientific: These firms focus on ultra-high-purity, analytical, and life-science–grade methyl acetate for R&D and pharmaceutical manufacturing, where trace-level quality is a purchase determinant and switching costs are high.
- Anhui Ruibai New Materials (Ruibai Group): Represents a strategic counterweight from China — a large-scale, vertically integrated acetate producer with patented synthesis routes and capacity advantages. Its scale and integration can enable competitive pricing and fast response to regional demand swings, while certification credentials (ISO, REACH) address export and regulated-market requirements.
What PW Consulting’s full report delivers — practical, decision-ready content
The complete PW Consulting High Purity Methyl Acetate report is structured to convert insight into action. Key deliverables include:
- Validated market sizing and seven-year forecast (2026–2032), with sensitivity scenarios and upside/downside tails tied to raw material prices and regulatory shifts.
- Feedstock cost model and scenario stress-tests showing margin impact across price paths for methanol and acetic acid.
- Supplier scorecards and a risk matrix that evaluate production footprint, purity capabilities, certification status, and counterparty risk.
- Purity-grade pricing framework that quantifies typical premium bands and break-even points for investments in additional purification.
- Go-to-market playbooks for producers and downstream formulators — including product positioning templates, tiered sample qualification strategies for electronics/pharma customers, and contracting guidelines to lock-in supply at scale.
- M&A and JV screening toolset highlighting targets by capability gap (e.g., purification technology, geographic access, certified pharma supply).
- 24-month tactical roadmap for procurement, R&D, and commercial teams — prioritized actions to preserve margin and capture share amid volatility.
Note: This briefing follows the “trailer” principle — we intentionally withhold the granular regional and application-level splits and the full tabulated supplier scorecards to preserve the value of the full dataset. The report available on our site contains these detailed matrices and downloadable models.
How to use the report in 2026 corporate planning
- C-Suite / Strategy: Use the forecast scenarios and concentration analysis to set portfolio bets — whether to double down on high-purity, pursue vertical integration, or pursue licensing/partner models.
- Procurement: Implement the feedstock cost model to design hedging and long-term sourcing strategies; prioritize contracts that reduce short-term exposure to methanol and acetic acid spot volatility.
- R&D and Product Management: Calibrate formulation roadmaps to exploit VOC-exempt positioning and purity-led premium segments; prioritize investments in purification technology where return-on-capital is clearest.
- Operations and Capex Planning: Use supplier scorecards to evaluate whether brownfield upgrades versus greenfield capacity best meet demand timing and specification needs; run break-even analyses for additional purification stages against the premium for high-purity output.
- Commercial and Sales: Adopt the report’s qualification playbooks when approaching electronics and pharma customers — reduce qualification timelines and capture sticky, higher-margin contracts.
- M&A and Corporate Development: Screen targets against capability gaps identified in the report and use the report’s valuations framework to size strategic acquisitions or JVs.
Conclusion — immediate implications for 2026
2026 will be a year of active tactical choices rather than passive market-following. A market growing in the mid-single digits annually creates opportunity, but capture requires disciplined attention to feedstock risk, purity-driven product strategy, and supplier positioning. Firms that combine purification capability, procurement sophistication, regulatory-compliant manufacturing, and targeted commercial playbooks will convert forecast growth into above-market returns.
Call to action
PW Consulting’s full High Purity Methyl Acetate Market report contains the datasets, supplier scorecards, and executable templates described above. Corporates preparing 2026 budgets, procurement negotiations, or M&A pipelines should consult the full report for the granular regional and application-level intelligence that we intentionally redact here. Visit PW Consulting’s report page to request the complete dataset and tailored advisory support.
For detailed analysis of this topic, please visit the official page: High Purity Methyl Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com