

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
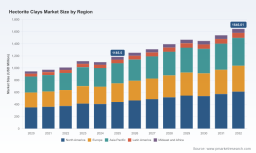
PW Consulting Forecast: Hectorite Clays Market Poised to Reach USD 1,646.01 Million by 2032

Hectorite Clays Market — Strategic Outlook for 2026: Why this Commodity Matters to Industrial and Specialty Chemical Decision‑Makers
As global manufacturers recalibrate product portfolios for resilience, sustainability and margin recovery, hectorite clays have re‑emerged as a high‑leverage material in several specialty value chains. PW Consulting’s Hectorite Clays Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—provides the actionable intelligence procurement, product, and corporate strategy teams need to convert mineral endowments into commercial advantage in 2026 and beyond.
Hectorite Clays Market
Headline market trajectory (what we measured)
Our analysis shows the hectorite market has moved from the mid‑single hundreds of USD million in the early 2020s into a structurally larger market by 2025, and continues to expand through the forecast window at a compound annual growth rate (CAGR) of roughly 4.8%. This steady growth masks meaningful near‑term variability driven by formulation trends in cosmetics and coatings, drilling demand cycles, and the evolving balance between natural and synthetic supply sources.
Hectorite Clays Market
Why this matters for 2026 decision cycles
- Procurement and supply security: Hectorite’s supply base is concentrated and differentiated by source type. Firms with exposure to formulations sensitive to trace minerals, or those operating in regulated end markets, need a procurement playbook that recognises both geological constraints and the premium for sustainably sourced natural material.
- Product formulation and NPD prioritisation: New product development decisions in personal care, coatings and specialty adhesives will hinge on rheological performance versus sustainability claims. Manufacturers must test trade‑offs between synthetic and modified natural clays to optimise cost, performance and marketing position.
- M&A and partnership focus: Market concentration is material and buying patterns favour near‑specialist producers. Strategic buyers and investors should prioritise targets that (a) control high‑purity natural feedstock, (b) offer proprietary modification platforms, or (c) bring formulation R&D that shortens customer validation cycles.
- Regulatory and sustainability compliance: 2026 will see more procurement contracts and product launches conditioned on transparent sourcing and lower life‑cycle impacts. Companies that can document both responsible extraction and low‑carbon processing will enjoy preferential access to premium channels.
What the data implies for 2026 strategies
At a macro level, the market’s CAGR near 4.8% indicates predictable expansion rather than explosive disruption—an environment suited to deliberate, capability‑building moves rather than speculative bets. Tactical implications include:
Hectorite Clays Market
- Hedge with dual sourcing: Where formulations permit, maintain both natural and engineered supply routes to manage price and availability shocks.
- Invest in application validation: Allocate R&D budget to head‑to‑head performance testing (suspension, texture, spreadability, shear recovery) and to generate claims‑supporting data for regulated end markets like cosmetics.
- Prioritise sustainability KPIs: Embed supplier environmental performance and mine rehabilitation metrics into procurement scorecards to reduce transition risk as downstream customers intensify ESG demands.
- Monitor concentration indicators: The market exhibits meaningful top‑tier concentration; buyers should track supplier stability and contingency capacity closely as part of their 2026 vendor risk assessments.
Competitive landscape — who matters and why
The hectorite value chain is populated by a mix of vertically integrated miners, specialty formulators, and additives companies that convert raw mineral into application‑ready rheology modifiers. Key players we profile and monitor include global mineral majors, specialty additives groups, and regional producers that feed local coatings and cosmetics supply chains.
- Elementis plc (UK/USA) — Controls the world’s principal high‑grade natural hectorite deposit and packages it into industry‑recognised brands. Their recent product introductions and focus on naturally activated lines highlight a strategy to capture premium formulation space while leveraging a unique upstream asset.
- China‑based specialty producers — Several manufacturers supply synthetic and organoclay variants targeted at drilling, paints and cosmetics. Their strengths are cost competitiveness, scale for regional markets, and fast product customisation cycles.
- Global additives and chemicals groups — Established additives players incorporate hectorite variants into broader portfolios, offering formulation services and global distribution—valuable to multinational end users seeking single‑vendor simplification.
- Specialist suppliers and processors — Smaller firms focus on niche organo‑modified grades or customer‑specific processing capabilities; they are important partners for co‑development in high‑value segments.
Recent product launches and technical advances provide real signals about where competition is heading. New “all‑in‑one” hectorite blends aimed at personal care formulations and targeted demonstrations of natural activation indicate a combined strategy of premiumisation and technical differentiation. Separately, academic and industrial research into mesoporous and steam‑assisted synthesis routes signals a longer‑term trend toward engineered microstructures with improved adsorption and rheology control.
Supply fundamentals and regulatory context
Hectorite’s upstream picture is atypical for a clay mineral: globally important natural feedstock is concentrated in a small number of deposits, with at least one major commercial mine offering a long resource life. That geological efficiency lowers the number of independent natural suppliers relative to other minerals, and it increases the strategic value of secure offtake and long‑term sourcing agreements.
Regulatory frameworks relevant to 2026 decisions include cosmetics safety assessments and evolving environmental standards for mineral extraction. Long‑established safety assessments support the use of certain modified hectorite grades in cosmetic formulations under specified concentration limits, which facilitates product development but does not remove the need for traceability and supplier documentation. Meanwhile, tightening environmental expectations in major markets are nudging both formulators and miners toward demonstrable stewardship practices.
What the PW Consulting report delivers (practical content you can use)
- Actionable market sizing and demand scenarios (2020–2025 historical base plus a 2026–2032 forecast) to underpin budgeting and MRP decisions.
- A supplier risk matrix and procurement playbook that includes contracting templates, recommended hedging approaches, and inventory buffers calibrated to application criticality.
- Competitive dossiers with capability maps for the major producers, including proprietary product positioning and go‑to‑market strengths.
- Segment‑level demand drivers (cosmetics, drilling, coatings, adhesives and other industrial uses) linked to actionable KPIs for pricing and formulation teams—presented as qualitative signals and decision rules rather than raw tables in this preview.
- Regulatory and sustainability roadmaps highlighting compliance triggers and low‑cost measures to capture green premium opportunities.
- M&A and JV opportunity assessment with shortlist criteria that reflect resource access, formulation IP and route‑to‑market synergies.
To respect strategic confidentiality and drive verification, the report’s full quantitative regional and application splits, vendor market shares and transaction models are provided exclusively in the source document and supporting data annexes.
Risks, leading indicators and monitoring framework
- Supply disruption risk: Concentrated natural supply increases exposure to operational outages. Leading indicators: mine operating reports, shipment lead times, and new capacity announcements from synthetic producers.
- Demand volatility: End‑market cyclicality (notably drilling and industrial coatings) can shift volumes quickly. Leading indicators: OEM orderbooks, construction activity indices, and seasonality in consumer personal care launches.
- Regulatory shift risk: Revisions to cosmetic ingredient guidance or mineral extraction permitting could change sourcing preferences. Leading indicators: regulatory advisory committee agendas and major market ESG procurement policies.
- Technology disruption: Advances in engineered hectorite or alternative rheology systems could alter value capture. Leading indicators: patent filings, peer‑reviewed material science publications and strategic partnerships between additives firms and research institutions.
How to use this insight in 90 days (recommended next steps)
- Commission formulation head‑to‑head tests to validate switching costs between natural and synthetic hectorite in core SKUs.
- Run supplier stress tests using the procurement playbook included in our report (simulate 30‑ and 90‑day supply shortfalls to quantify margin impact).
- Prioritise a shortlist of strategic suppliers for multi‑year agreements and negotiate environmental performance clauses tied to price adjustments.
- Brief your M&A committee on acquisition criteria that capture resource access, downstream formulation capability, and customer contracts.
Conclusion — the strategic takeaway
Hectorite is no longer just an obscure rheology additive; it is a strategically relevant mineral whose sourcing, modification and certification can materially affect product performance, brand claims, and margin outcomes. For 2026 planning cycles, decision‑makers should treat hectorite as a component that requires integrated sourcing, R&D and sustainability strategies. PW Consulting’s Hectorite Clays Market report delivers the quantitative forecast, supplier intelligence and execution templates needed to turn market structure into an advantage—while reserving the proprietary segmentation tables and supplier share datasets for the full report.
For access to the full dataset, regional and application splits, supplier shares, and downloadable procurement tools, please refer to the PW Consulting report landing page linked in our distribution materials.
For detailed analysis of this topic, please visit the official page: Hectorite Clays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com