

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Animal Monoclonal Antibodies Market Poised for 8.2% CAGR Through 2032

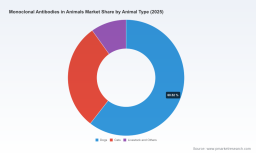
Monoclonal Antibodies in Animals Market 2026: Strategic Imperatives for Executive Decision‑Making
PW Consulting today publishes its definitive industry briefing, Monoclonal Antibodies in Animals Market — Strategic Outlook (base year 2025). The report synthesizes five years of historical performance and a seven‑year forecast horizon (2026–2032), showing the veterinary monoclonal antibody sector moving from a firmly established specialty market toward broader commercialization. At a global level the market passes an important commercialization milestone in 2026 and continues on a sustained growth trajectory with a compound annual growth rate (CAGR) of 8.2% through 2032.
Monoclonal Antibodies In Animals Market
Why 2026 is an inflection point for corporate strategy
-
Regulatory momentum and new pathways: Over the past 18 months regulators in major jurisdictions have signaled practical shifts that accelerate time‑to‑market while increasing expectations for post‑approval evidence. Examples include recent conditional approvals and guidance changes that de‑risk earlier commercialization for lead candidates, plus regulatory moves to modernize non‑clinical testing approaches.
Monoclonal Antibodies In Animals Market -
Commercial validation: Several high‑profile product approvals and licensing deals reported through 2025–2026 have shifted the market from proof‑of‑concept to commercial scale. These events validate veterinary monoclonal antibodies as investable assets and catalyze follow‑on programs across companion and production animals.
Monoclonal Antibodies In Animals Market -
Concentration and competition: The market shows high concentration at the top — a small group of incumbents controls a substantial share of commercially available assets — creating both competitive barriers and strategic acquisition opportunities. Our market concentration analysis registers a CR3 of 65.4% and a CR5 of 78.2%.
-
Unit economics pressure: Production cost remains a structural constraint that will shape pricing, adoption and route‑to‑market decisions; companies that achieve meaningful cost reductions or differentiated value propositions will capture disproportionate returns.
Recent industry developments that matter for 2026 plans
-
Regulatory approvals and conditional pathways: Conditional approvals for veterinary monoclonal products have become an operational reality, providing first‑mover advantages for brands that couple accelerated market entry with robust post‑market evidence generation.
-
Notable commercial and licensing moves: Several licensing transactions and acquisitions in 2024–2025 demonstrate an active market for platform technologies and specialty assets, highlighting opportunities for biologics developers and animal health majors to expand via M&A or collaborations.
-
Policy and testing innovation: Regulatory agencies have announced plans to modernize non‑clinical testing approaches for biologics, which can shorten development timelines and reduce animal use when companies adapt early to new methodologies.
What PW Consulting’s report delivers — practical intelligence for 2026 decisions
This report is built for executives who need actionable choices rather than academic descriptions. It contains:
-
A top‑line market sizing and growth trajectory calibrated to the 2025 base year and extended through 2032, reflecting a clear CAGR of 8.2% under the base scenario.
-
Scenario modelling (base, upside, downside) with trigger points and sensitivity analyses that translate macro market moves into investment thresholds and go/no‑go criteria for new programs.
-
Competitive intelligence dossiers for the leading players and biotech licensors, including commercial positioning, regulatory strategy, channel models and partnership histories.
-
A regulatory playbook that maps expedited and conditional approval routes across major jurisdictions and specifies the post‑approval evidence plans necessary to convert conditional to full licensure.
-
Manufacturing and cost‑of‑goods (COGS) diagnostics, including a CMO landscape, capacity risk matrix and technology levers (expression systems, formulation innovations) that materially affect margins.
-
Commercial launch blueprints: field force design, veterinary channel segmentation, pricing and reimbursement decision trees, and early adopter engagement templates for specialty clinics and referral centers.
-
M&A and partnership playbooks: target screening criteria, valuation frameworks for platform technologies, and integration checklists for rapid scale‑up.
-
Practical appendices: primary interview excerpts, data‑model overview and methodology, and a redacted workbook that can be licensed for scenario re‑runs.
Competitive landscape — strategic takeaways for incumbents and entrants
-
Major animal health companies are leveraging existing clinical channels and brand trust to convert biologics into repeatable revenue streams. Leaders with approved canine and feline mAbs have set commercial playbooks that others will emulate; incumbents should accelerate channel partnerships and bundle services (diagnostics + biologic therapy) to protect share.
-
Conditional approvals (recent examples in 2025–2026) have become a tactical route for capturing clinical precedence. Firms that design development programs to meet conditional criteria — and allocate resources for mandated post‑market studies — can obtain market access ahead of full licensure rivals.
-
Licensing and boutique biotech activity has intensified: platform specialists and regional developers are now attractive acquisition or collaboration targets for companies seeking differentiated pipelines or novel delivery formats (for example, orally delivered antibodies for production animals).
-
Strategically, there are two dominant playbooks: (1) scale & defend — deploy capital to broaden indication coverage and clinical evidence to maintain leadership; (2) specialize & monetize — focus on platform strengths (e.g., oral mAbs, rapid passive immunity) and monetize through licensing and co‑development.
Five strategic moves to prioritize in 2026
-
Adopt an approval‑first commercialization cadence: target conditional or accelerated pathways where feasible, and build a resourced post‑market evidence plan to convert early entrants into enduring incumbents.
-
Lock in manufacturing flexibility: secure CMO capacity and invest in cost reduction technologies now to protect margins as volumes scale; dual‑sourcing and modular capacity reduce single‑point supply risk.
-
Design value‑based pricing tied to measurable clinical outcomes: given production costs, reimbursement models that tie price to effectiveness and dosing intervals will drive payer and clinician acceptance.
-
Build partnerships with diagnostic and specialty clinic networks to accelerate adoption and create bundled care propositions that capture higher lifetime value per patient.
-
Execute a targeted M&A/ alliance program: prioritize platform licensors, formulation specialists, and regionally dominant developers who can shorten time to market or broaden therapeutic scope with minimal integration risk.
Scenario planning — watchlist and decision triggers
The report provides three scenarios aligned to strategic planning cycles. The base scenario aligns with the market’s 8.2% CAGR and assumes steady adoption and timely regulatory conversions. Upside assumes faster adoption driven by price erosion and large‑scale production efficiencies; downside reflects delayed approvals, reimbursement pushback, or manufacturing bottlenecks. We recommend executive teams monitor four primary triggers: regulatory policy updates, major approval outcomes, announced capacity expansions or CMO failures, and significant pricing or reimbursement decisions by large procurement channels.
How to put the report to work in your 2026 planning cycle
-
Investment committees: use the model to size potential returns across launch timelines and acquisition targets.
-
R&D and regulatory teams: adopt the regulatory playbook to re‑sequence trials for conditional pathways and set post‑market study budgets.
-
Commercial leadership: apply the launch blueprints to adapt field coverage and pricing strategies to local clinic economics.
-
Corporate development: leverage the partner scoring and valuation tools to prioritize licensing and acquisition targets that close capability gaps.
What we are intentionally withholding (and why)
Consistent with the “trailer” approach of this release, this briefing demonstrates the strategic insights and analyses contained in the full PW Consulting report while withholding the granular region‑by‑region and application‑level revenue tables and line‑by‑line forecasts that are central to tactical deployment. Those detailed splits and proprietary forecast workbooks are gated in the full report to preserve client value and enable confidential scenario re‑runs tailored to your organization’s portfolio and risk tolerance.
Next steps
Executives looking to convert this intelligence into 2026 decisions can license the full report and model package, commission a bespoke competitive deep‑dive, or schedule a strategy session with PW Consulting’s Animal Health practice. Our client work focuses on translating market growth (as captured in our base CAGR of 8.2% through 2032) into specific investment, R&D and commercialization actions that materially change outcomes.
PW Consulting — Strategy for the bio‑enabled animal health economy. For report access and engagement inquiries, please visit PW Consulting’s report page or contact our Animal Health practice leadership to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Monoclonal Antibodies In Animals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com