

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Single Mode Fiber Bundle Market to Expand at a 7.8% CAGR, Powering Growth in Data Centers and Medical Imaging
By pmarketresearch, 2026-07-15
Single Mode Fiber Bundle Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As global networks accelerate capacity upgrades and optical architectures diversify, single mode fiber (SMF) bundles have moved from niche technical components to strategic enablers of carrier, hyperscale, industrial and specialty photonics deployments. PW Consulting’s latest market study, anchored on a 2025 base year and a 2026–2032 forecast window, quantifies a resilient expansion in the SMF bundle market — driven by renewed capital intensity in data centers, broadband rollouts, and an expanding set of non-telecom applications. Our top-line projection: the global market reached USD 330.1 Million in 2025 and is set to grow at a 7.8% compound annual growth rate (CAGR) over the forecast horizon, approaching the mid-hundreds of millions by 2032.
Single Mode Fiber Bundle Market
Why this report matters for 2026 strategy
-
Time-sensitive capital allocation. For network operators and optical component suppliers, 2026 is a pivotal year to rebase capex assumptions. The market’s steady CAGR and near-term uptick imply that procurement strategies and capacity investments made this year will materially affect unit economics and service timelines through 2032.
Single Mode Fiber Bundle Market -
Supplier selection and negotiating leverage. With a moderately concentrated supplier base (the top three firms account for ~42.5% of market revenue and the top five roughly ~58.8%), purchasers can optimize sourcing through portfolio rationalization, long-form agreements, and contingency sourcing — especially where tariffs and raw-material volatility have increased cost exposure.
Single Mode Fiber Bundle Market -
Cross-sector growth windows. Beyond telecom and data centers, applications in sensing, medical optics, high-power laser delivery and aerospace create differentiated premium opportunities for firms that can adapt bundle form-factors and qualification processes rapidly.
Market trajectory: the headline numbers
Our historical series documents consistent expansion from 2020 through 2025, with the market rising from the low hundreds of millions to USD 330.1 Million in 2025. Based on demand drivers and supply-side dynamics modeled in the report, the market is projected to exceed USD 360 Million in 2026 and continue expanding across the 2026–2032 forecast period at a 7.8% CAGR, reaching an elevated scale by 2032. These aggregated figures reflect both traditional telecom demand and the acceleration of specialty applications that are beginning to represent a growing share of vendor roadmaps.
Dynamics shaping 2026 decisions
-
Regulatory and policy shifts. Recent policy moves in major markets are re-shaping transition risk and deployment windows. For example, regulatory changes affecting technology transition rules and broadband classification have implications for legacy copper-to-fiber migration timelines and service continuity obligations. Decision-makers need to model multiple regulatory scenarios when planning network upgrades to avoid stranded assets and to ensure emergency-service continuity during transitions.
-
Trade and tariff risk. Import restrictions and tariffs enacted in the prior 18 months have materially altered landed costs for certain cross-border fiber products. Buyers and manufacturers must revisit trade strategies — localized manufacturing, nearshoring and tariff engineering — to protect margins and maintain predictable lead times.
-
Raw-material and supply-chain pressure. Commodity and component price movements have raised production costs for optical fiber and related assemblies. In early 2026, industry pricing pressures re-emerged, underscoring the importance of active procurement hedging, dual-sourcing strategies and inventory optimization for manufacturers and system integrators.
-
Technology convergence and product innovation. Advances such as multi-core fiber demonstrations and hybrid bundle architectures are beginning to surface in trade shows and product roadmaps. These innovations create both a threat (product obsolescence for incumbents slow to adapt) and an opportunity (premium ASPs for differentiated, performance-assured bundles).
Competitive landscape: what winners are doing
The market exhibits a clear mix of global incumbents and specialized niche players. Established fiber and cable houses continue to dominate systems-oriented and high-volume telecom/business deployments, while highly specialized vendors service medical, aerospace, laser and instrumentation segments where qualification cycles are longer but margins can be premium.
-
Large-volume incumbents — firms with deep optical manufacturing footprints and broad product portfolios are optimizing scale through bend-insensitive designs, high-density bundle constructions and integrated cable systems suitable for backbone and FTTH infrastructures.
-
Regional and specialty players — niche suppliers are capitalizing on application-specific requirements (e.g., high-power laser transmission, fused silica bundles for medical use, polarization-maintaining configurations for instrumentation) by offering configurable assemblies and rapid prototyping capabilities.
Representative firms featured in our competitive analysis include long-standing global leaders in glass and cable manufacturing, prominent system suppliers with enterprise and telco-focused offerings, and agile specialists addressing instrumentation and industrial laser markets. The report profiles each firm’s strategic positioning, product portfolio highlights, commercial strengths, and likely moves over the next 18–36 months — including potential areas of M&A interest and capacity reallocation. Additionally, we map partner ecosystems, critical supplier relationships and the commercial levers companies are using to protect margin under commodity pressure.
What the PW Consulting report provides — practical, decision-ready content
This study is designed as an operational manual for executives, strategy teams and procurement leaders. It blends rigorous quantitative modeling with practical tools you can apply in 2026 planning cycles:
-
Market sizing and demand scenarios — top-down and bottom-up models with alternative adoption curves to stress-test investment decisions.
-
Supply-chain and cost-to-serve mapping — supplier archetypes, raw-material exposure matrices, and end-to-end lead-time sensitivity analysis to guide contingency decisions and inventory policy.
-
Commercial playbooks — tender frameworks, negotiation levers, and contract structures tailored for high-volume telecom buys versus low-volume specialty assemblies.
-
Go-to-market frameworks — segmentation strategies for entering adjacent specialty markets (medical, sensing, aerospace) where certification and qualification are the primary barriers.
-
M&A and partnership scorecards — criteria for target selection, valuation sensitivities, and integration checkpoints relevant to capability-driven consolidation.
-
Regulatory risk matrix — scenario-based assessments of policy changes (including technology transition rules and trade measures) and recommended mitigations for service providers and vendors.
-
Implementation-ready dashboards — KPI sets and monitoring templates designed to track market share, margin pressure, and capacity utilization quarterly.
Actionable recommendations for 2026
-
Rebalance procurement timelines. Lock in strategic suppliers for base volumes while keeping a portion of demand flexibly sourced to exploit spot-market pricing or to pivot to localized production if tariffs persist.
-
Prioritize capability investments. For manufacturers, invest selectively in modular assembly and qualification capabilities that reduce time-to-market for specialty bundles, enabling premium pricing in non-commodity segments.
-
Build regulatory playbooks. Operators should maintain scenario-based plans for legacy service grandfathering and 911/critical-service continuity to reduce transition risk when moving services from copper to fiber.
-
Evaluate M&A or JV paths. Given moderate market concentration, strategic acquisitions that add unique form-factors, connectorization expertise, or regional manufacturing footprint can accelerate market entry and margin accretion.
Signal watch: near-term events to monitor
-
Product demonstrations and multi-core fiber (MCF) integrations showcased at major industry events signal the pace at which alternate architectures could move from lab to deployment. We observed notable MCF and hybrid solutions previewed in early 2026, which merit attention from both buyers and incumbents.
-
Policy and trade updates — sudden changes in tariff postures or domestic content incentives can create immediate shifts in procurement routing and capital allocation.
-
Raw-material cost movements — continued upward pressure will compress margins absent corresponding price pass-through mechanisms; monitoring suppliers’ cost disclosures and inventory positions is now essential.
How to use this analysis
This briefing provides a strategic perspective and operational starting points. For teams preparing 2026 budgets, negotiating supplier agreements, evaluating M&A targets, or designing go-to-market plays in adjacent specialty segments, the full PW Consulting Single Mode Fiber Bundle Market report delivers the necessary quantitative detail, primary-source interview excerpts, and model sensitivities to convert insight into action.
Next steps — where to find the full intelligence
We have intentionally highlighted the analytical framework, headline market dynamics, and the decision-useful tools contained in the study while reserving granular segmentation tables, regional and application breakdowns, and proprietary company-by-company revenue estimates for the full report. Access to the complete dataset and downloadable models is available through our report distribution channels. For enterprise licensing, bespoke briefings, or to request an extract tailored to your procurement, product or M&A agenda, contact your PW Consulting representative or visit our report landing page.
For detailed analysis of this topic, please visit the official page: Single Mode Fiber Bundle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide N‑Allylamine Market Set to Grow at a 5.12% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide N‑Allylamine Market — Strategic Outlook for 2026: Actionable Intelligence from PW Consulting
PW Consulting’s new market study, "Worldwide N‑Allylamine Market (Base Year: 2025) — 2026–2032 Forecast," delivers the kind of decision-grade intelligence senior executives need to shape 2026 strategy. With rigorous historical analysis covering 2020–2025, a clear forecast through 2032 and a compound annual growth rate (CAGR) of 5.12% across the forecast horizon, the report translates market dynamics into practical commercial playbooks for suppliers, buyers and investors operating in high‑purity amine chemistry.
Worldwide N-Allylamine Market
Why this report matters for 2026 decisions
-
Timing and clarity — The industry moves on multi-year investment cycles. Our report uses 2025 as the base year and projects forward to 2032, enabling leadership teams to align CAPEX, capacity ramps, and partnership strategies with an analytically defensible view of demand evolution.
Worldwide N-Allylamine Market -
Demand certainty — N‑Allylamine’s end markets (including pharmaceutical intermediates, water treatment chemistries, polymer synthesis and agrochemical applications) are each progressing under distinct drivers: pharmaceutical pipeline expansion and regulatory complexity, infrastructure-driven water treatment spending, and polymers’ shifting formulation needs. We quantify how these drivers aggregate to overall market growth and outline the implications for product mix and purity positioning.
Worldwide N-Allylamine Market -
Risk and resilience — Our scenario and sensitivity analyses surface how supply shocks, raw material volatility and regional trade disruptions could alter near‑term availability and pricing. That makes the report an immediate input to procurement contingency planning, inventory policies and hedging strategies for 2026.
Market trajectory in numbers (high‑level)
After recovering from pandemic-era disruptions, the N‑Allylamine market expanded from approximately USD 41 million in 2020 to USD 52.4 million in 2025. Based on our vetted bottom‑up sizing and triangulation with industry sources, the market is forecast to continue expanding to roughly USD 74.3 million by 2032 — reflecting a 2026–2032 CAGR of 5.12%. These headline figures mask an important nuance: growth is steady but not uniform across channels, grades and geography, which creates differentiated opportunities for value capture.
Report scope: what you’ll get (practical, actionable content)
-
Executive summary with investment implications — 3‑ to 5‑point actions tailored for market entrants, incumbent producers and strategic buyers.
-
Historical market sizing (2020–2025) and methodology appendix — transparent data lineage and assumptions for CFO review.
-
Forecast model (2026–2032) — downloadable model with demand drivers, elasticity assumptions and adjustable scenarios to test your own hypotheses.
-
Segmentation analyses — by region, product purity and application, with dynamics and growth vectors mapped to buyer use cases.
-
Supply chain and margin map — feedstock exposure, production routings, shipping and storage constraints, and suggested margin preservation tactics.
-
Pricing and procurement playbook — recommended negotiation levers, contract structures and inventory guidelines under different volatility regimes.
-
Regulatory and compliance landscape — region‑specific constraints that will materially affect commercial access and product specs in 2026 and beyond.
-
Company profiles & competitive landscaping — strategic profiles, capability maps and M&A candidate shortlists for market consolidation or bolt‑on expansion.
-
Risk matrix & contingency frameworks — prioritized actions to safeguard supply and commercial continuity.
Competitive landscape — what we found
The N‑Allylamine market exhibits a moderate level of concentration: top suppliers hold meaningful scale, yet there remains ample room for regional players and specialty producers to differentiate. The profiles below synthesize public positioning and product focus to highlight competitive implications for 2026 strategy.
-
Tokyo Chemical Industry Co., Ltd. (TCI) — Tokyo, Japan ( https://www.tcichemicals.com). TCI’s strength is in high‑purity intermediates tailored to organic synthesis and pharmaceutical R&D. Their emphasis on catalogue reliability and consistent high‑purity grades positions them as the premium supplier for process‑sensitive customers. Strategic implication: suppliers should assess whether a premium, documentation‑heavy offering can command higher margins with regulated customers in 2026.
-
Merck KGaA (Sigma‑Aldrich) — Darmstadt, Germany ( https://www.sigmaaldrich.com). Merck combines strong brand trust in chemical supply with capabilities spanning lab to bulk quantities. Their global distribution network and regulatory know‑how make them a go‑to for customers requiring documented supply chains. Strategic implication: competitors must evaluate how to match service levels and compliance documentation or pursue niches where speed and cost trump full documentation.
-
Thermo Fisher Scientific Inc. (Alfa Aesar) — Waltham, MA, USA ( https://www.thermofisher.com). Alfa Aesar’s offering focuses on laboratory‑scale and small industrial use, supporting early‑stage development and small batch production. For 2026, their role as a reliable R&D supplier underpins product development pipelines for pharmaceutical and agrochemical firms.
-
Capot Chemical Co., Ltd. — Hangzhou, China ( https://www.capotchem.com). As a manufacturing and export‑oriented supplier, Capot plays a cost‑competitive role in supporting large‑volume industrial and intermediate markets. Their proximity to regional feedstocks and flexible production lines can accelerate time‑to‑supply for customers in Asia and beyond. Strategic implication: Western players should refine their value proposition around quality assurance, regulatory service and supply security to counter cost competition.
Competitive dynamics and strategic options for 2026
-
Positioning by purity and service — The market rewards two distinct value propositions: premium high‑purity supply (for pharma and sensitive polymer applications) and cost‑effective bulk supply (for commodity industrial users). Firms should decide whether to invest in purity upgrades and regulatory dossiers or scale production for margin capture.
-
Partnerships vs. in‑house expansion — For buyers dependent on uninterrupted high‑purity supply, forward integration (minority stakes or long‑term off‑take agreements) offers insurance versus spot market volatility. For suppliers, tolling and contract manufacturing models can extend utilization without full greenfield exposure.
-
Geographic diversification — While demand growth is globally distributed, regional supply constraints and trade policy risk mean that 2026 procurement strategies must consider multi‑sourcing and near‑shoring options to reduce lead‑time risk.
-
Portfolio optimization — Given steady overall market growth, incremental revenue alone will not guarantee margin expansion. Tactical SKU rationalization, premium grade focus and differential pricing across channels are essential to protect profitability.
-
M&A and bolt‑on opportunities — The market’s moderate concentration presents opportunities to acquire complementary capacity or technical know‑how. Our report flags higher‑value subsegments and candidate profiles fit for consolidation plays.
Regulatory and supply‑chain watchpoints for 2026
Regulatory scrutiny around intermediates used in pharmaceutical and agrochemical synthesis is increasing. For 2026 planning, companies must prioritize controlled documentation, batch traceability and environmental compliance to avoid customer disqualification. On the supply side, feedstock availability and logistics chokepoints — particularly containerized shipping and hazardous‑goods handling — will be decisive factors in service level agreements and working capital planning.
How executives should use this study in 2026
-
CxOs: Align capital plans with the report’s forecast scenarios — use the downloadable model to stress‑test the business under price and volume shocks.
-
Commercial leaders: Implement customer segmentation by value — create differentiated contracts for high‑purity, high‑documentation clients versus cost‑sensitive industrial buyers.
-
Supply‑chain managers: Reconfigure supplier scorecards and inventory buffers informed by our risk matrix; prioritize dual‑sourcing for critical grades.
-
M&A and corporate development teams: Use our shortlist of strategic acquisition targets and capability gaps to accelerate inorganic growth plans.
Why PW Consulting’s study is distinct
Beyond headline forecasts, this study couples granular operational levers (feedstock exposure, purity upgrade costs, tolling economics) with strategic frameworks that translate market data into executable 90‑, 180‑ and 360‑day initiatives. Our methodology blends bottom‑up facility modeling, supplier interviews and trade data triangulation — and we deliberately document key assumptions so corporate teams can re‑run the model under bespoke scenarios.
Next steps and access
This overview intentionally emphasizes strategic takeaways while withholding the granular regional, application and grade splits that form the core of transaction‑level decision making. For access to the full dataset, interactive forecast model, and detailed segmentation (including the breakdowns by region, type and application), please consult the full report page on the PW Consulting portal. The full report includes proprietary appendices, downloadable models and a concise M&A candidate dossier designed to accelerate 2026 execution.
In an environment where incremental product demand is steady but competitive pressure and regulatory complexity are rising, the right intelligence delivered early is a decisive advantage. PW Consulting’s N‑Allylamine study is built to be that advantage for executives planning for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide N-Allylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Embedded Hypervisor Software Market to Rise from USD 565.0 Million in 2025 to USD 937.36 Million by 2032 at a 7.5% CAGR
By pmarketresearch, 2026-07-15
Worldwide Embedded Hypervisor Software Market — Strategic Briefing for 2026 Decision-Makers
As embedded systems evolve from isolated controllers into networked, mixed‑criticality platforms, hypervisor technology has become a strategic lever for product differentiation, safety compliance, and cost consolidation. PW Consulting’s new market study on the Worldwide Embedded Hypervisor Software Market provides a forward‑looking guide for executives who must make procurement, architecture and partner decisions in 2026. The market is no longer a niche engineering concern: after steady expansion through the early 2020s, the global embedded hypervisor market was estimated at USD 565.0 Million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of 7.5% over the forecast period, reaching roughly USD 937 Million by 2032. This trajectory creates windows of opportunity — and risk — for OEMs, Tier‑1 suppliers, semiconductor vendors, and systems integrators.
Worldwide Embedded Hypervisor Software Market
Why this matters to C‑suite and product leaders in 2026
Three trends turn hypervisor selection into a C‑level strategic priority:
Worldwide Embedded Hypervisor Software Market
- Safety and certification are non‑negotiable. Regulation and procurement requirements tied to DO‑178C (avionics) and ISO 26262 (automotive) mean that embedded hypervisors are evaluated as part of system certification pathways, not just as software components.
- Hardware choices constrain software architecture. Effective Type‑1 partitioning requires silicon with virtualization extensions; design decisions around Arm cores, RISC‑V extensions, or x86 virtualization materially affect performance, certification cost, and time‑to‑market.
- Consolidation potential vs. supplier concentration. The market shows meaningful concentration — the top three vendors collectively control a majority share, and the top five expand that control further — creating tradeoffs between best‑of‑breed capabilities and vendor dependence.
Market trajectory and practical implications
The market’s macro trajectory is clear: from a mature engineering problem to an enterprise procurement decision whose financial implications can be modeled predictably. Our projections suggest a meaningful uplift between 2025 and 2026 as platforms move from single‑OS ECUs to multi‑OS, multi‑criticality domains. This is a buying cycle that aligns with new silicon availability (Armv9 and emerging RISC‑V profiles) and growing requirements for certified partitioning. For 2026 planning, this means three practical implications:
Worldwide Embedded Hypervisor Software Market
- Prioritize hardware‑software co‑design. Architects must lock silicon and hypervisor roadmaps together to avoid rework when moving from evaluation to certifiable product builds.
- Budget for certification early. Certification planning (DO‑178C DAL A, ISO 26262 ASIL D, IEC standards for industrial and medical device contexts) should inform vendor selection and contractual milestones.
- Embed vendor concentration into risk models. With the marketplace exhibiting high concentration among a handful of specialist suppliers, procurement teams should model supplier failure, price pressure, and strategic lock‑in as scenarios in 2026 planning.
What the report delivers — practical, operational intelligence (not theory)
This study is expressly designed to move beyond high‑level forecasts into decision‑ready assets. Highlights of the operational content include:
- Vendor selection framework and weighted scoring models tailored to mixed‑criticality use cases (automotive ECUs, avionics line‑replaceable units, industrial controllers, medical devices).
- Certification playbooks that map functional and verification artifacts required to achieve DO‑178C and ISO 26262 objectives when using embedded hypervisors — with timelines and estimated resource profiles to support 2026 roadmap planning.
- Integration blueprints and reference architectures showing realistic consolidation paths (number of guest OSs, partition layouts, timing budget allocations) that can be adapted for specific silicon targets.
- Cost of ownership and productization models that quantify NRE, certification, maintenance, and upgrade paths across multi‑year product lifecycles.
- RFP templates, test plans, and security assessment checklists that accelerate vendor evaluation and reduce procurement cycle time.
These artifacts are presented as editable deliverables so teams can drop them into quarterly planning, R&D roadmaps, and supplier diligence workflows. The goal is to convert market intelligence into executable steps for 2026 product and sourcing decisions.
Competitive landscape — profiles and strategic moves to watch
The vendor landscape is dominated by specialist suppliers with deep safety and certification heritage. Our report analyzes each major player’s positioning, certification assets, architecture support, and recent strategic moves — distilled into implications for buyers.
- Wind River — A leader in avionics and safety‑critical systems, known for its VxWorks 653 hypervisor. Recent product work has extended support to RISC‑V and Armv9, signaling a tactical push to align with new silicon and broaden addressable platforms. For buyers, Wind River represents a fast path to avionics certification but comes with premium positioning and an expectation of close engineering partnership.
- Green Hills Software — Provides INTEGRITY‑178 and μ‑velOSity with strong ARINC 653 and real‑time partitioning credentials. Its strengths lie in isolation guarantees and legacy avionics/industrial deployments; for 2026, Green Hills is attractive where proven partitioning semantics and deterministic behavior are non‑negotiable.
- Lynx Software Technologies — LynxSecure emphasizes MILS‑class separation and has pursued strategic silicon relationships (e.g., partnerships for NXP i.MX integration). Expect Lynx to be a go‑to for industrial and defense systems that require formalized isolation and close SoC partners.
- SYSGO — PikeOS offers strong cross‑industry certification focus and recent medical device certification advances. SYSGO’s multi‑domain approach makes it a viable option for OEMs seeking a single supplier to cover avionics, automotive, industrial, and medical segments.
- Real‑Time Systems GmbH — Focused on pragmatic, performance‑oriented hypervisors for ARM and x86, with traction in automotive and industrial IoT. Their strength is in flexible, lightweight virtualization primitives that suit resource‑constrained ECUs.
- BlackBerry QNX — With QNX Hypervisor and established automotive safety credentials, QNX continues to be a leading choice for Tier‑1s and OEMs focused on in‑car infotainment and safety‑critical domains, particularly where integration with existing QNX stacks is desired.
- Mentor Graphics (Siemens EDA) — Brings a systems‑level perspective and toolchain integration that benefits large programs needing end‑to‑end development workflows.
- ETAS (Bosch Group) — RTA‑Hypervisor targets multi‑OS automotive ECUs and brings deep automotive toolchain compatibility and AUTOSAR alignment.
The recent vendor activity we track — product releases expanding architecture support, certification achievements in new domains, and strategic silicon partnerships — confirms a market where technical differentiation is tightly coupled with certification and ecosystem playbooks. These are the variables that will determine winners in 2026 procurement rounds.
Technology and regulatory dynamics that will shape 2026 decisions
- Hardware bottlenecks: Effective Type‑1 partitioning needs silicon with virtualization extensions (ARM virtualization extensions or x86 VT‑x). Buyers must validate platform support early in the selection process.
- Regulatory imperatives: DO‑178C DAL‑A and ISO 26262 ASIL‑D continue to govern certification strategies for avionics and automotive respectively — hypervisor selection is tightly coupled to achieving these certifications.
- Standards and APIs: Standards like ARINC 653 define partitioning interfaces and time‑space separation semantics; adherence simplifies certification and supplier interoperability.
- Real‑time limitations of Type‑2 hypervisors: For hard real‑time tasks, Type‑2 approaches (hosted on general‑purpose OSs) often introduce latencies inconsistent with 1ms determinism — a common trap for teams pursuing fast prototyping without long‑term certifiability.
Recommendations for 2026 planning
For executive teams crafting 2026 roadmaps, we offer four succinct recommendations:
- Make certification a gating item, not an afterthought. Embed certification milestones into procurement contracts and architecture signoffs.
- Align silicon choices with hypervisor roadmaps. Reserve budget and calendar for early co‑validation on target SoCs with virtualization extensions.
- Adopt a hybrid sourcing strategy. Combine established, certified suppliers for safety‑critical partitions with more flexible suppliers for non‑critical domains to balance risk and cost.
- Quantify concentration risk and mitigate via dual‑vendor evaluation on key systems. Given market concentration, maintain an alternate path to de‑risk supplier disruption or pricing pressure.
How PW Consulting’s study should be used in procurement and product committees
The report is intended as an operational toolbox for committees making binding decisions in 2026. Use it to:
- Shortlist vendors against a prescriptive, use‑case specific checklist.
- Create certification‑dependent gating criteria for prototype → product transitions.
- Inform M&A diligence where embedded virtualization is a target capability.
- Develop five‑year supplier roadmaps that align software stacks with silicon lifecycle and support windows.
Final note — a strategic “trailer” to drive controlled disclosure
PW Consulting’s Worldwide Embedded Hypervisor Software Market report offers both the strategic narrative and the tactical artifacts required for high‑stakes 2026 decisions. This briefing highlights the macro trajectory (USD 565.0 Million market in 2025; projected CAGR of 7.5% to roughly USD 937 Million by 2032), the competitive dynamics, and the operational levers procurement and product teams must control. The report contains in‑depth vendor scorecards, editable procurement templates, certification timelines, and integration blueprints that we intentionally do not reproduce here so that decision teams can access verified source materials, templates, and granular segmentation directly from the report package.
To obtain the complete set of deliverables, vendor scorecards, and the full dataset behind the projections, please visit the PW Consulting report page for the Worldwide Embedded Hypervisor Software Market. Use the materials there to convert strategic intent into executable, low‑risk product and procurement action in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Steady Growth: Worldwide Automotive Water Separation Systems Market Set to Expand at a 5.02% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Automotive Water Separation System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Automotive Water Separation System market delivers a focused, decision-grade briefing designed to support executive choices in 2026. Grounded in an independent base-year analysis (2025) and a 2026–2032 forecast horizon, this briefing synthesizes market sizing, regulatory drivers, supply-chain stress points, and competitive moves into actionable implications for OEMs, Tier‑1 suppliers, aftermarket players and strategic investors.
Worldwide Automotive Water Separation System Market
Why this market matters in 2026
Water contamination in liquid fuels remains a mission‑critical reliability and regulatory issue for internal combustion powertrains—especially in commercial and off‑road segments where exposure to moisture and biodiesel blends is higher. Our report estimates the global market at USD 1,462 Million (base year 2025), and projects a steady recovery and expansion through the forecast period at a compound annual growth rate (CAGR) of 5.02%, reaching roughly USD 2,060 Million by 2032. This growth trajectory reflects a combination of regulatory tightening, technology refresh cycles among large fleets, and material‑led cost dynamics that will shape supplier positioning and procurement strategies in 2026.
Worldwide Automotive Water Separation System Market
Report scope — what’s inside (practical and operational)
- Market sizing and multi‑scenario forecasts (2026–2032) with sensitivity analyses reflecting regulatory and raw‑material shocks.
- Detailed segmentation frameworks (by region, vehicle type and component) and demand drivers — note: detailed split tables and proprietary datapacks are available in the full report.
- Regulatory and standards impact assessment (EN 590, EPA requirements, Euro legislation) and compliance roadmaps for product teams and certification managers.
- Technology trends and R&D horizon‑mapping for filter media, coalescing membranes and sensor/electronic integration, with TRL (technology readiness level) scoring.
- Supply‑chain heat‑map and raw‑material risk register (including glass microfiber and polymer membranes), plus alternative sourcing and hedging tactics.
- Competitor benchmarking, product portfolio mapping, supplier nomination case studies and likely OEM sourcing priorities.
- M&A and partnership opportunity matrix with valuation multiples and integration risk flags for strategic buyers.
- Operational playbooks for procurement, engineering and aftermarket commercial teams — from design‑to‑cost to warranty mitigation.
High‑impact takeaways for 2026 executives
- Prioritize regulatory‑constrained performance: Standards such as EN 590 and EPA testing thresholds are not static. Design and procurement teams must lock product specifications to meet or exceed mandated water‑removal efficiencies to avoid retrofits and warranty exposures.
- Mitigate raw‑material exposure now: Glass microfiber price inflation and constrained borosilicate supplies have already driven cost pressure. Sourcing teams should implement multi‑tier supplier strategies, qualify alternative media (including polymer coalescers) and negotiate indexed contracts to limit margin erosion.
- Invest selectively in sensor integration: Hybrid mechanical/electronic separators that provide real‑time water detection are moving from premium to mainstream in higher‑duty segments. Fleet operators will pay for predictive maintenance signals that reduce downtime and fuel‑system damage.
- Plan for technological bottlenecks: Coalescing polymer membranes face technical limits in achieving sub‑50 ppm water removal required for some future emissions and fuel‑quality scenarios. Roadmaps should hedge between incremental improvements and partnerships with membrane innovators.
- Address channel economics: Aftermarket and service networks represent both a revenue stream and a reputational risk. Warranty‑backed replacement programs combined with OEM approved maintenance bundles can capture recurring revenue while reducing catastrophic failure claims.
Competitive landscape — who’s shaping 2026 supplier pools
The market remains moderately consolidated with a small group of established filter and filtration systems manufacturers commanding a meaningful share of global OEM and aftermarket nominations. Key companies profiled in the report include:
Worldwide Automotive Water Separation System Market
- Donaldson Company (Bloomington, MN, USA) — advancing media science with recent Synteq XP upgrades aimed at improved efficiency on low‑sulfur fuels.
- Parker Hannifin (Racor Division, Cleveland, OH, USA) — cementing OEM relationships through strategic nominations for next‑gen truck platforms.
- Cummins Inc. (Fleetguard Division, Columbus, IN, USA) — integrating NanoNet separators with engine platforms and securing ISO‑level validations.
- Mann+Hummel and Mahle (Germany) — competing on multifunction filter assemblies for both passenger and commercial applications.
- Hengst SE, Sogefi Group, Separ Sweden, Davco Technology (Eaton) and Baldwin Filters — each defending niche strengths ranging from swirl separation technologies to heavy‑duty modular systems.
Recent competitive moves — product launches, OEM nominations and validation milestones — point to a market where OEM preference and co‑development agreements materially influence supplier selection. The report contains granular vendor scorecards and decision trees used by procurement committees when evaluating nomination rounds.
Regulation, raw materials and technology — dynamics that will decide winners
- Regulatory pressure: EN 590 and analogous standards enforce low allowable water content in diesel; U.S. EPA testing regimes require high removal efficiencies for some nonroad applications. These standards raise the bar for filter performance and can shorten product life cycles.
- Material cost shocks: 2024 saw material cost increases in key media inputs; a 15% price uptick in glass microfiber (driven by borosilicate production constraints) is indicative of recurring volatility that must be modeled into product costing and contract terms.
- Technology bottlenecks and opportunities: While coalescing elements remain core, polymer membrane technologies face challenges meeting ultra‑low water thresholds demanded by future regulations (e.g., Euro 7‑era specifications). Conversely, innovations in sensor/electronics are creating differentiation opportunities for suppliers that can deliver prognostics alongside filtration.
- Market concentration: The market exhibits moderate concentration among the top suppliers, which has implications for negotiating leverage and the speed of innovation diffusion. Our concentration analysis and CRx metrics are included in the full report.
Action checklist for 2026 — what each stakeholder should do next
- OEM product and systems engineering: Commission accelerated validation cycles for separators under expected fuel blend and contamination cases; prioritize modular designs that ease upgrades to meet tightening standards.
- Tier‑1 suppliers: Fast‑track co‑development agreements with membrane and sensor specialists; run cost‑to‑serve analyses for integrated assemblies versus component-only sales.
- Fleet operators and LCV/HCV buyers: Insist on in‑service water‑detection reporting and align warranties to demonstrable separator performance; consider retrofit campaigns where risk exposure is highest.
- Procurement: Introduce multi‑year supply agreements with pass‑through cost mechanisms and develop dual‑sourcing for high‑risk media categories.
- Private equity / strategic investors: Target bolt‑on opportunities where proprietary media or sensor IP can be combined with scale operations to improve margins and accelerate adoption in large OEM pipelines.
Risk scenarios and contingency planning
In addition to the base forecast (5.02% CAGR), the report models three scenario paths: a regulatory‑tightening scenario that accelerates adoption and raises average selling prices; a raw‑material shock scenario that compresses supplier margins and favors vertically integrated players; and a technology disruptive scenario where a membrane breakthrough displaces incumbent media. Each scenario includes trigger indicators and a recommended tactical playbook for fast response.
How PW Consulting’s analysis translates to boardroom decisions
Executives use this briefing to prioritize capital allocation, define supplier qualification criteria, and align product roadmaps with compliance timelines. The combination of bottom‑up sizing, scenario planning, supplier scorecards and a pragmatic procurement playbook provides the evidence base required to: (a) green‑light R&D investments, (b) renegotiate nominations with OEMs, and (c) execute M&A or partnership moves with a defensible valuation thesis.
Next steps — gaining access to the full intelligence
This article is a strategic preview designed to surface the analysis, implications and actionable pathways that PW Consulting delivers. It intentionally omits the full split‑level tables and proprietary datapacks (regional, vehicle‑type and component breakdowns) to preserve the commercial value of the dataset. Subscribers and clients receive the complete quantitative appendices, supplier due‑diligence files, and bespoke scenario modelling templates that are essential for executing the 2026 plays outlined above.
To obtain the full Worldwide Automotive Water Separation System Market report, detailed vendor scorecards, and an executive briefing tailored to your organisation’s role in the value chain, please contact PW Consulting or visit our research portal for subscription and advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Water Separation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Paint Booth Market to grow from USD 855.0 Million in 2025 to USD 1,254.45 Million by 2032 at a 5.65% CAGR
By pmarketresearch, 2026-07-15
Automatic Paint Booth Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting's latest market research — Automatic Paint Booth Market: 2026–2032 Strategic Outlook — provides an executive-grade, actionable intelligence package designed to shape capital allocation, procurement, and product strategy for industrial manufacturers, body shops, OEM paint shops, and private equity investors entering the space in 2026. Drawing on an evidence base that spans the 2020–2025 historical period and a robust forecast horizon of 2026–2032, the report frames near-term tactical choices within a long‑range view of demand growth, regulatory pressure, and technology adoption.
Automatic Paint Booth Market
Market trajectory at a glance
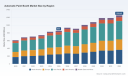
Using 2025 as the base year, PW Consulting’s model shows the global automatic paint booth market expanded from USD 612.45 Million in 2020 to USD 855.0 Million in 2025. Our scenario-driven forecast projects continued expansion through 2032, reaching approximately USD 1,254.45 Million by the end of the forecast period (2026–2032 CAGR: 5.65%). These headline numbers reflect a balancing of cyclical capital expenditure patterns, accelerating automation adoption in higher-volume segments, and the capital intensity of regulatory and sustainability-driven upgrades that are reshaping buying criteria.
Automatic Paint Booth Market
Important nuance: the 2026–2032 path is not linear — the model embeds near-term variability driven by macroeconomic cycles, supply-chain friction (notably steel and specialized filtration media pricing), and a rapid pivot toward waterborne coatings in many end-markets. PW Consulting’s forecast therefore provides both point estimates and alternative scenarios to support contingency planning and capital phasing decisions.
Automatic Paint Booth Market
Why 2026 is a tipping point for procurement and capex
- Regulatory and compliance inflection: Enforcement and guidance under OSHA (29 CFR 1910.107) and EPA NESHAP Subpart HHHHHH are tightening expectations for ventilation, fire-safety construction, and filter capture efficiency. Buyers must now embed compliance validation into procurement specifications rather than treating it as an add-on.
- Coatings technology transition: The industry-wide shift to waterborne coatings increases the importance of precise climate control (typical targets in the sector span 18–25°C and 50–65% relative humidity). Booth selection and HVAC design must be assessed against these operational envelopes to avoid rework costs and warranty exposure.
- Automation and flexibility: Demand is bifurcating: high-throughput OEM and contract finishers prioritize multi-stage automated solutions and robotic integration, while smaller repair and specialty shops favor modular, energy-efficient booths that optimize floor space and TCO.
- Input-price volatility: Raw-material swings — steel and filtration media in particular — are material to manufacturing margins and should inform contract terms, inventory strategies, and supplier selection.
Practical strategic imperatives for 2026
For executives making procurement, manufacturing, or investment decisions in 2026, the PW Consulting report recommends a prioritized, pragmatic playbook:
- Adopt a phased-capex approach: Break large paint-shop projects into validated modules. Prioritize investments that unlock capacity or compliance quickly (e.g., filtration upgrades, climate control retrofits) and defer lower‑ROI automation stages until throughput is proven.
- Require end-to-end TCO metrics in RFPs: Move beyond purchase price — require bidders to provide lifecycle energy consumption, filter replacement schedules and costs, expected production throughput under waterborne coatings, and compliance validation documentation.
- Insist on interoperability and upgrade paths: Specify modular control architectures and open-communication standards (for robotics and IoT) so that initial systems can host future automation or process controls without full replacement.
- Hedge supply‑chain exposure: Secure multi-year or indexed contracts for critical inputs where possible; evaluate regional sourcing and pre-formed kits to reduce lead times and exposure to raw-material spikes.
- Test before scale: Run pilot installations or staged proofs-of-concept to validate waterborne-coating performance and climate-control regimes at production scale before committing to full-array automation.
- Quantify sustainability as an economic lever: Model energy savings and emissions reductions from LED curing, heat-recovery HVAC, and optimized booth airflow — these often produce measurable operating-cost improvements that shorten payback periods.
- Factor in aftermarket and service economics: Prioritize vendors offering fast local service, parts availability, and remote diagnostics; downtime at finishing stages has outsized operational impact.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three firms hold a meaningful but not dominant share of revenue, and the top five account for roughly half of market receipts. This dynamic creates room for both incumbent expansion and nimble regional or specialist providers to win deals — particularly where local code knowledge, rapid service, and tailored engineering matter.
- Garmat USA (USA) — Strength: code-compliant automotive and heavy-duty repair booths with strong regional support and an emphasis on airflow and safety. Best for repair shops prioritizing regulatory alignment and proven designs.
- Accudraft Paint Booths (SAIMA of North America) (USA) — Strength: high-production automotive and commercial booths plus prep and finishing solutions accumulated over decades; strong option for high-throughput body shops seeking integrated systems.
- Global Finishing Solutions (GFS) (Osseo, WI) — Strength: wide portfolio spanning industrial, automotive, and automated booths including multi-stage options; attractive where turnkey finishing lines and automation are required.
- Blowtherm USA (USA) — Strength: energy-efficient systems with demonstrable case-study outcomes in quality and sustainability; a vendor to watch where energy costs and emissions goals drive procurement.
- RTT Finishing Solutions (Rockwall, TX) (USA) — Strength: engineering focus across diverse applications; recent leadership changes signal an integration phase following acquisition, which may affect vendor strategy and go-to-market execution.
- Spray‑Tech (Rialto, CA) (USA) — Strength: custom-engineered, high-performance booths suited to specialized auto, aerospace, and manufacturing applications where bespoke solutions are required.
- Taikisha USA (Troy, MI) (USA) — Strength: downdraft robotic paint spray booths with a focus on automotive manufacturing environments; best-in-class for large OEM paint shops seeking scale and integration.
- Dürr Systems (Germany, global) — Strength: world-leading automated paint-shop and robotic application technology; strong capability for future-proofed, flexible paint lines — evidenced by public showcases of “paint shop of the future” solutions.
- Marathon Finishing Systems (USA) — Strength: high-performance booths for automotive, industrial, and aerospace customers; useful where performance and reliability are prioritized.
Recent vendor moves in 2025–2026 illustrate the market dynamics: executive appointments following acquisitions, case-study installations demonstrating sustainability and efficiency gains, and vendor showcases of flexible, future-ready paint-shop architectures. These developments highlight two trends: consolidation among service-capable suppliers and a marketing pivot toward sustainability and automation as primary differentiators.
What the PW Consulting report delivers — operational, actionable content
Beyond headline forecasts, the report is explicitly built for practitioners who must convert insight into action in 2026. Key deliverables include:
- Decision frameworks for retrofit vs. greenfield projects, with stepwise capex phasing and break‑even timelines.
- Vendor scorecards and RFP templates calibrated to regulatory compliance, energy consumption, automation readiness, and aftermarket service KPIs.
- Detailed TCO models that quantify energy, maintenance, filter replacement, labor, and downtime exposures under alternative coating regimes (including waterborne scenarios).
- Scenario planning modules for supply‑chain disruption and raw-material price shocks, with mitigation playbooks.
- Regulatory compliance checklists aligned to OSHA and EPA NESHAP requirements and practical verification steps for procurement and acceptance testing.
- Integration roadmaps for staged automation, digital monitoring, and remote diagnostics to protect optionality while reducing upfront risk.
Note: to preserve commercial sensitivity and to guide decision-makers to validated data sources, this public briefing intentionally omits granular splits by region, booth type, and application — those detailed segmentations and vendor-level market share matrices are available in the full report.
Implications for buyers, OEMs, and investors in 2026
- Buyers: Treat 2026 as an inflection year to reframe booth acquisitions as long-lived production assets with embedded software, HVAC, and filtration lifecycles. Require warranty and service clauses that reflect modern operating profiles (waterborne coatings, robotic processes).
- OEMs / Contract Finishers: Prioritize modular automation that can be scaled with demand, and negotiate supplier commitments for upgrades and spare-part availability to reduce time-to-revenue during ramp phases.
- Investors / PE: Look for targets with strong regional service footprints, proprietary installation methodology, and differentiated energy-efficiency offerings — these attributes materially improve exit multiples in this market.
Next steps
PW Consulting’s Automatic Paint Booth Market: 2026–2032 Strategic Outlook is designed to be a working tool for the C-suite, procurement teams, and investors. The full report contains the granular segmentation, vendor share matrices, and downloadable decision tools referenced above. For organizations planning capex or M&A in 2026, early engagement with PW Consulting will enable customized scenario modeling and a tailored vendor selection process that accelerates implementation while controlling compliance and operating risk.
Issued by: PW Consulting — Advanced Industry Practice, Automatic Paint Booth Markets
For detailed analysis of this topic, please visit the official page: Automatic Paint Booth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Gracey Curette Market Poised for 6.85% CAGR in 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Gracey Curette Market: Strategic Insights for 2026 Decision‑Making
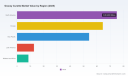
PW Consulting’s new market study on the Worldwide Gracey Curette Market (base year 2025; historical period 2020–2025; forecast 2026–2032) equips healthcare executives, procurement leads, product R&D heads, and private equity investors with a compact, decision‑grade synthesis for 2026 planning. The market is experiencing steady expansion — growing from roughly USD 154.4 Million in 2020 to USD 215.0 Million in 2025, and projected to reach over USD 341.8 Million by 2032 at a compound annual growth rate (CAGR) of approximately 6.85%. These macro dynamics create a window of strategic opportunity for players across the value chain, while rewarding disciplined competitive moves and operational rigor.
Worldwide Gracey Curette Market
Executive summary — Why this report matters for 2026
-
Actionable foresight for near‑term capital allocation: The report translates market momentum into tactical recommendations for procurement cadence, inventory sizing, and CAPEX for instrument processing infrastructure.
Worldwide Gracey Curette Market -
Commercial playbook for growth: It outlines go‑to‑market options — from premium single‑use adjuncts and coated/treated instruments to service models (e.g., sharpening, subscription) — calibrated to 2026 demand signals.
Worldwide Gracey Curette Market -
Risk and compliance readiness: We map regulatory, sterilization, and standardization touchpoints that materially affect time‑to‑market, buyer preferences, and tender outcomes.
-
M&A and partnership lens: The study identifies structural features that make targets attractive for roll‑up strategies, strategic alliances, and OEM supply agreements.
What’s inside the report — practical, commercially oriented content
-
Market sizing and trend synthesis (historical and forecast) with scenario analysis calibrated for 2026 decision horizons.
-
Demand driver mapping and buyer persona insights for private dental practices, institutional buyers, and academic/research segments.
-
Regulatory and standards matrix (including implications of device classification, sterilization requirements and reimbursement coding) that materially influence procurement and product design.
-
Competitive benchmarking and supplier scorecards emphasizing product attributes, price‑performance, and service models.
-
Commercial and operational playbooks: supplier selection criteria, procurement RFP templates, and sterilization throughput planning for central sterile services.
-
Investment thesis and M&A screening framework, including diligence checklists focused on manufacturing quality, IP (coatings, heat treatments), and aftermarket services.
-
Key performance indicators for procurement and clinical adoption, plus a prioritized 100‑day plan for market entry or expansion.
Market dynamics shaping decisions in 2026
Several non‑market forces set the guardrails for strategic action next year. From a regulatory perspective, Gracey curettes remain a low‑barrier device class in key jurisdictions, which lowers time‑to‑market risk but raises the bar on supplier quality and standards compliance as differentiators. Practically, these instruments are classified in the U.S. regulatory framework in a manner that exempts many from premarket notification, yet purchasers and clinicians demand conformity to internationally recognized standards for surgical instruments. Sterilization requirements — routine steam autoclaving at validated cycles — create operational constraints for clinics and centralized sterile processing facilities and therefore influence preferences for instrument finish, metallurgy, and lifecycle costing.
Reimbursement coding for periodontal procedures also subtly affects adoption velocity: where periodontal scaling and root planing are well‑reimbursed, clinical throughput and instrument replacement cadence accelerate. Material advances in instrument metallurgy and surface treatments influence total cost of ownership; instruments that sustain edge integrity longer reduce sharpening cycles and reprocessing costs, an attractive proposition for high‑volume users.
Demand vectors and innovation priorities
Clinician adoption is being driven by a mix of clinical efficacy, ergonomics, and lifecycle cost economics. Practitioners are increasingly valuing instruments that reduce hand fatigue, improve access to subgingival anatomy, and retain sharpness between sharpening cycles. These performance attributes translate into two commercial imperatives for 2026:
-
Design and materials innovation: investments in coatings, heat treatments, and handle ergonomics remain high‑leverage areas where suppliers can achieve premium pricing or improved share in high‑volume accounts.
-
Service differentiation: bundled offerings that combine clinical education, on‑site sharpening or refurbishment, and predictable replenishment contracts are becoming decisive in procurement negotiations.
For executives, prioritizing product pipelines that demonstrably lower clinical effort and lifecycle costs will have outsized returns in the next 12–24 months.
Competitive landscape — positioning and implications
The market exhibits meaningful product innovation pockets alongside a fragmented supplier base. A few observations on main competitive archetypes and strategic implications:
-
Premium innovators: Companies offering advanced edge technologies, controlled heat treatment processes, and micro‑geometry instruments compete on clinical superiority and clinician preference. These suppliers can target higher ASPs and specialty institutional channels.
-
Ergonomic and service‑oriented suppliers: Firms that emphasize ergonomic handles, lightweight construction, and sharpening longevity focus on workflow savings and clinician comfort — attributes that resonate with high‑throughput clinics.
-
Broadline players: Manufacturers that position Gracey curettes within a wider periodontal instrument portfolio compete on procurement convenience and bundled purchasing discounts.
Representative companies profiled in the study include established and specialized names across North America and Europe. Profiles summarize product portfolios, unique technology claims (e.g., coatings, heat treatments, hollow handles, color‑coding), and channel focus — information oriented to help buyers and investors prioritize partners or acquisition targets. Executive teams should evaluate suppliers not only on product specs but on quality systems, sterilization compatibility, and aftermarket service capability.
Market concentration metrics underscore an open landscape: the top three players hold a limited single‑digit to low‑double‑digit share of the market, and the top five account for a modest increase over that. In practice, this means there is runway for consolidation, vertical integration of sharpening/refurbishment services, and for well‑funded entrants to capture niche leadership through focused innovation.
Operational levers for 2026
-
Procurement optimization — adopt a supplier scorecard that weights clinical performance, sterilization compatibility, and lifecycle cost rather than headline unit price alone.
-
Inventory and sterilization planning — align procurement with sterilization throughput capabilities; higher edge retention reduces inventory and reprocessing cycles.
-
Clinical training and adoption programs — invest in KOL partnerships and hands‑on training to accelerate clinician preference for new instrument geometries.
-
Service model experiments — pilot subscription or sharpening‑as‑a‑service models in representative markets to validate CAC and recurring revenue potential.
-
M&A and partnership focus — target small to mid‑sized specialists with proprietary coatings or heat‑treatment know‑how, and assets that can be quickly integrated into existing distribution footprints.
How to use this report for decisive action in 2026
Executives should treat the study as a practical toolkit for immediate and medium‑term choices. For procurement teams, the report supplies negotiation levers and an RFP template. For product and R&D leaders, it prioritizes innovation themes that influence buying decisions next year (edge retention, coated surfaces, ergonomic grips). For investors and corporate development teams, the study provides a screening rubric to identify attractive consolidation targets and cliffs where regulatory or standards compliance creates entry barriers.
We emphasize that while this release highlights macro sizing and growth (including the 2025 base and the near‑term 2026 outlook), the full report contains the granular subsegment and regional intelligence — detailed growth trajectories by market channel, product type, and region — necessary to execute targeted go‑to‑market plans and deal diligence. That detailed segmentation data is intentionally reserved for the full report to ensure tailored and actionable engagement.
Methodology and data integrity
The analysis is grounded in a multi‑source methodology: longitudinal market tracking (2020–2025), primary interviews with clinicians, procurement officers, and manufacturers, audited company disclosures, sterilization and standards documentation, and scenario‑based forecasting through 2032. Financials are presented in constant 2025 USD (Million) to ensure comparability. Forecasting incorporates sensitivity to reimbursement dynamics, clinical procedure volume scenarios, and technology substitution curves.
Conclusion — next steps for leaders
As the Gracey curette market expands at an approximate 6.85% CAGR, 2026 represents a pivotal year to convert favorable macro momentum into defensible commercial advantages. Whether the priority is optimizing clinical workflows, upgrading procurement to value‑based models, or executing consolidation plays, PW Consulting’s study provides the operational scaffolding leaders need to act with confidence.
For the full dataset, granular segment and regional breakdowns, supplier scorecards, and the 100‑day execution plan, access the complete Worldwide Gracey Curette Market report on our website or contact PW Consulting’s research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Gracey Curette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Baggage Packaging Service Market to Reach USD 1,453.93 Million by 2032, Expanding at a 6.51% CAGR
By pmarketresearch, 2026-07-15
Worldwide Baggage Packaging Service Market — Strategic Preview for 2026 Decision-Makers
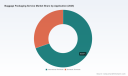
PW Consulting’s latest market intelligence on the Worldwide Baggage Packaging Service market delivers an executive-grade synthesis designed to inform corporate strategy, procurement, sustainability programs, and M&A diligence in 2026. With a clearly defined base year of 2025 and a focused forecast horizon through 2032, this study converts granular operational realities into boardroom-ready strategic options. The market is on a sustained growth trajectory — our model shows a mid-single-digit compound annual growth rate (CAGR) of 6.51% across the forecast window, moving total industry revenue from a 2025 baseline to an expected market size approaching USD 1.45 billion (Million USD unit) by 2032.
Worldwide Baggage Packaging Service Market
Why this report matters for 2026 planning
-
Timing: Airlines, airport operators, and vendor partners are revising service contracts and capital plans in 2026. The market’s predictable growth and concentration profile create a narrow window for tactical moves — whether to secure capacity, lock in technology licensing, or accelerate sustainable-material transitions.
Worldwide Baggage Packaging Service Market -
Investment clarity: The report translates revenue trajectories into cash-flow implications for service operators and OEMs of wrapping equipment, enabling CFOs and strategy leads to stress-test investment cases against realistic adoption curves and operational KPIs.
Worldwide Baggage Packaging Service Market -
Regulatory foresight: An integrated compliance playbook anticipates the operational impact of mounting packaging Extended Producer Responsibility (EPR) rules and state-level mandates in major markets, enabling preemptive cost allocation and supplier negotiations.
-
Competitive playbook: We map competitive strengths and recent product moves to expose where premium service differentiation (technology, sustainability, and traceability) will command margin premium vs. where scale and network density remain decisive.
High-level market dynamics — what’s driving growth and disruption
-
Demand-side tailwinds: Travel recovery, greater baggage protection expectations, and heightened hygiene considerations continue to drive per-bag uptake of protection services in terminals and intermodal hubs. Our scenario framework quantifies adoption under conservative, base, and upside travel scenarios so clients can align capacity investments with risk appetite.
-
Supply-side pressures: The sector remains dependent on polymer films (primarily LDPE and LLDPE). Volatility in plastics input prices is material — for example, US producer-price indices for plastics films remain elevated through early 2026 — creating near-term cost push that operators must either absorb, hedge, or pass through via pricing models.
-
Regulatory closure: EPR regimes now span multiple US states and expanding international frameworks, shifting end-of-life costs onto producers and service providers. Operators who integrate recyclable or biodegradable film options early will mitigate fee exposure and gain procurement leverage with airports setting sustainability targets.
-
Technology and automation: Innovations in automated wrapping platforms, digital tracking (including NFC-enabled solutions), and material-efficiency improvements are changing unit economics. New machine generations reduce film consumption per bag and speed throughput — critical where labor cost or terminal dwell constraints limit manual service rollouts.
Competitive landscape — synthesis and strategic implications
-
Market structure: The baggage packaging service market is moderately concentrated. The top three incumbent groups account for a meaningful share of revenue, while the top five consolidate a clear majority. That structure creates differentiated dynamics: large operators secure airport concessions and roll out equipment networks quickly; mid-tier players compete on local presence, specialized service packages, or sustainability credentials.
-
Profiles to watch:
-
Safe Bag S.p.A. (TraWell) — a technical and network leader in airport baggage protection and tracing. Their recent product introduction of a next-generation automatic wrapping platform includes NFC-based digital tracking and a material-efficiency lift that reduces film consumption per bag — a commercially significant improvement for both cost and sustainability KPIs.
-
Secure Wrap (US) — a market-leading operator in TSA-authorized services, notable for tamper-evident offerings and operational conveniences such as complimentary rewraps after security inspection. Their product and service positioning make them a valuable partner for carriers and airport retail programs.
-
BagWrap, Wrap N’ Fly, TrueStar Group (Wrap and Fly), Seal & Go, Encalm Enwrap, and Excess Baggage Company — collectively they demonstrate two strategic playbooks: (1) franchise/network expansion with standardized equipment and rapid terminal deployment; and (2) differentiation via sustainability and local-market customization, including biodegradable film options and premium hygiene claims.
-
-
Recent strategic moves: Several vendors have moved from pilot to commercial roll-out of sustainable films and digitally-enabled wrapping systems. A notable case is the introduction of an automated platform that integrates bag-level NFC tracking while reducing film consumption materially — the kind of capability that compresses operating cost per bag and supports product premiumization in high-traffic terminals.
Operational levers and commercial models we analyze
-
Contract structures: Per-bag fees, revenue-share concessions, and blended fixed-plus-variable agreements each trade off risk differently between airports, vendors, and airlines. Our report models profit and cash-flow outcomes for each arrangement across occupancy and traffic scenarios.
-
Cost pass-through frameworks: We provide elasticities and practical clauses to incorporate material-price volatility and EPR fee exposures into long-term supply contracts.
-
Capex and fleet planning: For airport retailers and equipment providers, we deliver a deployment prioritization matrix that links terminal throughput, dwell time, and labor availability to equipment spec choices (manual, semi-automatic, fully automatic).
-
Sustainability transition roadmap: A decision tree and supplier-selection scorecard evaluate trade-offs between 100% recyclable films, biodegradable options, and mixed-material strategies — including life-cycle and end-of-life cost modeling under emerging EPR regimes.
Risk vectors — what to watch in 2026
-
Policy shock: Accelerated or broadened EPR laws could materially change the cost profile for operators who retain end-of-life responsibility for films. We quantify the sensitivity of unit economics to incremental per-ton fees phased in across state and international programs.
-
Input-price inflation: Elevated polymer film prices compress gross margins unless operators can lock supply or pass through costs. Hedging and strategic vendor partnerships are now part of best-practice procurement playbooks.
-
Technology adoption risk: Early movers in automatic wrapping and digital tracking gain operating leverage; late adopters risk margin erosion and concession loss. Our deployment scenarios indicate payback periods under different traffic-density assumptions.
-
Reputational/consumer risk: Sustainability claims must be verifiable. Operators who rush to biodegradable labeling without chain-of-custody evidence will face reputational penalties when airports and consumers demand proof.
What the PW Consulting report delivers (practical, actionable modules)
-
Market model and scenarios: A transparent financial model with base, upside, and downside demand curves and a stress-tested P&L for operators and equipment OEMs.
-
Supplier benchmark: Capability matrices, go-to-market approaches, and a comparative rubric that surfaces where to partner, acquire, or compete.
-
Procurement playbook: Contract templates, pass-through mechanisms, and negotiation tactics specific to airports, concession managers, and airlines.
-
Sustainability and compliance toolkit: EPR impact assessment, transition roadmap to recyclable/biodegradable films, and sample reporting templates for regulator and corporate sustainability teams.
-
M&A and partnership targets: Screening criteria and shortlists for strategic buyers seeking scale, technology, or geographic footholds — accompanied by valuation sensitivities.
-
Primary research appendix: Interview summaries with airport procurement leads, operators, and polymer suppliers, plus methodology transparency for in-market intelligence.
How leading organizations should act in 2026
-
Airports and concessionaires: Prioritize concession structures that align incentives for sustainability and throughput efficiency. Incorporate outcome-based KPIs (e.g., film consumption per bag, customer satisfaction scores) into contracts to capture upside from technology-led efficiency gains.
-
Operators and franchisees: Accelerate pilots of automatic platforms in high-density terminals and secure exclusive or semi-exclusive equipment arrangements where footfall justifies capex. Leverage digital tracking to create ancillary revenue streams (lost-luggage proof-of-service, branded protection bundles).
-
Buyers and private equity: Target assets that combine network density with demonstrable intellectual property in packaging efficiency or digital traceability. Our valuation playbook shows where multiples expand for technology-enabled operators versus purely local service providers.
-
Material suppliers and OEMs: Invest in verified recyclable or biodegradable materials and quantify end-of-life downstream costs transparently; early certification will be a competitive advantage as EPR fees mature.
PW Consulting’s Worldwide Baggage Packaging Service Market report is intentionally designed as a strategic instrument: it delivers the analytical depth required to make 2026 decisions with confidence while reserving proprietary segmentation tables and raw datasets for report subscribers. Senior executives and procurement teams who need the complete dataset, modeling workbook, and supplier scorecards are invited to access the full report on our website or contact our research desk for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Baggage Packaging Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Proctoscope Market to Expand at a 5.48% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Proctoscope Market: Strategic Imperatives for 2026
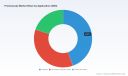
PW Consulting’s latest market study, Worldwide Proctoscope Market (Base Year 2025, Forecast 2026–2032), reframes how executives should think about capital allocation, product strategy, and regulatory readiness in the anorectal diagnostic and procedural device space. Built on a robust historical series (2020–2025) and a granular scenario-driven forecast, the study projects continued expansion of the total market from a 2025 baseline of USD 245.5 Million to an expected USD 357.12 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 5.48% over the forecast window. For decision-makers preparing 2026 operating plans and three- to five-year roadmaps, the report converts that headline trajectory into concrete choices around portfolio prioritization, channel economics, and M&A targeting.
Worldwide Proctoscope Market
Why 2026 Is a Turning Point
-
Macro stability with tactical inflection: After steady recovery through 2020–2025, the market’s projected growth entering 2026 is neither an episodic rebound nor runaway expansion—it is sustained, measurable growth that rewards timely tactical moves rather than late-stage catch-up investments.
Worldwide Proctoscope Market -
Shifting procurement calculus: Hospitals and ambulatory providers are recalibrating capital vs. consumables trade-offs (reusable instrumentation, disposables, sterilization capex, and service contracts). The 2026 budget cycle is the practical window for capitalizing on new purchasing behaviors.
Worldwide Proctoscope Market -
Regulatory and reimbursement clarity: With proctoscopes categorized as Class I devices under FDA rules (510(k) exempt) and standardized reimbursement pathways under CPT codes, 2026 is optimal for scaling across payor- and compliance-constrained settings—provided product and process controls meet ISO and CDC expectations.
Market Trajectory: Numbers That Inform Strategy
Understanding magnitude and momentum is foundational to prioritization. Our report synthesizes the historical series and multiple forecast scenarios to derive the central projection: total market value growing from USD 245.5 Million in 2025 to USD 266.19 Million in 2026, continuing to a base-case endpoint of USD 357.12 Million in 2032 (5.48% CAGR). These figures enable CFOs and strategy leads to model three things with confidence in 2026 planning cycles: expected topline elasticity from volume vs. ASP shifts; the payback horizon of sterilization and reprocessing investments; and the sizing of attainable share for new product launches or geographic expansions.
Strategic Implications for Key Stakeholders
-
OEMs and product teams: Prioritize modular product architectures that can sit across acute-care and ambulatory channels. Devices optimized for rapid turnover in ambulatory settings (single-use convenience) and low-TCO reusable platforms for higher-acuity centers present distinct go-to-market plays. Our analysis quantifies the breakeven points and margin sensitivity for both approaches.
-
Hospital procurement and IDNs: Reassess total cost of ownership (TCO). The report’s procurement playbook includes templates to compute sterilization costs (autoclave up to 134°C for medical-grade AISI 316L instruments), service contract design, and capital crediting—tools that materially change 2026 acquisition decisions.
-
Investors and M&A teams: The market’s moderate concentration (CR3 and CR5 metrics are highlighted in the report) signals pockets of consolidation opportunity. We pair value-tree analysis with transaction comparables to identify targets whose unit economics deliver rapid margin lift when integrated into a broader endoscopy or single-use disposables portfolio.
Competitive Landscape: What to Watch in 2026
The proctoscope category blends established players with niche innovators. Our competitive landscaping combines product-level benchmarking, coverage of distribution strategies, and technology roadmaps to outline realistic competitive moves for 2026.
-
Olympus Corporation (Tokyo): A legacy endoscopy leader with proven rigid proctoscope platforms. Strengths include clinical credibility and installed-base integration with imaging systems. Strategic choices revolve around modular optics and service models that extend lifetime value.
-
Karl Storz SE & Co. KG (Tuttlingen): Known for reusable systems with integrated optics and material-grade engineering. The 11620 family is emblematic of product durability; Karl Storz’s engineering focus positions it to defend high-acuity hospital share while selectively entering single-use adjacencies.
-
Richard Wolf GmbH (Knittlingen): Focused on direct-visualization rigid instruments, Richard Wolf competes on precision and surgical ergonomics. Differentiation opportunities include procedure-specific instrument sets and bundled service agreements.
-
PENTAX Medical (HOYA Corporation, Tokyo): Leverages endoscopy R&D to supply rigid proctoscopes integrated into colorectal portfolios. Bundling with imaging and documentation workflows is a natural competitive axis.
-
Baxter International / Welch Allyn (Deerfield, Illinois): A prominent supplier of single-use solutions—KleenSpec is a direct play on infection control and outpatient convenience. The business case for disposables depends on sterile-supply economics and reimbursement dynamics.
-
HEINE Optotechnik (Herrsching): Niche strength in illumination with LED-enabled proctoscope sets. Small-product differentiation in optics and light management can unlock outsized clinical preference in procedure-heavy centers.
-
B. Braun Melsungen AG (Melsungen): Stainless steel platforms like the 720 series emphasize surgical-grade reliability. Their global distribution and service footprint make them a credible partner in perioperative environments.
-
Wallach Surgical Devices (Trumbull): Offers both disposable and reusable options and is strategically placed to serve outpatient and gynecologic crossover demand. Their flexible product mix is an advantage in markets shifting toward ambulatory care.
Across competitors, our benchmarking highlights three linked defensive plays for incumbents and entrants alike: (1) sterilization and reprocessing cost leadership; (2) integrated imaging/IT compatibility; and (3) tailored channel economics for ambulatory surgery centers (ASCs). The full report contains a promoter-detractor matrix and capability heatmap for each named firm.
Regulatory, Clinical and Operational Dynamics
-
Regulation: With proctoscopes classified as Class I devices and often 510(k) exempt under the FDA product code FDT, regulatory entry is comparatively accessible. This lowers technical barriers but increases the importance of clinical validation and quality-system differentiation (ISO 13485 compliance recommended for export-readiness).
-
Reimbursement: Proctoscopy procedures fall within established CPT code ranges with average Medicare payments that make outpatient conversion economically attractive for many providers. Our report provides a mock reimbursement model that sensibly aligns payer mix and utilization assumptions for 2026 budgeting.
-
Infection prevention and materials: AISI 316L stainless steel remains the clinical standard for reusable devices given autoclave compatibility at steam sterilization temperatures; CDC and ISO sterilization guidance define the operational envelope. For reusable products, stringent high-level disinfection protocols are non-negotiable.
What the Report Delivers (Actionable Components)
-
Market-sizing and scenario models with transparent assumptions and sensitivity toggles for ASP, utilization, and channel mix.
-
Procurement playbooks and TCO calculators for hospital networks and ASCs to run competing buy/rent/consumable scenarios.
-
Competitor profiles and a capability heatmap including product portfolios, service models, and IP positions.
-
Regulatory and clinical compliance checklists tailored to key export markets and private-payor environments.
-
M&A scouting list with financial trigger metrics and integration risk assessments—prioritized for 2026 outreach.
-
Commercial go-to-market playbooks focused on clinician adoption, distributor economics, and e-procurement integration for 2026 launches.
Action Steps for 2026 Planning
-
For OEMs: Lock in one pilot health system for a bundled offering that combines instrument, sterilization service, and digital documentation—use 2026 to prove the ROI case with real utilization data.
-
For hospital systems: Run parallel TCO scenarios for reusable vs. disposable pathways in your 2026 capital planning cycle; incorporate sterilization capacity and staff training costs into the decision gate.
-
For private equity and corporate development: Target sub-scale manufacturers with proprietary optics or cost-advantaged disposables; 2026 is a year to accelerate diligence on targets that can be scaled through sales-channel consolidation.
Next Steps and How to Access the Full Intelligence
This executive briefing is designed as a strategic “trailer”: it conveys the market’s shape, the competitive fault-lines, and the practical choices that ought to inform 2026 budgets. To preserve the tactical utility of our benchmarking and the proprietary segmentation work that underpins targeted decisions (regional adoption curves, application-level economics, and product-type breakouts), detailed splits and downloadable models are available exclusively in the full report package.
For procurement teams, corporate development groups, and clinical innovation leaders preparing 2026 action plans, the full report provides the calibrated templates, data models, and vendor-level playbooks necessary to convert the market’s 5.48% CAGR and projected growth into executable advantage.
Contact PW Consulting to request the complete Worldwide Proctoscope Market report and obtain access to the interactive models, annexes, and vendor dossiers that will operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Proctoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com