

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Proctoscope Market to Expand at a 5.48% CAGR Through 2032

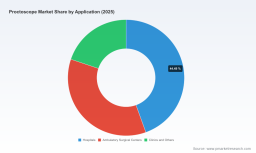
Worldwide Proctoscope Market: Strategic Imperatives for 2026
PW Consulting’s latest market study, Worldwide Proctoscope Market (Base Year 2025, Forecast 2026–2032), reframes how executives should think about capital allocation, product strategy, and regulatory readiness in the anorectal diagnostic and procedural device space. Built on a robust historical series (2020–2025) and a granular scenario-driven forecast, the study projects continued expansion of the total market from a 2025 baseline of USD 245.5 Million to an expected USD 357.12 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 5.48% over the forecast window. For decision-makers preparing 2026 operating plans and three- to five-year roadmaps, the report converts that headline trajectory into concrete choices around portfolio prioritization, channel economics, and M&A targeting.
Worldwide Proctoscope Market
Why 2026 Is a Turning Point
-
Macro stability with tactical inflection: After steady recovery through 2020–2025, the market’s projected growth entering 2026 is neither an episodic rebound nor runaway expansion—it is sustained, measurable growth that rewards timely tactical moves rather than late-stage catch-up investments.
Worldwide Proctoscope Market -
Shifting procurement calculus: Hospitals and ambulatory providers are recalibrating capital vs. consumables trade-offs (reusable instrumentation, disposables, sterilization capex, and service contracts). The 2026 budget cycle is the practical window for capitalizing on new purchasing behaviors.
Worldwide Proctoscope Market -
Regulatory and reimbursement clarity: With proctoscopes categorized as Class I devices under FDA rules (510(k) exempt) and standardized reimbursement pathways under CPT codes, 2026 is optimal for scaling across payor- and compliance-constrained settings—provided product and process controls meet ISO and CDC expectations.
Market Trajectory: Numbers That Inform Strategy
Understanding magnitude and momentum is foundational to prioritization. Our report synthesizes the historical series and multiple forecast scenarios to derive the central projection: total market value growing from USD 245.5 Million in 2025 to USD 266.19 Million in 2026, continuing to a base-case endpoint of USD 357.12 Million in 2032 (5.48% CAGR). These figures enable CFOs and strategy leads to model three things with confidence in 2026 planning cycles: expected topline elasticity from volume vs. ASP shifts; the payback horizon of sterilization and reprocessing investments; and the sizing of attainable share for new product launches or geographic expansions.
Strategic Implications for Key Stakeholders
-
OEMs and product teams: Prioritize modular product architectures that can sit across acute-care and ambulatory channels. Devices optimized for rapid turnover in ambulatory settings (single-use convenience) and low-TCO reusable platforms for higher-acuity centers present distinct go-to-market plays. Our analysis quantifies the breakeven points and margin sensitivity for both approaches.
-
Hospital procurement and IDNs: Reassess total cost of ownership (TCO). The report’s procurement playbook includes templates to compute sterilization costs (autoclave up to 134°C for medical-grade AISI 316L instruments), service contract design, and capital crediting—tools that materially change 2026 acquisition decisions.
-
Investors and M&A teams: The market’s moderate concentration (CR3 and CR5 metrics are highlighted in the report) signals pockets of consolidation opportunity. We pair value-tree analysis with transaction comparables to identify targets whose unit economics deliver rapid margin lift when integrated into a broader endoscopy or single-use disposables portfolio.
Competitive Landscape: What to Watch in 2026
The proctoscope category blends established players with niche innovators. Our competitive landscaping combines product-level benchmarking, coverage of distribution strategies, and technology roadmaps to outline realistic competitive moves for 2026.
-
Olympus Corporation (Tokyo): A legacy endoscopy leader with proven rigid proctoscope platforms. Strengths include clinical credibility and installed-base integration with imaging systems. Strategic choices revolve around modular optics and service models that extend lifetime value.
-
Karl Storz SE & Co. KG (Tuttlingen): Known for reusable systems with integrated optics and material-grade engineering. The 11620 family is emblematic of product durability; Karl Storz’s engineering focus positions it to defend high-acuity hospital share while selectively entering single-use adjacencies.
-
Richard Wolf GmbH (Knittlingen): Focused on direct-visualization rigid instruments, Richard Wolf competes on precision and surgical ergonomics. Differentiation opportunities include procedure-specific instrument sets and bundled service agreements.
-
PENTAX Medical (HOYA Corporation, Tokyo): Leverages endoscopy R&D to supply rigid proctoscopes integrated into colorectal portfolios. Bundling with imaging and documentation workflows is a natural competitive axis.
-
Baxter International / Welch Allyn (Deerfield, Illinois): A prominent supplier of single-use solutions—KleenSpec is a direct play on infection control and outpatient convenience. The business case for disposables depends on sterile-supply economics and reimbursement dynamics.
-
HEINE Optotechnik (Herrsching): Niche strength in illumination with LED-enabled proctoscope sets. Small-product differentiation in optics and light management can unlock outsized clinical preference in procedure-heavy centers.
-
B. Braun Melsungen AG (Melsungen): Stainless steel platforms like the 720 series emphasize surgical-grade reliability. Their global distribution and service footprint make them a credible partner in perioperative environments.
-
Wallach Surgical Devices (Trumbull): Offers both disposable and reusable options and is strategically placed to serve outpatient and gynecologic crossover demand. Their flexible product mix is an advantage in markets shifting toward ambulatory care.
Across competitors, our benchmarking highlights three linked defensive plays for incumbents and entrants alike: (1) sterilization and reprocessing cost leadership; (2) integrated imaging/IT compatibility; and (3) tailored channel economics for ambulatory surgery centers (ASCs). The full report contains a promoter-detractor matrix and capability heatmap for each named firm.
Regulatory, Clinical and Operational Dynamics
-
Regulation: With proctoscopes classified as Class I devices and often 510(k) exempt under the FDA product code FDT, regulatory entry is comparatively accessible. This lowers technical barriers but increases the importance of clinical validation and quality-system differentiation (ISO 13485 compliance recommended for export-readiness).
-
Reimbursement: Proctoscopy procedures fall within established CPT code ranges with average Medicare payments that make outpatient conversion economically attractive for many providers. Our report provides a mock reimbursement model that sensibly aligns payer mix and utilization assumptions for 2026 budgeting.
-
Infection prevention and materials: AISI 316L stainless steel remains the clinical standard for reusable devices given autoclave compatibility at steam sterilization temperatures; CDC and ISO sterilization guidance define the operational envelope. For reusable products, stringent high-level disinfection protocols are non-negotiable.
What the Report Delivers (Actionable Components)
-
Market-sizing and scenario models with transparent assumptions and sensitivity toggles for ASP, utilization, and channel mix.
-
Procurement playbooks and TCO calculators for hospital networks and ASCs to run competing buy/rent/consumable scenarios.
-
Competitor profiles and a capability heatmap including product portfolios, service models, and IP positions.
-
Regulatory and clinical compliance checklists tailored to key export markets and private-payor environments.
-
M&A scouting list with financial trigger metrics and integration risk assessments—prioritized for 2026 outreach.
-
Commercial go-to-market playbooks focused on clinician adoption, distributor economics, and e-procurement integration for 2026 launches.
Action Steps for 2026 Planning
-
For OEMs: Lock in one pilot health system for a bundled offering that combines instrument, sterilization service, and digital documentation—use 2026 to prove the ROI case with real utilization data.
-
For hospital systems: Run parallel TCO scenarios for reusable vs. disposable pathways in your 2026 capital planning cycle; incorporate sterilization capacity and staff training costs into the decision gate.
-
For private equity and corporate development: Target sub-scale manufacturers with proprietary optics or cost-advantaged disposables; 2026 is a year to accelerate diligence on targets that can be scaled through sales-channel consolidation.
Next Steps and How to Access the Full Intelligence
This executive briefing is designed as a strategic “trailer”: it conveys the market’s shape, the competitive fault-lines, and the practical choices that ought to inform 2026 budgets. To preserve the tactical utility of our benchmarking and the proprietary segmentation work that underpins targeted decisions (regional adoption curves, application-level economics, and product-type breakouts), detailed splits and downloadable models are available exclusively in the full report package.
For procurement teams, corporate development groups, and clinical innovation leaders preparing 2026 action plans, the full report provides the calibrated templates, data models, and vendor-level playbooks necessary to convert the market’s 5.48% CAGR and projected growth into executable advantage.
Contact PW Consulting to request the complete Worldwide Proctoscope Market report and obtain access to the interactive models, annexes, and vendor dossiers that will operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Proctoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com