

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Embedded Hypervisor Software Market to Rise from USD 565.0 Million in 2025 to USD 937.36 Million by 2032 at a 7.5% CAGR

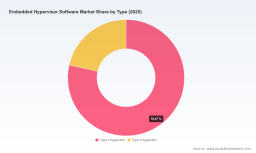
Worldwide Embedded Hypervisor Software Market — Strategic Briefing for 2026 Decision-Makers
As embedded systems evolve from isolated controllers into networked, mixed‑criticality platforms, hypervisor technology has become a strategic lever for product differentiation, safety compliance, and cost consolidation. PW Consulting’s new market study on the Worldwide Embedded Hypervisor Software Market provides a forward‑looking guide for executives who must make procurement, architecture and partner decisions in 2026. The market is no longer a niche engineering concern: after steady expansion through the early 2020s, the global embedded hypervisor market was estimated at USD 565.0 Million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of 7.5% over the forecast period, reaching roughly USD 937 Million by 2032. This trajectory creates windows of opportunity — and risk — for OEMs, Tier‑1 suppliers, semiconductor vendors, and systems integrators.
Worldwide Embedded Hypervisor Software Market
Why this matters to C‑suite and product leaders in 2026
Three trends turn hypervisor selection into a C‑level strategic priority:
Worldwide Embedded Hypervisor Software Market
- Safety and certification are non‑negotiable. Regulation and procurement requirements tied to DO‑178C (avionics) and ISO 26262 (automotive) mean that embedded hypervisors are evaluated as part of system certification pathways, not just as software components.
- Hardware choices constrain software architecture. Effective Type‑1 partitioning requires silicon with virtualization extensions; design decisions around Arm cores, RISC‑V extensions, or x86 virtualization materially affect performance, certification cost, and time‑to‑market.
- Consolidation potential vs. supplier concentration. The market shows meaningful concentration — the top three vendors collectively control a majority share, and the top five expand that control further — creating tradeoffs between best‑of‑breed capabilities and vendor dependence.
Market trajectory and practical implications
The market’s macro trajectory is clear: from a mature engineering problem to an enterprise procurement decision whose financial implications can be modeled predictably. Our projections suggest a meaningful uplift between 2025 and 2026 as platforms move from single‑OS ECUs to multi‑OS, multi‑criticality domains. This is a buying cycle that aligns with new silicon availability (Armv9 and emerging RISC‑V profiles) and growing requirements for certified partitioning. For 2026 planning, this means three practical implications:
Worldwide Embedded Hypervisor Software Market
- Prioritize hardware‑software co‑design. Architects must lock silicon and hypervisor roadmaps together to avoid rework when moving from evaluation to certifiable product builds.
- Budget for certification early. Certification planning (DO‑178C DAL A, ISO 26262 ASIL D, IEC standards for industrial and medical device contexts) should inform vendor selection and contractual milestones.
- Embed vendor concentration into risk models. With the marketplace exhibiting high concentration among a handful of specialist suppliers, procurement teams should model supplier failure, price pressure, and strategic lock‑in as scenarios in 2026 planning.
What the report delivers — practical, operational intelligence (not theory)
This study is expressly designed to move beyond high‑level forecasts into decision‑ready assets. Highlights of the operational content include:
- Vendor selection framework and weighted scoring models tailored to mixed‑criticality use cases (automotive ECUs, avionics line‑replaceable units, industrial controllers, medical devices).
- Certification playbooks that map functional and verification artifacts required to achieve DO‑178C and ISO 26262 objectives when using embedded hypervisors — with timelines and estimated resource profiles to support 2026 roadmap planning.
- Integration blueprints and reference architectures showing realistic consolidation paths (number of guest OSs, partition layouts, timing budget allocations) that can be adapted for specific silicon targets.
- Cost of ownership and productization models that quantify NRE, certification, maintenance, and upgrade paths across multi‑year product lifecycles.
- RFP templates, test plans, and security assessment checklists that accelerate vendor evaluation and reduce procurement cycle time.
These artifacts are presented as editable deliverables so teams can drop them into quarterly planning, R&D roadmaps, and supplier diligence workflows. The goal is to convert market intelligence into executable steps for 2026 product and sourcing decisions.
Competitive landscape — profiles and strategic moves to watch
The vendor landscape is dominated by specialist suppliers with deep safety and certification heritage. Our report analyzes each major player’s positioning, certification assets, architecture support, and recent strategic moves — distilled into implications for buyers.
- Wind River — A leader in avionics and safety‑critical systems, known for its VxWorks 653 hypervisor. Recent product work has extended support to RISC‑V and Armv9, signaling a tactical push to align with new silicon and broaden addressable platforms. For buyers, Wind River represents a fast path to avionics certification but comes with premium positioning and an expectation of close engineering partnership.
- Green Hills Software — Provides INTEGRITY‑178 and μ‑velOSity with strong ARINC 653 and real‑time partitioning credentials. Its strengths lie in isolation guarantees and legacy avionics/industrial deployments; for 2026, Green Hills is attractive where proven partitioning semantics and deterministic behavior are non‑negotiable.
- Lynx Software Technologies — LynxSecure emphasizes MILS‑class separation and has pursued strategic silicon relationships (e.g., partnerships for NXP i.MX integration). Expect Lynx to be a go‑to for industrial and defense systems that require formalized isolation and close SoC partners.
- SYSGO — PikeOS offers strong cross‑industry certification focus and recent medical device certification advances. SYSGO’s multi‑domain approach makes it a viable option for OEMs seeking a single supplier to cover avionics, automotive, industrial, and medical segments.
- Real‑Time Systems GmbH — Focused on pragmatic, performance‑oriented hypervisors for ARM and x86, with traction in automotive and industrial IoT. Their strength is in flexible, lightweight virtualization primitives that suit resource‑constrained ECUs.
- BlackBerry QNX — With QNX Hypervisor and established automotive safety credentials, QNX continues to be a leading choice for Tier‑1s and OEMs focused on in‑car infotainment and safety‑critical domains, particularly where integration with existing QNX stacks is desired.
- Mentor Graphics (Siemens EDA) — Brings a systems‑level perspective and toolchain integration that benefits large programs needing end‑to‑end development workflows.
- ETAS (Bosch Group) — RTA‑Hypervisor targets multi‑OS automotive ECUs and brings deep automotive toolchain compatibility and AUTOSAR alignment.
The recent vendor activity we track — product releases expanding architecture support, certification achievements in new domains, and strategic silicon partnerships — confirms a market where technical differentiation is tightly coupled with certification and ecosystem playbooks. These are the variables that will determine winners in 2026 procurement rounds.
Technology and regulatory dynamics that will shape 2026 decisions
- Hardware bottlenecks: Effective Type‑1 partitioning needs silicon with virtualization extensions (ARM virtualization extensions or x86 VT‑x). Buyers must validate platform support early in the selection process.
- Regulatory imperatives: DO‑178C DAL‑A and ISO 26262 ASIL‑D continue to govern certification strategies for avionics and automotive respectively — hypervisor selection is tightly coupled to achieving these certifications.
- Standards and APIs: Standards like ARINC 653 define partitioning interfaces and time‑space separation semantics; adherence simplifies certification and supplier interoperability.
- Real‑time limitations of Type‑2 hypervisors: For hard real‑time tasks, Type‑2 approaches (hosted on general‑purpose OSs) often introduce latencies inconsistent with 1ms determinism — a common trap for teams pursuing fast prototyping without long‑term certifiability.
Recommendations for 2026 planning
For executive teams crafting 2026 roadmaps, we offer four succinct recommendations:
- Make certification a gating item, not an afterthought. Embed certification milestones into procurement contracts and architecture signoffs.
- Align silicon choices with hypervisor roadmaps. Reserve budget and calendar for early co‑validation on target SoCs with virtualization extensions.
- Adopt a hybrid sourcing strategy. Combine established, certified suppliers for safety‑critical partitions with more flexible suppliers for non‑critical domains to balance risk and cost.
- Quantify concentration risk and mitigate via dual‑vendor evaluation on key systems. Given market concentration, maintain an alternate path to de‑risk supplier disruption or pricing pressure.
How PW Consulting’s study should be used in procurement and product committees
The report is intended as an operational toolbox for committees making binding decisions in 2026. Use it to:
- Shortlist vendors against a prescriptive, use‑case specific checklist.
- Create certification‑dependent gating criteria for prototype → product transitions.
- Inform M&A diligence where embedded virtualization is a target capability.
- Develop five‑year supplier roadmaps that align software stacks with silicon lifecycle and support windows.
Final note — a strategic “trailer” to drive controlled disclosure
PW Consulting’s Worldwide Embedded Hypervisor Software Market report offers both the strategic narrative and the tactical artifacts required for high‑stakes 2026 decisions. This briefing highlights the macro trajectory (USD 565.0 Million market in 2025; projected CAGR of 7.5% to roughly USD 937 Million by 2032), the competitive dynamics, and the operational levers procurement and product teams must control. The report contains in‑depth vendor scorecards, editable procurement templates, certification timelines, and integration blueprints that we intentionally do not reproduce here so that decision teams can access verified source materials, templates, and granular segmentation directly from the report package.
To obtain the complete set of deliverables, vendor scorecards, and the full dataset behind the projections, please visit the PW Consulting report page for the Worldwide Embedded Hypervisor Software Market. Use the materials there to convert strategic intent into executable, low‑risk product and procurement action in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com