

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Worldwide Gracey Curette Market Poised for 6.85% CAGR in 2026–2032

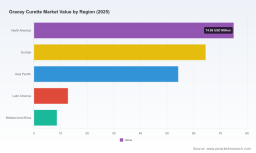
Worldwide Gracey Curette Market: Strategic Insights for 2026 Decision‑Making
PW Consulting’s new market study on the Worldwide Gracey Curette Market (base year 2025; historical period 2020–2025; forecast 2026–2032) equips healthcare executives, procurement leads, product R&D heads, and private equity investors with a compact, decision‑grade synthesis for 2026 planning. The market is experiencing steady expansion — growing from roughly USD 154.4 Million in 2020 to USD 215.0 Million in 2025, and projected to reach over USD 341.8 Million by 2032 at a compound annual growth rate (CAGR) of approximately 6.85%. These macro dynamics create a window of strategic opportunity for players across the value chain, while rewarding disciplined competitive moves and operational rigor.
Worldwide Gracey Curette Market
Executive summary — Why this report matters for 2026
-
Actionable foresight for near‑term capital allocation: The report translates market momentum into tactical recommendations for procurement cadence, inventory sizing, and CAPEX for instrument processing infrastructure.
Worldwide Gracey Curette Market -
Commercial playbook for growth: It outlines go‑to‑market options — from premium single‑use adjuncts and coated/treated instruments to service models (e.g., sharpening, subscription) — calibrated to 2026 demand signals.
Worldwide Gracey Curette Market -
Risk and compliance readiness: We map regulatory, sterilization, and standardization touchpoints that materially affect time‑to‑market, buyer preferences, and tender outcomes.
-
M&A and partnership lens: The study identifies structural features that make targets attractive for roll‑up strategies, strategic alliances, and OEM supply agreements.
What’s inside the report — practical, commercially oriented content
-
Market sizing and trend synthesis (historical and forecast) with scenario analysis calibrated for 2026 decision horizons.
-
Demand driver mapping and buyer persona insights for private dental practices, institutional buyers, and academic/research segments.
-
Regulatory and standards matrix (including implications of device classification, sterilization requirements and reimbursement coding) that materially influence procurement and product design.
-
Competitive benchmarking and supplier scorecards emphasizing product attributes, price‑performance, and service models.
-
Commercial and operational playbooks: supplier selection criteria, procurement RFP templates, and sterilization throughput planning for central sterile services.
-
Investment thesis and M&A screening framework, including diligence checklists focused on manufacturing quality, IP (coatings, heat treatments), and aftermarket services.
-
Key performance indicators for procurement and clinical adoption, plus a prioritized 100‑day plan for market entry or expansion.
Market dynamics shaping decisions in 2026
Several non‑market forces set the guardrails for strategic action next year. From a regulatory perspective, Gracey curettes remain a low‑barrier device class in key jurisdictions, which lowers time‑to‑market risk but raises the bar on supplier quality and standards compliance as differentiators. Practically, these instruments are classified in the U.S. regulatory framework in a manner that exempts many from premarket notification, yet purchasers and clinicians demand conformity to internationally recognized standards for surgical instruments. Sterilization requirements — routine steam autoclaving at validated cycles — create operational constraints for clinics and centralized sterile processing facilities and therefore influence preferences for instrument finish, metallurgy, and lifecycle costing.
Reimbursement coding for periodontal procedures also subtly affects adoption velocity: where periodontal scaling and root planing are well‑reimbursed, clinical throughput and instrument replacement cadence accelerate. Material advances in instrument metallurgy and surface treatments influence total cost of ownership; instruments that sustain edge integrity longer reduce sharpening cycles and reprocessing costs, an attractive proposition for high‑volume users.
Demand vectors and innovation priorities
Clinician adoption is being driven by a mix of clinical efficacy, ergonomics, and lifecycle cost economics. Practitioners are increasingly valuing instruments that reduce hand fatigue, improve access to subgingival anatomy, and retain sharpness between sharpening cycles. These performance attributes translate into two commercial imperatives for 2026:
-
Design and materials innovation: investments in coatings, heat treatments, and handle ergonomics remain high‑leverage areas where suppliers can achieve premium pricing or improved share in high‑volume accounts.
-
Service differentiation: bundled offerings that combine clinical education, on‑site sharpening or refurbishment, and predictable replenishment contracts are becoming decisive in procurement negotiations.
For executives, prioritizing product pipelines that demonstrably lower clinical effort and lifecycle costs will have outsized returns in the next 12–24 months.
Competitive landscape — positioning and implications
The market exhibits meaningful product innovation pockets alongside a fragmented supplier base. A few observations on main competitive archetypes and strategic implications:
-
Premium innovators: Companies offering advanced edge technologies, controlled heat treatment processes, and micro‑geometry instruments compete on clinical superiority and clinician preference. These suppliers can target higher ASPs and specialty institutional channels.
-
Ergonomic and service‑oriented suppliers: Firms that emphasize ergonomic handles, lightweight construction, and sharpening longevity focus on workflow savings and clinician comfort — attributes that resonate with high‑throughput clinics.
-
Broadline players: Manufacturers that position Gracey curettes within a wider periodontal instrument portfolio compete on procurement convenience and bundled purchasing discounts.
Representative companies profiled in the study include established and specialized names across North America and Europe. Profiles summarize product portfolios, unique technology claims (e.g., coatings, heat treatments, hollow handles, color‑coding), and channel focus — information oriented to help buyers and investors prioritize partners or acquisition targets. Executive teams should evaluate suppliers not only on product specs but on quality systems, sterilization compatibility, and aftermarket service capability.
Market concentration metrics underscore an open landscape: the top three players hold a limited single‑digit to low‑double‑digit share of the market, and the top five account for a modest increase over that. In practice, this means there is runway for consolidation, vertical integration of sharpening/refurbishment services, and for well‑funded entrants to capture niche leadership through focused innovation.
Operational levers for 2026
-
Procurement optimization — adopt a supplier scorecard that weights clinical performance, sterilization compatibility, and lifecycle cost rather than headline unit price alone.
-
Inventory and sterilization planning — align procurement with sterilization throughput capabilities; higher edge retention reduces inventory and reprocessing cycles.
-
Clinical training and adoption programs — invest in KOL partnerships and hands‑on training to accelerate clinician preference for new instrument geometries.
-
Service model experiments — pilot subscription or sharpening‑as‑a‑service models in representative markets to validate CAC and recurring revenue potential.
-
M&A and partnership focus — target small to mid‑sized specialists with proprietary coatings or heat‑treatment know‑how, and assets that can be quickly integrated into existing distribution footprints.
How to use this report for decisive action in 2026
Executives should treat the study as a practical toolkit for immediate and medium‑term choices. For procurement teams, the report supplies negotiation levers and an RFP template. For product and R&D leaders, it prioritizes innovation themes that influence buying decisions next year (edge retention, coated surfaces, ergonomic grips). For investors and corporate development teams, the study provides a screening rubric to identify attractive consolidation targets and cliffs where regulatory or standards compliance creates entry barriers.
We emphasize that while this release highlights macro sizing and growth (including the 2025 base and the near‑term 2026 outlook), the full report contains the granular subsegment and regional intelligence — detailed growth trajectories by market channel, product type, and region — necessary to execute targeted go‑to‑market plans and deal diligence. That detailed segmentation data is intentionally reserved for the full report to ensure tailored and actionable engagement.
Methodology and data integrity
The analysis is grounded in a multi‑source methodology: longitudinal market tracking (2020–2025), primary interviews with clinicians, procurement officers, and manufacturers, audited company disclosures, sterilization and standards documentation, and scenario‑based forecasting through 2032. Financials are presented in constant 2025 USD (Million) to ensure comparability. Forecasting incorporates sensitivity to reimbursement dynamics, clinical procedure volume scenarios, and technology substitution curves.
Conclusion — next steps for leaders
As the Gracey curette market expands at an approximate 6.85% CAGR, 2026 represents a pivotal year to convert favorable macro momentum into defensible commercial advantages. Whether the priority is optimizing clinical workflows, upgrading procurement to value‑based models, or executing consolidation plays, PW Consulting’s study provides the operational scaffolding leaders need to act with confidence.
For the full dataset, granular segment and regional breakdowns, supplier scorecards, and the 100‑day execution plan, access the complete Worldwide Gracey Curette Market report on our website or contact PW Consulting’s research team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Gracey Curette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com