

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecasts WNT Signaling Pathway Inhibitors Market to Surge at a 12.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
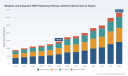
PW Consulting: Strategic Brief — Worldwide WNT (Wingless and Integrated) Signaling Pathway Inhibitors Market and the 2026 Decision Window
Executive snapshot
As WNT pathway biology moves from bench curiosity toward translational momentum, 2026 will be a year when strategic choices made today determine who captures therapeutic and platform value over the coming decade. PW Consulting’s new market study — built off a 2025 base and a 2026–2032 forecast horizon — finds the global WNT signaling pathway inhibitors market has more than tripled since 2020 and is tracking toward multi-billion-dollar scale by the early 2030s at a sustained compound annual growth rate of approximately 12.5%. This trajectory reflects accelerating clinical activity, expanding preclinical demand for research-grade compounds, and a growing set of strategic commercialization pathways despite the absence, to date, of any FDA-approved therapeutic WNT inhibitor.
Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
Why this report is strategically material for decisions in 2026
-
Inflection timing: 2026 represents the convergence of increased clinical readouts (Phase 1/1b combination studies), stronger translational evidence, and rising commercial interest from both reagent suppliers and biopharma sponsors. The market’s strong historical expansion from 2020–2025 has created optionality for investors, but the choices in 2026 will influence market positioning into the 2030s.
Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market -
Translational complexity: More than a hundred active clinical programs underscore scientific enthusiasm, but regulatory and safety unknowns remain. There are distinct strategic pathways between supporting research reagents and developing therapeutic candidates — each with different value levers and timing.
Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market -
Supply economics and manufacturing constraints: Complex multi-step syntheses — especially for Porcupine and Tankyrase inhibitors — create pronounced COGS pressure and sourcing risk. For research-grade quantities the market sees prices in the tens to low hundreds of dollars per milligram, an early signal of manufacturing intensity that will scale with therapeutic demand.
-
Commercial readiness before approval: No therapeutic WNT inhibitor has FDA approval as of the study’s base year. Organizations that align clinical, regulatory, and payer strategies early will de-risk commercialization timelines and price-setting negotiations.
What the PW Consulting report delivers — practical, decision-grade assets
We designed this study to be operationally useful for corporate strategy, BD&L, R&D leadership, and investors. Key deliverables include:
-
Dynamic market sizing model (base 2025; forecast 2026–2032) with sensitivity scenarios tied to clinical success, regulatory milestones, and COGS improvements — enabling “what-if” investment and revenue forecasts.
-
Clinical-trial tracker and readout calendar that flags high-impact inflection events, combination studies, and biomarker-led programs — prioritized by commercial upside and probability-of-success.
-
Supplier and upstream chemistry matrix mapping research-reagent vendors, CMO capabilities, capacity constraints, and raw material dependency — including pricing benchmarks and lead-time analysis for critical intermediates.
-
Regulatory & reimbursement playbook that translates existing RUO labeling realities into pathways for therapeutic trials, companion diagnostics, and early HTA engagement.
-
Competitive landscaping with compact strategic profiles of established reagent suppliers and translational-stage innovators, plus an M&A and partnership playbook that quantifies trade-offs between in-house development and inorganic scale-up.
-
Commercial go-to-market scenarios covering launch sequencing, channel design (research vs clinical distribution), and payer engagement models for specialty oncology and potential non-oncology uses.
Competitive landscape: what to watch and why
The early WNT ecosystem remains a hybrid of research-reagent specialists and therapeutic-focused developers. Key actors executing at scale include established life-science suppliers who dominate the preclinical and translational supply chain, alongside smaller biotech players advancing clinical candidates:
-
MedChemExpress LLC (Monmouth Junction, NJ): A leading supplier of widely used research-grade inhibitors. Their catalog breadth makes them a default partner for many translational groups and a bellwether for preclinical demand.
-
Selleck Chemicals (Houston, TX): Known for a deep portfolio of pathway modulators; their distribution networks accelerate time-to-reagent for academic and industry labs, shaping early target validation pace.
-
Cayman Chemical (Ann Arbor, MI): Focuses on high-purity compounds that support more demanding translational assays and GLP-aligned studies, positioning them on the higher end of the reagent value chain.
-
Tocris Bioscience (Bristol, UK): Offers selective modulators that pair well with inhibitor portfolios for orthogonal validation, supporting sophisticated target interrogation strategies.
-
Sigma-Aldrich (St. Louis, MO): Its catalog reach and commercialization scale provide a strategic distribution advantage for widespread reagent adoption.
-
TargetMol (Boston, MA): A focused player bridging research reagents and preclinical-standard compounds — often a source of early chemical matter for translational pipelines.
On the therapeutic front, clinical activity — exemplified by recent development programs such as porcupine inhibitor RXC004 entering combination Phase 1b/2 studies — highlights the immediate strategic binary: combination-readout success can rapidly reframe trial design, partnership urgency, and commercial forecasts.
Industry dynamics that materially affect 2026 choices
-
Regulatory baseline: No FDA-approved WNT inhibitors → regulatory uncertainty is a gating variable for investment scaling and payer strategy formation.
-
Clinical density: Over one hundred active trials amplify both scientific learning and the noise of competing hypotheses — making careful signal extraction essential when prioritizing indications and combinations.
-
Reimbursement & labeling: Many reagents remain classified as research-use-only; sponsors must therefore plan early for translational-to-therapeutic handoffs and parallel diagnostic strategies.
-
Supply economics: Complex synthesis and high per-mg research prices imply early investments in manufacturing scale and CMO relationships will unlock margins as demand moves from milligrams to grams and beyond.
Strategic playbook — 10 actions for leadership teams in 2026
-
Prioritize optionality: Structure investments as staged commitments tied to specific readouts (first-in-human safety, first combination efficacy signal) to avoid overpaying for unproven modality risk.
-
Secure chemistry and CMO partnerships now: Negotiate supply agreements and tech-transfer options to control API continuity and drive down unit manufacturing costs as programs transition to later-phase trials.
-
Design combination-aware trials: Plan early for simultaneous or sequential combinations with established chemotherapies and IO agents; the clinical landscape shows combination strategies are becoming the norm.
-
Invest in translational biomarkers: Differentiate candidates through companion diagnostics and patient-selection assays that increase probability of clear efficacy signals in early cohorts.
-
Map reimbursement scenarios now: Model potential payer negotiations under multiple approval and label outcomes; consider early HTA engagement in priority geographies.
-
Build a bifurcated commercial plan: Separate channels for continued reagent/research revenues versus future therapeutic commercialization to maintain near-term cash while preparing for long-term launch needs.
-
Monitor competitor reagent supply to anticipate surrogate adoption: Portfolio breadth among reagent suppliers can presage which molecular classes will be most heavily explored translationally.
-
Use scenario-driven M&A: Target bolt-on chemistry or CMO assets that shorten time-to-scale rather than large and expensive platform acquisitions without clinical proof points.
-
Plan for regulatory contingency: Establish early dialogue with regulators and create safety monitoring infrastructures to rapidly address off-target biology when moving into vulnerable patient populations.
-
Adopt an adaptive budgeting approach: Reallocate development and commercial spend based on milestone gates rather than calendar years to preserve liquidity and responsiveness.
How to extract value from the report
Executives should treat the PW Consulting report as a decision engine, not merely a narrative. Use the included financial model to stress-test investment cases under multiple clinical and price scenarios. Leverage the clinical-trial tracker to schedule BD outreach and negotiate option terms timed to high-value readouts. Apply the supplier matrix when negotiating long-term supply agreements — early leverage can materially reduce downstream COGS risk.
Next steps and access
For teams preparing 2026 budgets, pipeline prioritization, or M&A roadmaps, our study provides a practical blueprint and evidence-based thresholds for commitment. The report intentionally showcases analytical depth while withholding certain granular segmentation figures in this public release — access to the full dataset, scenario model, and company scorecards is available through the PW Consulting portal for subscribing clients. Engaging with the full study prepares leadership teams to convert the 2026 inflection into a durable strategic advantage.
Contact PW Consulting to schedule a private briefing and to receive the interactive market model and clinical readout calendar tailored to your organization’s portfolio and risk posture.
For detailed analysis of this topic, please visit the official page: Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 8.52% CAGR for Worldwide Indoor Lighting Control Systems Market, Driven by Wireless and Commercial Adoption
By pmarketresearch, 2026-07-15
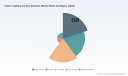
Worldwide Indoor Lighting Control Systems Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s newest market study on Worldwide Indoor Lighting Control Systems synthesizes five years of historical performance and a seven‑year forecast to deliver a decision‑grade view for corporate strategy teams, investors, and procurement leaders. Anchored on a 2025 base year and modeled through 2032, the study quantifies the market trajectory and pairs that with operational intelligence you can act on in 2026 — while reserving the granular segment tables and regional breakouts for the full report.
Worldwide Indoor Lighting Control Systems Market
Why this briefing matters for 2026 strategic planning
- The indoor lighting control systems market is transitioning from a cost‑reduction play to a systems‑level value proposition that ties lighting to buildings’ operational intelligence. Our market model—built from 2020–2025 historicals and projecting 2026–2032—shows sustained expansion at a compound annual growth rate (CAGR) of approximately 8.5%. This makes lighting controls a growth category deserving of capital and organizational attention in 2026.
- For executives weighing retrofit vs. new‑build strategies, procurement of sensor networks, or alliances with platform providers, the timing is critical: the market moves from product sales to platform and recurring‑revenue services. The 2025 market baseline and our forward curve enable finance teams to size near‑term opportunity and stress‑test revenue scenarios under multiple adoption speeds.
- Our analysis emphasizes where commercial outcomes (energy savings, occupant wellbeing, operational automation) align with regulatory and standards momentum—creating pockets of predictable demand that should inform go‑to‑market prioritization in 2026.
Key macro picture (what the numbers tell you)
Mapping five years of observed outcomes into a seven‑year forecast yields a clear narrative: demand for indoor lighting controls is resilient and accelerating as IoT integration, energy regulation, and LED proliferation converge. With a 2025 market baseline and a projected average growth near 8.5% over the forecast horizon, organizations can anticipate both scale and upgrading cycles rather than one‑time transactions. This trajectory favors vendors and integrators that can convert one‑off installations into managed services and analytics subscriptions.
Worldwide Indoor Lighting Control Systems Market
Practical, decision‑grade deliverables inside the full report
- Robust market sizing and scenario models (base case, adoption‑accelerated, and constrained scenarios) calibrated to historical 2020–2025 performance and validated against vendor reporting.
- Channel and procurement playbooks showing how to structure contracts that capture value across hardware, installation, integration, and recurring software/analytics streams.
- Technology adoption roadmaps for wired, wireless, and hybrid deployments — including migration patterns from legacy dimming protocols to DALI‑2 and IP‑native controls.
- CapEx/Opex comparison templates for retrofit vs. greenfield decisions that tie lighting control investments to payback timelines and ESG reporting metrics.
- Supplier selection framework with weighted criteria (technical interoperability, standards compliance, cybersecurity posture, financing options, and lifecycle services).
Note: the summary above is deliberately high‑level. The full report contains the granular regional, technology, and application splits, as well as detailed supplier scorecards and proprietary unit‑price models.
Worldwide Indoor Lighting Control Systems Market
Market dynamics shaping 2026 execution
- Regulatory tailwinds are tangible. European energy efficiency mandates and North American building energy codes increasingly require automated control strategies as part of compliance. For procurement teams, this equates to mandatory functionality rather than competitive differentiation — and it shortens the sales cycle for compliant solutions.
- Standards convergence (notably DALI‑2 and KNX certification proliferation) reduces integration risk for multi‑vendor projects and accelerates enterprise adoption. Interoperability standards lower switching costs and make platform openness a competitive advantage for vendors.
- Sensor economics and supply dynamics matter. Component costs (for example, commodity PIR occupancy sensors) have compressed margins on basic controllers but created opportunities for value capture higher in the stack—analytics, asset management, and integration services.
- Wireless protocols and mesh technologies continue to displace dedicated wiring in many retrofit scenarios, turning constrained installation budgets into addressable opportunities for innovative vendors with robust commissioning toolsets.
Competitive landscape — what to watch in 2026
The competitive field blends large multinational electrical and building automation firms with specialized lighting control vendors. The market is moderately concentrated: a number of well‑established global firms command leadership positions, but the remainder of the market remains accessible to focused challengers and regional integrators. Key players profiled in the study include:
- Signify (Eindhoven, Netherlands) — an IoT‑led approach centered on the Interact platform, combining sensors, gateways, and cloud management for commercial buildings.
- Lutron Electronics (Coopersburg, PA, USA) — a long‑standing specialist in both wired and wireless controls, with solutions tuned for home and commercial automation.
- Acuity Brands (Atlanta, GA, USA) — multi‑channel offerings that bridge wired and wireless architectures and emphasize certified interoperability.
- Schneider Electric (Rueil‑Malmaison, France) — building‑wide IoT integration that positions lighting as one domain within converged building management.
- Legrand, ABB, ams‑OSRAM, Tridonic, Helvar, Eaton, Delta Electronics, and Hubbell Lighting — each with targeted strengths in protocol support, aftermarket components, DALI ecosystems, or integration services.
Our vendor analysis does more than list logos: it assesses product roadmaps, platform openness, channel reach, and the ability to support enterprise‑grade cybersecurity and lifecycle services. The full vendor matrix in the report includes a capability scorecard and suggested partnership archetypes for OEMs and systems integrators.
Notable recent developments that shape 2026 tactics
- Product innovation: Major players have introduced AI‑enabled occupancy sensing and node‑based wireless products that simplify commissioning and reduce per‑installation labor.
- Protocol upgrades: Vendors are shipping products with native DALI‑2, Thread, and other IP‑friendly protocols—lowering integration friction with building management and IoT platforms.
- Certifications: DALI‑2 certifications and other standard milestones reduce perceived risk for enterprise buyers and unlock larger contracts tied to compliance roadmaps.
These developments imply that buyers should prioritize solutions with modular upgrade paths and vendors that demonstrate cadence in firmware and cloud feature delivery.
Strategic implications and recommended actions for 2026
- Procurement: Move beyond lowest‑price RFPs. Include interoperability, long‑term support, and data ownership clauses. Our pricing and TCO models enable procurement teams to quantify the true lifetime cost for managed vs. transactional engagements.
- Technology roadmaps: Favor vendors committed to standards and with documented upgrade paths for wireless and IP‑native deployments. That reduces risk of stranded assets as standards evolve.
- Partnerships and M&A: Mid‑market integrators and component specialists remain attractive targets for larger platform providers seeking to accelerate field‑installation capabilities and local market penetration.
- Service design: Design offers that bundle analytics, energy reporting, and predictive maintenance. The market shift from hardware to services means margin pools increasingly favor software and managed services.
- Pilots and scaling: Use a "pilot to program" approach—validate interoperability and data flows on small installs, then scale geographically. Our implementation playbooks show typical timeline, resource needs, and acceptance criteria.
How the report supports boardroom decisions
Boards and C‑suites can use the report to: (1) calibrate capital allocation for smart building investments, (2) set go‑to‑market priorities for product and channel investments, and (3) assess acquisition targets against a quantified market size and trajectory. The study’s scenario engine helps quantify revenue sensitivity to price, adoption rate, and regulatory tightening — all of which drive valuation multiples for vendors and integrators in the space.
Methodology and reliability
The study combines top‑down macro assessment with bottom‑up revenue build‑ups, validated against vendor disclosures, procurement datasets, and primary interviews with integrators and facility managers. Our base year is 2025; historical coverage spans 2020–2025 and the forecast extends 2026–2032. Financials are presented in USD (Million). We apply sensitivity analysis to test outcomes under optimistic and constrained adoption paths, and we document assumptions transparently so you can re‑run scenarios with your own inputs.
Limitations and where to go for the full intelligence
This briefing emphasizes the strategic narrative and selective macro datapoints to illuminate decision paths. It intentionally does not include the full regional and application‑level tables, granular pricing models, or the vendor scorecard detail. Those elements are included in the full study and supporting data pack, which is designed for procurement, product, and M&A teams that require line‑item granularity.
Next steps
- For procurement teams: Request the TCO templates and vendor scorecard annex to start vendor shortlisting in Q1 2026.
- For product and engineering: Access the protocol adoption maps and technology migration timelines to prioritize integration workstreams.
- For M&A and strategy teams: Use the scenario engine in the report to stress‑test target valuations under different adoption and regulatory outcomes.
PW Consulting’s Worldwide Indoor Lighting Control Systems Market report is tailored to turn uncertainty into actionable plans for 2026. For full market tables, segmented forecasts, supplier scoring, and downloadable models, consult the full report and data pack on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Indoor Lighting Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Modern AI Infrastructure to Surge from USD 312.6B in 2025 to USD 1.68T by 2032 at a 27.14% CAGR
By pmarketresearch, 2026-07-15
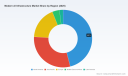
Worldwide Modern AI Infrastructure Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research, Worldwide Modern AI Infrastructure Market (base year 2025), synthesizes a fast-evolving ecosystem into actionable guidance for CIOs, CTOs, procurement leads, and boardrooms planning capital allocation in 2026. The market reached USD 312.6 Billion in 2025 and is forecast to expand at a 27.14% CAGR through 2032, reaching approximately USD 1.68 Trillion by the end of the forecast window. That pace of expansion, combined with shifting supply dynamics, regulatory constraints and infrastructure bottlenecks, makes 2026 a pivotal year for strategic choices that will determine competitive positioning for the remainder of the decade.
Worldwide Modern AI Infrastructure Market
Why 2026 Is an Inflection Point
The macro picture driving urgency in 2026 is clear: hyperscalers and major cloud providers are committing record capital to AI infrastructure, industrial-scale GPU deployments continue to concentrate demand, and semiconductor and systems suppliers are racing to expand capacity. Public signals from the hyperscalers point to combined capex guidance that will materially outstrip historical norms, while suppliers are negotiating supply agreements and strategic partnerships to secure long-lead components.
Worldwide Modern AI Infrastructure Market
At the same time, non-market constraints are shaping deployment timelines. Power availability, grid interconnection queues and long lead times for large electrical transformers are now frequently the binding constraints on new AI data center capacity. Delays measured in quarters — and in some cases years — are being reported for projects originally scheduled for 2026, shifting practical deployment windows into 2027–2028 unless mitigations are in place. Material intensity (wiring, cooling infrastructure and specialty copper) and the need to integrate liquid cooling and advanced power distribution systems are elevating the capital and delivery complexity of every new build.
Worldwide Modern AI Infrastructure Market
Regulatory dynamics add another layer of strategic risk. Export controls on advanced computing integrated circuits and new limits on frontier AI model artifacts introduce shipping and licensing complexity that can affect supplier selection, geographic sourcing, and contractual terms. Compliance strategies will now need to interleave export licensing, supplier audits and operational segregation to avoid business disruptions.
What the Report Delivers — Practical, Actionable Intelligence
- Robust sizing and forecasting anchored to historical trends (2020–2025) and forward-looking scenarios (2026–2032), with transparent methodology and sensitivity tests tuned to capex cycles, component lead times, and regulatory shocks.
- Operational segmentation by component, deployment model and infrastructure topology, coupled with deployment playbooks and TCO templates tailored for cloud-native, hyperscale colocation, enterprise data center and edge AI use cases.
- Vendor landscape maps, risk heatmaps and procurement scorecards that prioritize suppliers by capability, scale-readiness, and supply-chain resilience.
- Scenario-based procurement and financing strategies (including capex vs. opex trade-offs), together with contract clauses and insurance approaches to hedge against delivery slips driven by power and materials constraints.
- Technical appendices: cooling and power design benchmarks, ISO/IEC 30134-aligned energy and water performance KPIs, and a checklist for integrating next-generation accelerators and networking fabrics into existing operations.
To preserve strategic advantage for clients and partners, the public preview intentionally omits detailed segment tables and split-level sizing; those granular models and vendor scorecards are available in the full report and interactive dashboards.
Competitive Landscape — Who Matters and Why
The market remains concentrated among a small set of suppliers and platform operators, and the competitive calculus is increasingly a function of both silicon and systems capability plus the ability to deliver scale fast. Concentration metrics in our analysis indicate that the top three suppliers control a dominant portion of addressable value, and the top five capture an even larger share — a structure that creates acute supply-risk and pricing leverage for those incumbents.
- NVIDIA Corporation — The de facto leader in accelerator ecosystems, offering not just chips but an extensive software and networking stack that underpins many large-scale training clusters. Its partnerships and supply agreements are materially influencing availability and architecture choices across the market.
- Advanced Micro Devices (AMD) — Competing with optimized accelerator lines and driving alternative high-throughput architectures for HPC and AI clusters, particularly in heterogenous deployments.
- Intel Corporation — Bringing CPU and accelerator portfolios to the data center, with a particular emphasis on integrated platform solutions that target enterprise and hyperscale operators.
- Broadcom Inc. and Arista Networks — Critical providers of high-speed interconnects and switching fabrics; their roadmaps determine the performance envelope of clustered accelerators.
- Hyperscalers (AWS, Microsoft Azure, Google Cloud, Oracle) — Beyond cloud services, these firms are both major buyers and innovators: custom silicon, managed infrastructure offerings and capacity reservations are reshaping procurement options for enterprises.
- TSMC and the foundry ecosystem — The ultimate bottleneck for advanced process nodes; wafer capacity and priority allocations to large customers are a defining constraint on new accelerator availability.
- Specialized providers (CoreWeave, Cerebras, Groq, Vertiv, Equinix) — Niche and ancillary players that offer differentiated pathways: high-density GPU clouds, wafer-scale solutions, inference-optimized LPUs, and infrastructure services (power, cooling, colocation).
Recent Market Signals That Matter for Procurement
- Major investment and supply agreements between accelerators and leading AI model operators indicate prioritized allocation to certain customers and use cases — buyers should assume constrained spot availability and plan contractual commitments accordingly.
- Large-scale financing plans by cloud platform operators to expand capacity reflect a wave of near-term demand; enterprises should evaluate capacity reservation options or consider hybrid approaches to avoid vendor-backed queuing.
- Emerging IP and productization in modular, liquid-cooled, high-density edge/containerized data centers point to alternative deployment routes for latency- or data-sovereignty-sensitive workloads.
Key Risks and Operational Constraints for 2026 Deployments
Our fieldwork and supplier interviews highlight five operational constraints that require immediate attention by enterprise planners:
- Power and Grid Interconnection: multi-year wait times for key electrical components and interconnection slots are now commonplace. Expect project schedules to slip without early engagement with utilities and flexible contracting clauses.
- Material and Component Lead Times: copper-intensive builds, specialty transformers, and bespoke cooling loops have long procurement tails. Inventory strategies and supply agreements are essential.
- Regulatory and Export Controls: evolving export controls on advanced computing items and frontier model artifacts increase compliance complexity for cross-border operations and supplier selection.
- Vendor Concentration Risks: a small number of suppliers control critical stack elements — diversifying across architecture families and engaging alternative accelerator vendors reduces single-source exposure.
- Sustainability and Standards Compliance: ISO/IEC 30134-series metrics are becoming contractual and investor requirements; energy and water efficiency planning is now operational risk management.
Timing and CapEx Strategies — How to Respond in 2026
Enterprises should treat 2026 as a year to shift from opportunistic procurement to strategic capacity planning. Practical approaches include:
- Immediate site readiness audits that focus on power, cooling and interconnect permit paths.
- Workload mapping to determine which models and inference tasks are best suited to hyperscale cloud, specialized GPU clouds, colocation or on-prem deployments.
- Tiered contracting strategies: a mix of short-term cloud capacity, medium-term reserved instances/commitments, and long-term build contracts with phased delivery.
- Supplier engagement playbooks that include export-compliance clauses, option windows for accelerated delivery, and staged payment tied to performance milestones.
- Financial hedging: scenario-driven ROI models that explicitly incorporate delivery slippage, energy-cost shocks and carbon compliance costs.
Recommended First Moves for Executive Teams
- Commission an immediate 90-day infrastructure readiness program focused on power and site interconnects.
- Map critical AI workloads to an infrastructure taxonomy and prioritize those workloads for reserved capacity procurement.
- Negotiate flexible supplier agreements that account for export-control risk and allow for architectural fallbacks.
- Pilot advanced cooling and modular data-center solutions where speed-to-deploy and density matter most.
- Embed sustainability KPIs aligned to ISO/IEC 30134 into procurement scorecards and vendor SLAs.
PW Consulting’s Worldwide Modern AI Infrastructure Market report is designed to support these actions with the granular models, vendor scorecards, procurement templates, and scenario analyses that senior leaders need to operationalize decisions in 2026. This preview outlines the strategic landscape and operational imperatives; the full report and interactive dashboards contain the detailed split-level sizing, regional breakdowns, vendor benchmarking matrices and implementation playbooks required to execute with confidence.
For enterprise teams preparing 2026 budgets and long-term AI infrastructure strategies, the choice is between reactive sourcing — accepting unpredictable delivery windows and higher total cost — and proactive, model-driven procurement that secures capacity, manages regulatory exposure, and aligns deployments to sustainability and performance targets. PW Consulting’s full report provides the decision-grade intelligence to take the proactive path. Visit PW Consulting’s research portal to access the full report, data visualizations and bespoke advisory packages.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Okra Seeds Market to Grow at 8.15% CAGR, Prompting Strategic Shifts in Seed Production
By pmarketresearch, 2026-07-15
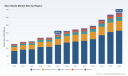
Worldwide Okra Seeds Market — Strategic Insights for 2026 Decision-Making
Executive summary
As global food systems intensify their focus on vegetable protein, resilience and smallholder incomes, the okra seeds market is emerging from a period of steady recovery into one of structurally higher growth. PW Consulting’s new market model projects the global okra seeds market to expand at a compound annual growth rate (CAGR) of 8.15% over the 2026–2032 forecast window, building on an estimated market size of USD 382.45 Million in the 2025 base year and reaching an estimated USD 661.86 Million by 2032. This trajectory reflects a confluence of agronomic innovation, concentrated commercial seed development, and renewed public–private breeding efforts that together reshape varietal adoption patterns and commercial opportunity sets for seed companies, input suppliers, and development partners.
Worldwide Okra Seeds Market
Why this matters for 2026 corporate strategy
-
Timing of investment: With accelerating growth projected beyond 2026, decisions made in the next 12–18 months—around breeding alliances, capacity expansion, and market-entry partnerships—will capture disproportionate share as commercial hybrid adoption and programmatic releases converge.
Worldwide Okra Seeds Market -
Portfolio prioritization: Seed firms must reassess R&D and distribution allocations between hybrid and open-pollinated strategies, balancing short-term revenue capture with long-term farmer access and seed-system resilience.
Worldwide Okra Seeds Market -
Channel optimization: Shifts in procurement economics and farmer labor dynamics (notably the high cost of hired labor in many producer systems) elevate the value of traits that reduce labor intensity and enable mechanization or simplified management.
-
Policy and input-cost headwinds: Public investments in fertilizer production and national varietal approvals are changing input availability and regulatory risk; firms that align commercial plans with policy timelines will reduce market-entry friction.
Market trajectory — drivers and practical implications
The projected CAGR of 8.15% to 2032 is underpinned by four converging drivers that have direct operational implications for 2026 planning:
-
Breeding acceleration and public–private collaboration. The relaunch of coordinated okra breeding programs and new variety releases have shortened time-to-market for resilient, high-yielding cultivars. For decision-makers, this reduces R&D uncertainty but increases the importance of rapid seed multiplication and distribution planning.
-
Commercial consolidation and concentration. The market shows meaningful concentration among leading seed firms (market concentration: CR3 ~42.5%; CR5 ~58.75%), which creates both competitive barriers and partnership opportunities. Market entrants must evaluate vertical integration, licensing, or acquisition as routes to scale.
-
Input-cost dynamics and agronomy. Recent public investments in fertilizer production, coupled with agronomic evidence on nutrient and water regimes (e.g., the importance of balanced NPK and moderate supplemental irrigation for reliable yields), are shifting profitability profiles for growers and the economics of seed choice.
-
Market access and regulatory cadence. National approvals of new varieties and coordinated release strategies—illustrated by recent varietal approvals in country-level catalogs—are catalyzing faster adoption where seed systems and seed regulations are aligned.
Strategic imperatives for 2026
For executives and strategy teams preparing 2026 playbooks, PW Consulting highlights four priority actions that translate market insight into executable moves:
-
Fast-track partnership blueprints: Negotiate modular breeding and licensing agreements that allow phased royalty or revenue-share models. These reduce upfront cost while securing priority access to high-performing germplasm.
-
Operationalize seed multiplication pipelines: Convert breeding gains into marketable volumes through contract growers, nucleus seed programs, and regional multiplication hubs. Early-capacity commitments avoid lost shelf space when varieties launch.
-
Design trait-first, farmer-centric product lines: Prioritize traits that reduce labor and input intensity (disease resistance, extended harvest windows, and configurations suited to supplemental irrigation regimes) to appeal to both smallholders and commercial growers.
-
Embed policy intelligence into go-to-market timing: Align launches with national varietal registration windows and leverage public programs that subsidize input costs or promote improved germplasm to accelerate uptake.
What PW Consulting’s report delivers (practical, actionable content)
Our Worldwide Okra Seeds Market report is structured to move from insight to implementation. Key practical deliverables include:
-
Proprietary market model and scenario suite: Base-case, policy-accelerated, and constraint-aware scenarios that quantify market trajectories through 2032 and inform capital allocation under alternate assumptions.
-
Commercial playbooks: Step-by-step guides for breeding partnerships, seed multiplication, and channel deployment, including contract templates, seed-lot sizing heuristics, and seasonal distribution calendars.
-
Go-to-market diagnostic for legacy portfolios: Assessment tools to prioritize SKUs for market exits, upgrades, or relaunch—scored against adoption risk, margin potential, and regulatory exposure.
-
Capex and operating benchmarks: Comparative KPIs for seed production facilities, cold-chain needs (where relevant), and staffing models that reduce time-to-volume for new varieties.
-
Risk register and mitigation playbook: Practical mitigations for input-price shocks, labor constraints, phytosanitary hurdles, and rapid varietal substitution pressures.
Note: The report presents detailed regional and application splits, varietal performance matrices, and revenue-by-channel estimates in appendices. These granular tables and the underlying data are intentionally withheld here to preserve the report’s role as a single source of truth.
Competitive landscape — how to read the field in 2026
The competitive map combines global R&D leaders with agile regional champions. Established multinational groups are consolidating breeding intellectual property and pursuing scale advantages, while specialized regional players focus on fast, localized product cycles and strong distributor relationships.
-
Multinationals with broad R&D and distribution capabilities (e.g., firms with global vegetable seed divisions) are concentrating on disease-resistance, yield optimization, and seed treatments that simplify farmer adoption—a strategy that favors premium pricing and institutional contracts.
-
Regional specialists and seed houses from India, Africa and Southeast Asia emphasize rapid adaptation to local ecologies and smallholder preferences, leveraging aggressive multiplications and farmer-facing trials to build trust.
-
Smaller heirloom and specialty suppliers focus on niche channels—home garden, specialty retailers and urban agriculture—where differentiated genetics and branding drive margin despite smaller volumes.
Recent industry moves reinforce these dynamics: a major vegetable seed acquisition in India has bolstered breeding capacity and commercial scale; a leading international research center has released new high-yielding okra varieties and relaunched its okra program with a multi-institution working group; and product deployments by regional seed firms underline the continuing importance of locally tuned portfolios. Together, these developments increase competitive pressure on time-to-market and seed availability.
Operational and regulatory dynamics to watch
-
Input availability and costs: Public investments to expand fertilizer production are starting to lower upstream constraints in some markets, but distribution and affordability remain uneven. Firms should model margin sensitivity to fertilizer price and availability scenarios.
-
On-farm practices: Agronomic best practices—such as optimal NPK application regimes and supplemental irrigation scheduling—are material to varietal performance claims. Seed commercialization strategies that bundle agronomy advisory or input packages will see higher adoption rates.
-
Labor constraints and gender dynamics: High hired-labor costs and access barriers for women farmers are critical adoption constraints. Product and channel strategies that reduce labor demand or improve access to credit and seed-on-credit can unlock under-penetrated segments.
-
Regulatory timing: National varietal approval calendars and seed certification processes materially affect launch plans. Aligning registration and multiplication milestones with policy windows reduces go-to-market risk.
How to use these insights in practical planning
-
Scenario-first budgeting: Build three-year budgets assuming both the base-case CAGR and accelerated-adoption scenarios; allocate contingency capital to scale multiplication when early uptake exceeds forecasts.
-
Partnership matrix: Create a tiered partnership map—global breeders for strategic traits, regional multipliers for distribution, and non-profit research partners for access to public germplasm and regulatory navigation.
-
Pilot-to-scale playbook: Design 2026 pilots that test seed treatment, advisory bundles, and low-cost irrigation packages; use pilot ROI to secure buyer commitments and pre-orders for 2027 multiplication volumes.
Next steps and how PW Consulting can support
PW Consulting is prepared to support corporate teams with tailored services that translate these insights into executable plans: custom scenario modeling, M&A and partnership due diligence, channel design, and operational blueprints for seed multiplication and distribution.
To access the full dataset, regional and application-level splits, varietal performance matrices, and the executable playbooks referenced here, visit the PW Consulting report page or contact our Okra Seeds practice. The complete report contains the proprietary tables and annexes necessary to finalize 2026 capex, product, and market-entry decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Okra Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
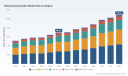
PW Consulting Forecasts Worldwide Wood Gas Generator Market to Reach USD 1,085.75 Million by 2032 on a 6.54% CAGR, with Europe Leading at USD 277.18M in 2025
By pmarketresearch, 2026-07-15
Worldwide Wood Gas Generator Market 2026: Strategic Intelligence for Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Wood Gas Generator Market report — a decision-ready resource for energy executives, industrial planners, technology investors and policy designers preparing for the 2026 planning cycle. Anchored in a rigorous base year of 2025 and a seven-year forecasting horizon to 2032, the study synthesizes historical performance (2020–2025), technology roadmaps, policy signals and commercial operator intelligence to translate a complex, rapidly evolving market into executable options. Our headline macro: the market reached roughly USD 697 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 6.5% through 2032, reaching just over USD 1.08 billion by the end of the forecast period.
Worldwide Wood Gas Generator Market
Why this matters for 2026 strategy
-
Operational resilience and local energy security are rising boardroom priorities. Wood gasification-based CHP and generator systems are uniquely positioned to deliver decentralized, dispatchable energy from locally-sourced biomass — a narrative that shifts investment calculus away from purely centralised renewables for many industrial and rural use-cases.
Worldwide Wood Gas Generator Market -
Policy and capital signals are aligning. Recent public financing and incentive frameworks are lowering implementation risk for early movers, changing the return profile for both project developers and host customers.
Worldwide Wood Gas Generator Market -
Technology modularity and scale diversity give suppliers and integrators multiple routes to market — from small, modular units to industrial installations — creating nuanced opportunity landscapes that demand targeted go‑to‑market strategies rather than one-size-fits-all plans.
What the full report delivers
-
Market sizing and trajectories: We provide an audited historical series (2020–2025), a validated base year (2025) and scenario-driven forecasts to 2032. These are accompanied by sensitivity modelling to test the impact of feedstock price swings, incentive continuation, and carbon pricing trajectories.
-
Technology and performance benchmarking: Comparative performance matrices across gasifier designs and CHP integration approaches, with practical KPIs (efficiency, uptime, maintenance cadence, feedstock flexibility) and a manufacturer-independent roadmap for expected incremental improvements to 2032.
-
Feedstock and supply chain diagnostics: Practical assessment of pellet and chip supply chains, quality control levers, preprocessing requirements and logistics optimisation opportunities that materially affect system economics and uptime.
-
Policy and financing playbooks: Actionable guidance on leveraging national and regional incentive schemes, grant/loan programmes, and green procurement pathways — including illustrative capital structuring options and public-private partnership templates.
-
Commercial use-cases and techno‑economic models: Real-world case studies with modeled cashflows and payback horizons (tailored to industrial heat, off-grid power, and CHP applications) to accelerate underwriting and procurement decisions.
-
Competitive intelligence and vendor selection toolkit: A curated vendor short-list, RFP templates and scoring rubrics to support procurement teams in 2026—designed to reduce selection risk and shorten procurement cycles.
-
Risk matrix and mitigation playbook: Practical mitigations for feedstock volatility, emissions compliance, permitting friction and technology obsolescence, enabling more confident capital allocation.
Market dynamics shaping 2026 decisions
-
Demand drivers: Decentralized energy demand, industrial decarbonisation targets and rural economic development programmes are driving procurement interest from new buyer segments — notably agribusiness, forestry operators and distributed industrial parks.
-
Supply-side evolution: Vendors are differentiating by automation, modularity and fuel-flexibility. System suppliers that can guarantee feedstock quality or provide integrated fuel-prep services enjoy a distinct commercial advantage.
-
Capital access and incentives: Public financing mechanisms are lowering deployment barriers. A recent example is a USDA-backed project financing decision for biomass gasification infrastructure, signalling that government credit support is available for bankable projects that convert forestry waste into energy.
-
Economic trade-offs: For many off-grid or high-diesel-cost settings, on-site biomass gasification offers materially lower energy costs and shortened payback horizons versus conventional generation — an economic swing that underpins many deployment cases we profile.
Competitive landscape — what to watch in 2026
The sector remains commercially diverse: established regional engineering houses sit alongside nimble modular developers and specialist integrators. The market’s vendor ecosystem rewards technical maturity, field reliability, and the ability to couple hardware with fuels and services.
-
Burkhardt GmbH (Mühlhausen, Germany) — A proven developer of modular CHP solutions and pellet/chip-optimised gasifiers. Burkhardt’s iterative process improvements and modular product families position it well for European decentralized heat and power tenders and for customers seeking engineered, turnkey solutions.
-
Spanner Re² GmbH (Germany) — Focused on CO2‑neutral energy from wood waste, Spanner Re²’s expertise in cascaded installations and heating network integration is a differentiator in markets with strong decentralised heat policy incentives.
-
ALL Power Labs (Berkeley, USA) — A leader in small-scale, modular gasifiers with a clear focus on automation and community-scale deployments. Their modular product orientation suits rapid deployment, experimental microgrids and distributed industrial applications.
-
Powermax Renewable Energy (Wuxi, China) — A long-tenured supplier with extensive project experience across scales. Continued industrial-scale product promotion signals competitiveness for larger, utility-adjacent projects.
-
Selected regional players — Manufacturers and integrators from India, Finland, Germany and the USA round out a diverse global supplier base. These firms offer commercially available systems and fertile partnership opportunities for OEMs and EPCs seeking proven hardware.
Competitive positioning in 2026 will pivot less on single-point technology claims and more on integrated value: field-proven uptime, fuel-sourcing guarantees, financing packaging and after-sales service chains.
Strategic recommendations for corporate leaders and investors
-
Prioritise integrated offers. Buyers and financiers prefer suppliers that bundle conversion technology with fuel logistics and performance warranties. If you are a hardware supplier, move quickly to develop bundled service contracts.
-
Invest in feedstock assurance. Securing long-term supply agreements or developing verticalised preprocessing capabilities reduces off-take risk and improves bankability.
-
Use staged deployment to derisk scale-up. Pilot or cascade deployments allow technology validation, local operational competency building and staged capital deployment — a pattern we identify as best practice in our case studies.
-
Leverage public capital where available. Emerging loan guarantee and incentive programmes materially improve economics. Structuring projects to access this capital can shorten payback horizons and improve IRR.
-
Align procurement with emissions accounting. As corporate buyers increasingly target Scope 1/2 reductions, alignment to accepted carbon accounting methods and transparent lifecycle reporting will be a procurement differentiator.
How PW Consulting’s report helps you act in 2026
This report converts market signals into executable options. Beyond headline forecasts (the market is projected from a base of roughly USD 697 million in 2025 to just over USD 1.08 billion by 2032 at ~6.5% CAGR), the deliverable provides sector-specific playbooks: an investor due-diligence checklist, an EPC selection toolkit, and scenario-based cashflow models calibrated to local fuel economics and incentive regimes. That combination of market view plus transaction-level tools is designed to reduce the time from decision to deployment.
Methodology and the limits of this preview
-
Methodology: Quantitative forecasting is built from a bottom-up synthesis of historical shipment and revenue data, vendor interviews, project databases and supply-chain cost modelling. Qualitative inputs come from supplier briefings, policy monitoring and techno-economic pilots.
-
Concentration and fragmentation: While a set of credible specialist vendors leads on technology and integration expertise, the market retains room for new entrants and local champions — a structural reality that favours agile, partnership-led strategies.
-
Scope of this preview: In line with our “trailer” principle, this release highlights strategic implications and high-level market sizing. Detailed segment-level breakdowns, regional and application-specific splits, proprietary vendor scorecards and the full financial model are published within the full report to preserve the integrity of our data and to enable custom downloads for clients.
Next steps
For companies preparing investment memoranda, refining 2026 capex allocations, or designing pilot projects, our full Worldwide Wood Gas Generator Market report provides the granular inputs and executable templates needed to convert strategy into action. PW Consulting is available for tailored briefings and scenario workshops to apply the report’s models to your specific operating context.
Contact PW Consulting to schedule a briefing and obtain access to the complete market dataset, vendor scorecards and the transaction-grade financial models that underpin the full analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Gas Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Localized Temperature Therapy Product Market to Grow from USD 2,345.6 Million in 2025 to USD 3,492.13 Million by 2032 at a 5.85% CAGR
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief: Worldwide Localized Temperature Therapy Product Market — Preview for 2026 Decision-Makers
PW Consulting is pleased to release this strategic preview of our forthcoming Worldwide Localized Temperature Therapy Product Market report. Designed for executives, corporate strategists, product leaders, and M&A teams, this briefing synthesizes the report’s most consequential macro insights and pragmatic implications for 2026 planning cycles. In keeping with our “trailer” approach, we present robust, decision-grade perspective and frameworks while deliberately withholding granular regional and application-level tables to encourage direct engagement with the full dossier and interactive data visualizations on our site.
Worldwide Localized Temperature Therapy Product Market
Executive snapshot
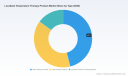
The localized temperature therapy market has demonstrated steady expansion through the 2020–2025 base period and continues to show resilient demand drivers. Our model places the market at approximately USD 2,345.6 Million in 2025 and projects growth to roughly USD 3,492.13 Million by 2032, representing a compounded annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window. Historical momentum, combined with clinical adoption and product innovation, underpins this trajectory.
Worldwide Localized Temperature Therapy Product Market
Market structure is moderately concentrated: the three largest vendors account for roughly 31% of revenue, and the top five together capture just under half of market value — an environment that supports both scale plays and targeted challenger strategies.
Worldwide Localized Temperature Therapy Product Market
Why this matters to corporate strategy in 2026
- Portfolio prioritization: A mid-single-digit CAGR signals attractive growth without runaway expansion — enabling disciplined resource allocation to high-ROI product upgrades, adjacent therapy modules, and services.
- Regulatory time-to-market planning: Many powered cryo/compression devices fall under Class II 510(k) pathways; anticipating submission timelines and clinical evidence needs is critical to meet 2026 commercialization milestones.
- Reimbursement and commercial models: Standard reimbursement pathways exist for therapeutic application (e.g., CPT 97010 posture for hot/cold modalities with a documented national Medicare average), but pathway optimization — bundling, service offers, or facility contracts — materially affects unit economics.
- M&A and partnership timing: Moderate concentration creates opportunities for bolt-on acquisitions that rapidly fill capability gaps (connected platforms, disposables, regional channels) without triggering high multiples seen in hyper-consolidated markets.
- Operational resilience: Companies that act in 2026 to secure supply chains, scalable manufacturing, and regulatory-compliant quality systems (ISO 13485 and IEC 60601 series) will preserve margins as adoption scales.
What the full report delivers — practical, actionable content
PW Consulting’s full report is structured as a working toolkit for the executive team. Highlights include:
- Transparent market-sizing and demand model with year-by-year historicals (2020–2025) and a detailed forecast through 2032, plus sensitivity scenarios tied to clinical adoption and reimbursement changes.
- Competitive landscape with 25+ vendor profiles, strategic positioning matrices, product feature grids, and go-to-market capability assessments. Key firms profiled include Breg, Inc.; Enovis (DJO Global); Össur hf.; DeRoyal Industries, Inc.; and ThermoTek, Inc., among others.
- Regulatory and standards mapping: device classification pathways, 510(k) considerations, CE/MDR implications for EU market entry, and applicable electrical and quality standards (e.g., IEC 60601-1, ISO 13485).
- Reimbursement playbook: payer mapping, coding strategies, and commercial contracting templates that elevate realized revenue per case beyond headline reimbursement rates.
- Clinical evidence sequencing and value dossier templates tailored to acute care, sports medicine, and post-operative recovery use cases.
- Growth playbooks for four strategic archetypes — Platform Leader, Niche Specialist, Channel Challenger, and Service Integrator — with 12–24 month milestone maps and ROI projections.
- An M&A and partnership screening engine that identifies high-impact targets across capability gaps (e.g., disposables, connected device software, regional distribution).
- Interactive dashboards (subscriber-only) allowing users to model alternative market scenarios and export tailored slides for board briefings.
Competitive dynamics: what the leading vendors reveal about market direction
Our vendor analysis shows distinct competitive plays that inform product and commercial strategy:
- Breg, Inc. emphasizes disposable-pad-enabled cold therapy systems tailored to localized post-operative cooling — a model that drives recurring consumable revenue and deepens perioperative relationships.
- Enovis (DJO Global) advances integrated solutions combining active compression with cold therapy (e.g., Game Ready systems), signaling a continued trend toward hybrid therapeutic platforms that deliver differentiated clinical outcomes.
- Össur’s compact units highlight a design emphasis on portability and point-of-care convenience that aligns with ambulatory and outpatient center expansion.
- DeRoyal and ThermoTek demonstrate clinical-grade system strategies targeting hospitals and specialty clinics, including sterile wraps and precision temperature control for vascular and orthopedic indications.
Collectively, these strategic vectors highlight three commercial fault lines for 2026: product-platform convergence (hardware + consumables + software), service and consumable monetization, and outpatient/at-home adoption. Winning companies will combine clinical evidence with channel depth and post-sale service capabilities.
Regulatory, standards and reimbursement realities that shape 2026 execution
- Regulatory: Powered localized cryotherapy/compression devices are generally regulated as Class II under 21 CFR 878.5980 in the U.S., with 510(k) premarket notification requirements. EU market access continues to require conformity with MDR obligations for CE marking.
- Quality & safety: Compliance with ISO 13485:2016 and IEC 60601-1 electrical safety standards is a baseline requirement for clinical adoption and institutional procurement.
- Reimbursement: While hot/cold application codes exist (e.g., CPT 97010 with a national average Medicare reimbursement benchmarking figure), commercial reimbursement strategy must address bundling, facility contracts, and value-based outcome arguments to avoid price erosion.
Material risks and market frictions to monitor
- Evidence gap risk: Devices entering new indications without robust RCT evidence face slow hospital uptake and tougher payer scrutiny.
- Commoditization pressure: Increased supplier activity in low-cost cold packs risks driving margin compression unless offset by differentiated features or services.
- Regulatory volatility: Stricter post-market surveillance requirements in key jurisdictions could lengthen product lifecycle costs and reporting obligations.
- Supply chain and component scarcity: Rapid scale-up without secure supplier agreements can cause production delays and reputational risk in surgical pathways.
Priority actions for 2026 — a checklist for leadership
- Finalize a prioritized three-year product roadmap that sequences clinical studies, regulatory submissions, and consumable commercialization so launch timing aligns with payer engagement.
- Operationalize compliance: certify ISO 13485 systems and align electrical safety testing early in the design cycle to avoid rework.
- Pursue value articulation pilots with high-volume hospital systems to gather outcome data that supports higher reimbursement and formulary placement.
- Evaluate bolt-on M&A targets that accelerate access to disposables, software analytics, or regional distribution rather than pursuing large transformational deals in a moderately concentrated market.
- Develop a pricing architecture that differentiates by channel (inpatient vs outpatient vs home-use) and supports subscription or consumable-anchored pricing where clinically justified.
How to use this preview in board-level decision-making
For the board and executive committees, this preview provides three immediate uses in 2026 planning:
- Risk-adjusted capital allocation: use the market-level CAGR and concentration context to stress-test R&D and M&A budgets against plausible adoption scenarios.
- Regulatory gating decisions: map product launch timelines to 510(k) and MDR submission milestones so commercialization commitments match compliance lead times.
- Go-to-market sequencing: prioritize bundled offers where clinical and commercial evidence can be delivered within 12–18 months to secure early adopter accounts and consumable annuity streams.
Next steps — access the full intelligence
This release is a strategic preview: we intentionally omit detailed regional, type and application breakout tables from this briefing to preserve the actionability of the full dataset. PW Consulting’s complete Worldwide Localized Temperature Therapy Product Market report contains the granular segmentations, downloadable spreadsheets, vendor scorecards, and an interactive forecast engine tailored for executive use. Subscribers also receive a 60‑minute one-on-one briefing with our senior analysts to translate findings into a bespoke 90-day action plan.
To obtain the full report, data dashboards, and subscription options, visit the PW Consulting report page or contact your PW Consulting representative. Our analysts stand ready to support scenario workshops that translate insights into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Localized Temperature Therapy Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
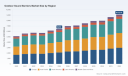
PW Consulting Forecast: Worldwide Outdoor Sound Barriers Market to Reach USD 9,112.18 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Outdoor Sound Barriers Market: Strategic Forecast and 2026 Playbook
Executive summary
As governments and infrastructure owners accelerate efforts to manage environmental noise, the outdoor sound barriers market continues to transition from a commoditized construction accessory to a strategic infrastructure component. PW Consulting’s new market study—anchored on a 2025 base year, a historical review spanning 2020–2025, and a forecast window covering 2026–2032—projects the global market to grow at a compound annual growth rate (CAGR) of 5.06% through the forecast period. The market size in 2025 stood at approximately USD 6,450 Million, with our scenario-driven modelling indicating a trajectory toward roughly USD 9,112 Million by 2032.
Worldwide Outdoor Sound Barriers Market
This briefing is designed as a director-level “trailer”: it highlights the report’s analytical depth and strategic utility for decision-makers preparing budgets, capital allocation, procurement, and M&A workstreams in 2026—while preserving the granular regional, material, and application splits that are available in the full PW Consulting report.
Worldwide Outdoor Sound Barriers Market
Why this market matters in 2026
-
Infrastructure stimulus programs, renewed road and rail investments, and stricter environmental noise requirements are converting sound barriers from optional mitigations into required elements of project specifications.
Worldwide Outdoor Sound Barriers Market -
Material and supply-chain dynamics—most notably volatility in steel and logistics costs—are reshaping supplier competitiveness and product architectures.
-
Technological and regulatory changes (including updates to ISO 9613‑2 and recent EU noise-emission amendments) are raising the technical bar for acoustic engineering and procurement documentation; compliance is now a source of competitive advantage.
Market dynamics and structural drivers
Our analysis identifies three structural drivers that will define strategic outcomes in 2026:
-
Demand-side push from infrastructure and urban mitigation projects, supported by public policy and local noise limits—driving steady top-line growth consistent with the 5.06% CAGR in our forecast.
-
Input-cost pressure, particularly from steel. Independent industry measures reported a near-double-digit annual uplift in steel averages by the end of 2025, with U.S. steel price benchmarks stabilizing in mid-2025—creating margin and product-design stress for metal-heavy offerings.
-
Standards and measurement changes: the ISO 9613‑2:2024 update and recent EU delegated regulations tighten measurement and reporting expectations. Buyers will demand verifiable attenuation figures and end-to-end compliance documentation, shifting value toward suppliers that integrate acoustic modelling, certification, and lifecycle performance guarantees.
Competitive landscape: patterns and strategic positioning
The outdoor sound barriers market remains fragmented: the top suppliers account for a relatively small share of the total market, leaving room for regional specialists, rental providers, and system integrators. Our report profiles the market’s leading players and distills their strategic positions:
-
Sound Fighter Systems (United States): a long-tenured specialist in fully absorptive, high-performance walls. Their strength lies in engineering-led solutions for highways and heavy infrastructure—appealing to project owners seeking performance-certified attenuation.
-
AIL Sound Walls (Canada): known for turnkey absorptive and reflective systems aimed at municipal and residential projects; a strong lifecycle-service orientation positions them well where municipalities seek single-source responsibility.
-
Echo Barrier (United Kingdom): the market leader in temporary and portable acoustic barriers. Echo Barrier’s rental and rapid-deploy model is disruptive for construction, events, and short-term mitigation, and it will increasingly capture early-stage project spend.
-
Kinetics Noise Control (United States): a product-focused manufacturer with lightweight panel systems. Their innovation in panelization and modularity reduces installation time and can mitigate some raw-material cost exposure.
-
IAC Acoustics (United States): notable for recent launches in continuous exterior barrier systems. Established engineering resources and a product pipeline make them a contender on technically demanding projects.
-
Other specialist players (Noise Barriers, ArtUSA, Acoustiblok, Acoustic Sciences Corporation, Sound Seal): each brings differentiated capabilities from custom industrial enclosures to retrofit fence inserts and high wind-load fencing—highlighting a market where product specialization and application focus drive margins.
Recent vendor activity reinforces these dynamics: product releases and trade-show visibility from core players during 2025–2026 signal a mix of incremental product innovation, greater emphasis on retrofit solutions, and continued growth of temporary barrier offerings. The market is therefore bifurcating between engineered, long-life systems for infrastructure owners and fast-deploy rental/retrofit solutions for time-bound projects.
Strategic implications for 2026—what executives should do now
Leaders preparing 2026 strategies must translate market trends into executable actions. Below are high-impact priorities we recommend based on our analysis.
-
Hedge raw-material exposure and redesign where possible. Suppliers with heavy steel content should prioritize modular designs that reduce per-linear-meter steel intensity, explore alternative materials or coatings, and sign forward contracts or index-linked supplier agreements to stabilize margins.
-
Embed regulatory compliance and acoustic validation in the value proposition. With ISO and EU method updates, successful vendors will offer certified acoustic modelling, on-site validation, and contractually guaranteed attenuation performance.
-
Pursue service-led and hybrid business models. Rental, maintenance, and performance-based contracts (e.g., guaranteed dB reduction) drive recurring revenue and lock in project owners—especially for temporary and urban retrofit segments.
-
Invest in digital acoustics capabilities. Integrating computational acoustic simulation, GIS-linked noise mapping, and digital twin approaches accelerates bid-to-proposal cycles and reduces underwriting risk for guaranteed-performance offers.
-
Prioritize customer segments and localize supply. Given the market’s fragmentation, regional manufacturing and logistics hubs reduce lead times and cost volatility—an especially powerful lever for bidders on public infrastructure contracts.
-
Assess M&A and partnership opportunities with a disciplined lens. Fragmentation creates buy-and-build opportunities in regional markets, rental fleets, or niche retrofit technologies; buyers should prioritize targets that add complementary channels, engineering IP, or fleet capabilities.
What PW Consulting’s full report delivers (practical, board-room ready)
The complete Worldwide Outdoor Sound Barriers Market report is built for executives and deal teams. Key deliverables include:
-
Market sizing and outlook (historical 2020–2025, base year 2025) with scenario and sensitivity analysis across the 2026–2032 forecast horizon.
-
Detailed segmentation by region, material type, and application—presented with demand drivers, supplier maps, and tender-level dynamics (note: detailed splits are available only in the full report).
-
Competitive profiles and capability matrices for leading global and regional players, including recent product launches, go-to-market models, and strategic intent indicators.
-
Procurement and cost-model playbooks—unit cost benchmarking, bill-of-material drivers, and contract templates to accelerate RFP responses and lifecycle-cost evaluations.
-
Regulatory and standards matrix—practical checklists to ensure compliance with ISO 9613‑2:2024 and recent EU regulations, plus recommended language for contractual attenuation guarantees.
-
Strategic recommendations and actionable 100‑day plans for suppliers, contractors, and investors, including M&A screening criteria and integration checklists.
Closing view: positioning for resilience and growth
The outdoor sound barriers sector is entering a phase where technical performance, supply-chain resilience, and commercial model innovation will determine winners. The market’s steady mid-single-digit growth offers attractive expansion opportunities—but also raises the bar on operational and engineering excellence. For 2026, organizations that proactively manage raw-material exposure, embed compliance and measurement into their products, and evolve toward service-oriented revenue will capture disproportionate value.
PW Consulting’s full report contains the granular forecasts, regional and product splits, company financials, and procurement tools needed to operationalize these conclusions. For access to the complete dataset, scenario models, and bespoke advisory engagements, please visit our report page or contact your PW Consulting account director.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Sound Barriers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide TRIS Buffer Market Poised to Hit USD 498.29 Million by 2032, Growing at a 6.32% CAGR
By pmarketresearch, 2026-07-15
Worldwide TRIS Buffer Market — Strategic Preview for 2026 Decisions
PW Consulting’s newest market research preview on the Worldwide TRIS Buffer Market delivers a compact, decision-ready briefing for executives, procurement leaders, and R&D strategists preparing plans in 2026. Drawing on an extended historical series (2020–2025) and a seven-year forecast horizon (2026–2032), this analysis synthesizes commercial, supply-chain, regulatory, and competitive signals that will materially affect sourcing, pricing, and investment choices for biological-grade and industrial TRIS products.
Worldwide TRIS Buffer Market
Why this preview matters to 2026 strategy
- Actionability: The report translates market dynamics into practical options — procurement hedges, supplier playbooks, and contingency scenarios — so you can move from insight to implementation during the year ahead.
- Timing: With macro momentum and regulatory inflection points materializing in 2026, the choices made this year will determine cost exposure and capacity access through the next planning cycle.
- Focus: We spotlight risk vectors that most commonly derail TRIS-dependent programs — raw-material volatility, concentrated production nodes, and evolving trade remedies — and provide decision trees to prioritize mitigation investments.
Market trajectory — macro facts you can act on
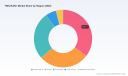
At the macro level, the TRIS buffer market has demonstrated steady expansion across the 2020–2025 period, growing from a defined base to a significantly larger market in the 2025 base year (reported in USD Million). Our modeling projects continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.32%, reaching an estimated market size by 2032 that represents a material upside to current capacity plans. These headline dynamics create a planning imperative for firms whose workflows or product pipelines depend on TRIS buffers.
Worldwide TRIS Buffer Market
Two strategic implications follow immediately. First, buyers should expect upward pressure on availability and premiums for higher-purity grades unless supply-side capacity is actively expanded or demand-side substitution accelerates. Second, the market scale and steady CAGR justify targeted investments in supplier qualification, dual-sourcing contracts, and inventory optimization for organizations that cannot tolerate disruption in nucleic-acid workflows, protein purification, or bioprocess buffers.
Worldwide TRIS Buffer Market
Supply-side dynamics and raw-material signals
Our industry diagnostics identify three supply-side drivers that will shape 2026 outcomes:
- Capacity versus consumption balance: Global production capability for the underlying chemical reached industry-scale volumes in recent years, and available evidence shows that installed capacity has historically sat only modestly above consumption. That cushion gives manufacturers limited room to absorb demand spikes without invoking price adjustments or allocation logic.
- Input-cost sensitivity: Nearly one-third of producers report raw-material cost fluctuations as a primary constraint on both production intensity and price stability. For buying organizations, this translates into an elevated probability of mid-cycle price renegotiations unless contracts include explicit indexation or fixed-price windows.
- Quality segmentation: Downstream users increasingly differentiate between analytical/biological grades and industrial grades. Premium supply chains for life-science applications remain concentrated among vendors that operate to recognized quality systems and compendial standards; as a result, lead times and qualification overheads for high-purity TRIS remain higher than for commodity grades.
Regulatory and trade environment — a 2026 inflection
Regulatory activity has heightened systemic risk in the TRIS market. In 2026 a major North American manufacturer initiated antidumping and countervailing duty actions that, if sustained, could lead to steep tariff overlays on certain import flows. That petition alleges very large dumping margins and signals an elevated chance of trade remedies that would reallocate demand toward domestically produced and regionally sourced inventory.
For corporate decision-makers, the practical consequence is clear: procurement strategies that were optimized for a low-tariff environment must be stress-tested for scenarios that include import restrictions and sudden shifts in landed cost. The report provides a pragmatic regulatory risk matrix and scenario templates that quantify the impact of tariff-like measures on landed cost, supplier scores, and switching thresholds.
Competitive landscape — who matters and why
The TRIS market displays moderate concentration, with the top-tier suppliers capturing a meaningful share of commercial volumes while a broader set of regional producers supply differentiated grade and packaging options. A compact set of global incumbents and specialized manufacturers control critical capacity and certified grades; their strategic moves will influence supply reliability and price dynamics into 2026 and beyond.
- Integrated, dual-site manufacturers — exemplified by a fully integrated supplier operating production facilities in North America and Europe — provide resilience for regulated customers through regional manufacturing redundancy and ISO-certified quality systems. Recent capacity additions and product-line expansions by such players have strengthened their position in regulated supply chains.
- Regional specialty producers in Asia supply large volumes across multiple purity tiers and remain an essential source of scale for global buyers. These suppliers are the backbone of commodity availability but face increasing scrutiny from cost- and standards-driven buyers when qualification for bioprocess-grade materials is required.
- Large lab-supply and life-science distributors and brands retain outsized influence over channel dynamics and customer access. Their extended product catalogs, distribution networks, and value-added services (e.g., custom buffer formulation, smaller package sizes, and traceable quality testing) make them preferred partners for research and clinical laboratories seeking fast fulfillment and technical support.
The full report contains detailed supplier profiles, capacity maps, and a five-point supplier-risk scoring model that synthesizes quality certifications, manufacturing footprint, regulatory exposure, and supply-chain flexibility — a practical toolset for developing sourcing strategies that balance cost, lead time, and compliance.
Recent industry developments that change the playbook
- Capacity investments: Several suppliers expanded production capabilities or buffer-preparation capacity in 2025 and 2026, a response to demand growth in life sciences and to customers seeking regional supply assurance.
- Channel realignment: New and expanded distribution agreements across North America and Europe are shortening time-to-market for certain high-purity buffer portfolios, while also introducing contractual interdependencies that merit closer review in procurement negotiations.
- Trade-action risk: The filing of trade remedy petitions in 2026 has already changed risk-appetite for some buyers; contingency sourcing plans and supplier diversification strategies are now moving from “nice to have” to “table stakes.”
What PW Consulting’s report delivers — practical content summary
This preview is purpose-built to motivate and guide executive action. The full report (base year 2025, forecast through 2032) contains the following operational modules designed for immediate use by strategy, procurement, and product-development teams:
- Demand-modeling engine: A configurable model that maps use-cases to volumes and stress-tests demand under scenario assumptions (pandemic re-runs, accelerated therapeutic pipelines, tariff events).
- Supply-mapping and capacity dashboard: Geospatial overlay of certified manufacturing assets, lead-time bands, and grade capabilities to support dual-sourcing and nearshoring decisions.
- Price-sensitivity and cost-to-serve analysis: Indexed cost scenarios that incorporate raw-material volatility and common supplier contract terms.
- Quality and regulatory playbooks: Checklists and qualification templates for ACS/ISO/cGMP claims, plus a regulatory risk matrix for trade-remedy scenarios and import compliance.
- M&A and CAPEX scoring: A rapid due-diligence framework to evaluate acquisition targets, tolling partners, and greenfield investments against demand forecasts and strategic fit.
- Procurement negotiation toolkit: Template SLAs, penalty structures, and inventory policy algorithms tailored to TRIS-grade distinctions.
How to use the intelligence — five recommended next moves for 2026
- Conduct a quick supplier-stress test: Use the supply-mapping output to identify single points of failure for any grade of TRIS used across your product and research portfolio.
- Lock a short-duration hedge on premium volumes: For organizations with low tolerance for quality-risk, secure fixed-price or capped-price windows for a portion of demand while maintaining spot flexibility for the remainder.
- Qualify a secondary regional supplier now: Even a limited qualification program reduces exposure to regulatory or logistical chokepoints and is typically faster and cheaper than emergency onboarding later.
- Integrate regulatory scenarios into procurement playbooks: Add simple decision gates that trigger alternative sourcing or inventory actions when trade-remedy or antidumping case statuses cross predefined thresholds.
- Use the M&A scoring tool for vertical options: If supply security is strategic, the scoring framework helps rapidly assess whether acquisition, tolling agreements, or long-term capacity investments make sense relative to outsourcing.
Conclusion — why 2026 is a strategic inflection year
The TRIS buffer market’s steady growth and the concentration of certified production capacity create both opportunity and risk. Growth justifies investment in resilience and supplier relationships; regulatory motion and input-cost volatility demand operational rigor. PW Consulting’s report is designed to turn macro visibility — a clear CAGR and multi-year market trajectory — into micro-level decisions: who to qualify, how much inventory to hold, and when to invest in capacity versus contract protection.
For sourcing leaders and corporate strategists, the most valuable edge in 2026 will be the ability to translate market-scale signals into executable supplier and procurement strategies before adversarial events (tariffs, capacity shortfalls, or raw-material spikes) force rationing decisions. Our full report equips teams with the models, playbooks, and supplier intelligence required to make those calls with confidence.
Get the complete intelligence
This preview is intentionally high-level to highlight the strategic thrusts and operational levers that matter most. The full Worldwide TRIS Buffer Market report provides the granular segmentation, supplier scoring, and downloadable decision tools that procurement, R&D, and corporate development teams will use to operationalize the recommendations above. Visit our report page to access full data tables, scenario models, and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com