

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 8.52% CAGR for Worldwide Indoor Lighting Control Systems Market, Driven by Wireless and Commercial Adoption

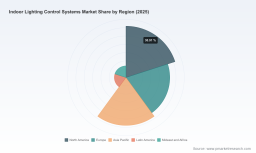
Worldwide Indoor Lighting Control Systems Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s newest market study on Worldwide Indoor Lighting Control Systems synthesizes five years of historical performance and a seven‑year forecast to deliver a decision‑grade view for corporate strategy teams, investors, and procurement leaders. Anchored on a 2025 base year and modeled through 2032, the study quantifies the market trajectory and pairs that with operational intelligence you can act on in 2026 — while reserving the granular segment tables and regional breakouts for the full report.
Worldwide Indoor Lighting Control Systems Market
Why this briefing matters for 2026 strategic planning
- The indoor lighting control systems market is transitioning from a cost‑reduction play to a systems‑level value proposition that ties lighting to buildings’ operational intelligence. Our market model—built from 2020–2025 historicals and projecting 2026–2032—shows sustained expansion at a compound annual growth rate (CAGR) of approximately 8.5%. This makes lighting controls a growth category deserving of capital and organizational attention in 2026.
- For executives weighing retrofit vs. new‑build strategies, procurement of sensor networks, or alliances with platform providers, the timing is critical: the market moves from product sales to platform and recurring‑revenue services. The 2025 market baseline and our forward curve enable finance teams to size near‑term opportunity and stress‑test revenue scenarios under multiple adoption speeds.
- Our analysis emphasizes where commercial outcomes (energy savings, occupant wellbeing, operational automation) align with regulatory and standards momentum—creating pockets of predictable demand that should inform go‑to‑market prioritization in 2026.
Key macro picture (what the numbers tell you)
Mapping five years of observed outcomes into a seven‑year forecast yields a clear narrative: demand for indoor lighting controls is resilient and accelerating as IoT integration, energy regulation, and LED proliferation converge. With a 2025 market baseline and a projected average growth near 8.5% over the forecast horizon, organizations can anticipate both scale and upgrading cycles rather than one‑time transactions. This trajectory favors vendors and integrators that can convert one‑off installations into managed services and analytics subscriptions.
Worldwide Indoor Lighting Control Systems Market
Practical, decision‑grade deliverables inside the full report
- Robust market sizing and scenario models (base case, adoption‑accelerated, and constrained scenarios) calibrated to historical 2020–2025 performance and validated against vendor reporting.
- Channel and procurement playbooks showing how to structure contracts that capture value across hardware, installation, integration, and recurring software/analytics streams.
- Technology adoption roadmaps for wired, wireless, and hybrid deployments — including migration patterns from legacy dimming protocols to DALI‑2 and IP‑native controls.
- CapEx/Opex comparison templates for retrofit vs. greenfield decisions that tie lighting control investments to payback timelines and ESG reporting metrics.
- Supplier selection framework with weighted criteria (technical interoperability, standards compliance, cybersecurity posture, financing options, and lifecycle services).
Note: the summary above is deliberately high‑level. The full report contains the granular regional, technology, and application splits, as well as detailed supplier scorecards and proprietary unit‑price models.
Worldwide Indoor Lighting Control Systems Market
Market dynamics shaping 2026 execution
- Regulatory tailwinds are tangible. European energy efficiency mandates and North American building energy codes increasingly require automated control strategies as part of compliance. For procurement teams, this equates to mandatory functionality rather than competitive differentiation — and it shortens the sales cycle for compliant solutions.
- Standards convergence (notably DALI‑2 and KNX certification proliferation) reduces integration risk for multi‑vendor projects and accelerates enterprise adoption. Interoperability standards lower switching costs and make platform openness a competitive advantage for vendors.
- Sensor economics and supply dynamics matter. Component costs (for example, commodity PIR occupancy sensors) have compressed margins on basic controllers but created opportunities for value capture higher in the stack—analytics, asset management, and integration services.
- Wireless protocols and mesh technologies continue to displace dedicated wiring in many retrofit scenarios, turning constrained installation budgets into addressable opportunities for innovative vendors with robust commissioning toolsets.
Competitive landscape — what to watch in 2026
The competitive field blends large multinational electrical and building automation firms with specialized lighting control vendors. The market is moderately concentrated: a number of well‑established global firms command leadership positions, but the remainder of the market remains accessible to focused challengers and regional integrators. Key players profiled in the study include:
- Signify (Eindhoven, Netherlands) — an IoT‑led approach centered on the Interact platform, combining sensors, gateways, and cloud management for commercial buildings.
- Lutron Electronics (Coopersburg, PA, USA) — a long‑standing specialist in both wired and wireless controls, with solutions tuned for home and commercial automation.
- Acuity Brands (Atlanta, GA, USA) — multi‑channel offerings that bridge wired and wireless architectures and emphasize certified interoperability.
- Schneider Electric (Rueil‑Malmaison, France) — building‑wide IoT integration that positions lighting as one domain within converged building management.
- Legrand, ABB, ams‑OSRAM, Tridonic, Helvar, Eaton, Delta Electronics, and Hubbell Lighting — each with targeted strengths in protocol support, aftermarket components, DALI ecosystems, or integration services.
Our vendor analysis does more than list logos: it assesses product roadmaps, platform openness, channel reach, and the ability to support enterprise‑grade cybersecurity and lifecycle services. The full vendor matrix in the report includes a capability scorecard and suggested partnership archetypes for OEMs and systems integrators.
Notable recent developments that shape 2026 tactics
- Product innovation: Major players have introduced AI‑enabled occupancy sensing and node‑based wireless products that simplify commissioning and reduce per‑installation labor.
- Protocol upgrades: Vendors are shipping products with native DALI‑2, Thread, and other IP‑friendly protocols—lowering integration friction with building management and IoT platforms.
- Certifications: DALI‑2 certifications and other standard milestones reduce perceived risk for enterprise buyers and unlock larger contracts tied to compliance roadmaps.
These developments imply that buyers should prioritize solutions with modular upgrade paths and vendors that demonstrate cadence in firmware and cloud feature delivery.
Strategic implications and recommended actions for 2026
- Procurement: Move beyond lowest‑price RFPs. Include interoperability, long‑term support, and data ownership clauses. Our pricing and TCO models enable procurement teams to quantify the true lifetime cost for managed vs. transactional engagements.
- Technology roadmaps: Favor vendors committed to standards and with documented upgrade paths for wireless and IP‑native deployments. That reduces risk of stranded assets as standards evolve.
- Partnerships and M&A: Mid‑market integrators and component specialists remain attractive targets for larger platform providers seeking to accelerate field‑installation capabilities and local market penetration.
- Service design: Design offers that bundle analytics, energy reporting, and predictive maintenance. The market shift from hardware to services means margin pools increasingly favor software and managed services.
- Pilots and scaling: Use a "pilot to program" approach—validate interoperability and data flows on small installs, then scale geographically. Our implementation playbooks show typical timeline, resource needs, and acceptance criteria.
How the report supports boardroom decisions
Boards and C‑suites can use the report to: (1) calibrate capital allocation for smart building investments, (2) set go‑to‑market priorities for product and channel investments, and (3) assess acquisition targets against a quantified market size and trajectory. The study’s scenario engine helps quantify revenue sensitivity to price, adoption rate, and regulatory tightening — all of which drive valuation multiples for vendors and integrators in the space.
Methodology and reliability
The study combines top‑down macro assessment with bottom‑up revenue build‑ups, validated against vendor disclosures, procurement datasets, and primary interviews with integrators and facility managers. Our base year is 2025; historical coverage spans 2020–2025 and the forecast extends 2026–2032. Financials are presented in USD (Million). We apply sensitivity analysis to test outcomes under optimistic and constrained adoption paths, and we document assumptions transparently so you can re‑run scenarios with your own inputs.
Limitations and where to go for the full intelligence
This briefing emphasizes the strategic narrative and selective macro datapoints to illuminate decision paths. It intentionally does not include the full regional and application‑level tables, granular pricing models, or the vendor scorecard detail. Those elements are included in the full study and supporting data pack, which is designed for procurement, product, and M&A teams that require line‑item granularity.
Next steps
- For procurement teams: Request the TCO templates and vendor scorecard annex to start vendor shortlisting in Q1 2026.
- For product and engineering: Access the protocol adoption maps and technology migration timelines to prioritize integration workstreams.
- For M&A and strategy teams: Use the scenario engine in the report to stress‑test target valuations under different adoption and regulatory outcomes.
PW Consulting’s Worldwide Indoor Lighting Control Systems Market report is tailored to turn uncertainty into actionable plans for 2026. For full market tables, segmented forecasts, supplier scoring, and downloadable models, consult the full report and data pack on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Indoor Lighting Control Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com