

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Modern AI Infrastructure to Surge from USD 312.6B in 2025 to USD 1.68T by 2032 at a 27.14% CAGR

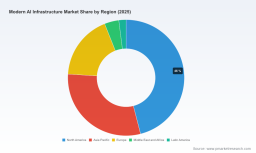
Worldwide Modern AI Infrastructure Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research, Worldwide Modern AI Infrastructure Market (base year 2025), synthesizes a fast-evolving ecosystem into actionable guidance for CIOs, CTOs, procurement leads, and boardrooms planning capital allocation in 2026. The market reached USD 312.6 Billion in 2025 and is forecast to expand at a 27.14% CAGR through 2032, reaching approximately USD 1.68 Trillion by the end of the forecast window. That pace of expansion, combined with shifting supply dynamics, regulatory constraints and infrastructure bottlenecks, makes 2026 a pivotal year for strategic choices that will determine competitive positioning for the remainder of the decade.
Worldwide Modern AI Infrastructure Market
Why 2026 Is an Inflection Point
The macro picture driving urgency in 2026 is clear: hyperscalers and major cloud providers are committing record capital to AI infrastructure, industrial-scale GPU deployments continue to concentrate demand, and semiconductor and systems suppliers are racing to expand capacity. Public signals from the hyperscalers point to combined capex guidance that will materially outstrip historical norms, while suppliers are negotiating supply agreements and strategic partnerships to secure long-lead components.
Worldwide Modern AI Infrastructure Market
At the same time, non-market constraints are shaping deployment timelines. Power availability, grid interconnection queues and long lead times for large electrical transformers are now frequently the binding constraints on new AI data center capacity. Delays measured in quarters — and in some cases years — are being reported for projects originally scheduled for 2026, shifting practical deployment windows into 2027–2028 unless mitigations are in place. Material intensity (wiring, cooling infrastructure and specialty copper) and the need to integrate liquid cooling and advanced power distribution systems are elevating the capital and delivery complexity of every new build.
Worldwide Modern AI Infrastructure Market
Regulatory dynamics add another layer of strategic risk. Export controls on advanced computing integrated circuits and new limits on frontier AI model artifacts introduce shipping and licensing complexity that can affect supplier selection, geographic sourcing, and contractual terms. Compliance strategies will now need to interleave export licensing, supplier audits and operational segregation to avoid business disruptions.
What the Report Delivers — Practical, Actionable Intelligence
- Robust sizing and forecasting anchored to historical trends (2020–2025) and forward-looking scenarios (2026–2032), with transparent methodology and sensitivity tests tuned to capex cycles, component lead times, and regulatory shocks.
- Operational segmentation by component, deployment model and infrastructure topology, coupled with deployment playbooks and TCO templates tailored for cloud-native, hyperscale colocation, enterprise data center and edge AI use cases.
- Vendor landscape maps, risk heatmaps and procurement scorecards that prioritize suppliers by capability, scale-readiness, and supply-chain resilience.
- Scenario-based procurement and financing strategies (including capex vs. opex trade-offs), together with contract clauses and insurance approaches to hedge against delivery slips driven by power and materials constraints.
- Technical appendices: cooling and power design benchmarks, ISO/IEC 30134-aligned energy and water performance KPIs, and a checklist for integrating next-generation accelerators and networking fabrics into existing operations.
To preserve strategic advantage for clients and partners, the public preview intentionally omits detailed segment tables and split-level sizing; those granular models and vendor scorecards are available in the full report and interactive dashboards.
Competitive Landscape — Who Matters and Why
The market remains concentrated among a small set of suppliers and platform operators, and the competitive calculus is increasingly a function of both silicon and systems capability plus the ability to deliver scale fast. Concentration metrics in our analysis indicate that the top three suppliers control a dominant portion of addressable value, and the top five capture an even larger share — a structure that creates acute supply-risk and pricing leverage for those incumbents.
- NVIDIA Corporation — The de facto leader in accelerator ecosystems, offering not just chips but an extensive software and networking stack that underpins many large-scale training clusters. Its partnerships and supply agreements are materially influencing availability and architecture choices across the market.
- Advanced Micro Devices (AMD) — Competing with optimized accelerator lines and driving alternative high-throughput architectures for HPC and AI clusters, particularly in heterogenous deployments.
- Intel Corporation — Bringing CPU and accelerator portfolios to the data center, with a particular emphasis on integrated platform solutions that target enterprise and hyperscale operators.
- Broadcom Inc. and Arista Networks — Critical providers of high-speed interconnects and switching fabrics; their roadmaps determine the performance envelope of clustered accelerators.
- Hyperscalers (AWS, Microsoft Azure, Google Cloud, Oracle) — Beyond cloud services, these firms are both major buyers and innovators: custom silicon, managed infrastructure offerings and capacity reservations are reshaping procurement options for enterprises.
- TSMC and the foundry ecosystem — The ultimate bottleneck for advanced process nodes; wafer capacity and priority allocations to large customers are a defining constraint on new accelerator availability.
- Specialized providers (CoreWeave, Cerebras, Groq, Vertiv, Equinix) — Niche and ancillary players that offer differentiated pathways: high-density GPU clouds, wafer-scale solutions, inference-optimized LPUs, and infrastructure services (power, cooling, colocation).
Recent Market Signals That Matter for Procurement
- Major investment and supply agreements between accelerators and leading AI model operators indicate prioritized allocation to certain customers and use cases — buyers should assume constrained spot availability and plan contractual commitments accordingly.
- Large-scale financing plans by cloud platform operators to expand capacity reflect a wave of near-term demand; enterprises should evaluate capacity reservation options or consider hybrid approaches to avoid vendor-backed queuing.
- Emerging IP and productization in modular, liquid-cooled, high-density edge/containerized data centers point to alternative deployment routes for latency- or data-sovereignty-sensitive workloads.
Key Risks and Operational Constraints for 2026 Deployments
Our fieldwork and supplier interviews highlight five operational constraints that require immediate attention by enterprise planners:
- Power and Grid Interconnection: multi-year wait times for key electrical components and interconnection slots are now commonplace. Expect project schedules to slip without early engagement with utilities and flexible contracting clauses.
- Material and Component Lead Times: copper-intensive builds, specialty transformers, and bespoke cooling loops have long procurement tails. Inventory strategies and supply agreements are essential.
- Regulatory and Export Controls: evolving export controls on advanced computing items and frontier model artifacts increase compliance complexity for cross-border operations and supplier selection.
- Vendor Concentration Risks: a small number of suppliers control critical stack elements — diversifying across architecture families and engaging alternative accelerator vendors reduces single-source exposure.
- Sustainability and Standards Compliance: ISO/IEC 30134-series metrics are becoming contractual and investor requirements; energy and water efficiency planning is now operational risk management.
Timing and CapEx Strategies — How to Respond in 2026
Enterprises should treat 2026 as a year to shift from opportunistic procurement to strategic capacity planning. Practical approaches include:
- Immediate site readiness audits that focus on power, cooling and interconnect permit paths.
- Workload mapping to determine which models and inference tasks are best suited to hyperscale cloud, specialized GPU clouds, colocation or on-prem deployments.
- Tiered contracting strategies: a mix of short-term cloud capacity, medium-term reserved instances/commitments, and long-term build contracts with phased delivery.
- Supplier engagement playbooks that include export-compliance clauses, option windows for accelerated delivery, and staged payment tied to performance milestones.
- Financial hedging: scenario-driven ROI models that explicitly incorporate delivery slippage, energy-cost shocks and carbon compliance costs.
Recommended First Moves for Executive Teams
- Commission an immediate 90-day infrastructure readiness program focused on power and site interconnects.
- Map critical AI workloads to an infrastructure taxonomy and prioritize those workloads for reserved capacity procurement.
- Negotiate flexible supplier agreements that account for export-control risk and allow for architectural fallbacks.
- Pilot advanced cooling and modular data-center solutions where speed-to-deploy and density matter most.
- Embed sustainability KPIs aligned to ISO/IEC 30134 into procurement scorecards and vendor SLAs.
PW Consulting’s Worldwide Modern AI Infrastructure Market report is designed to support these actions with the granular models, vendor scorecards, procurement templates, and scenario analyses that senior leaders need to operationalize decisions in 2026. This preview outlines the strategic landscape and operational imperatives; the full report and interactive dashboards contain the detailed split-level sizing, regional breakdowns, vendor benchmarking matrices and implementation playbooks required to execute with confidence.
For enterprise teams preparing 2026 budgets and long-term AI infrastructure strategies, the choice is between reactive sourcing — accepting unpredictable delivery windows and higher total cost — and proactive, model-driven procurement that secures capacity, manages regulatory exposure, and aligns deployments to sustainability and performance targets. PW Consulting’s full report provides the decision-grade intelligence to take the proactive path. Visit PW Consulting’s research portal to access the full report, data visualizations and bespoke advisory packages.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com