

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Automotive Engine Oil Additives Market Set to Expand at a 3.21% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-15
Worldwide Automotive Engine Oil Additives Market — Strategic Preview for 2026 Decision-Makers
Executive summary
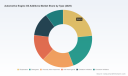
PW Consulting’s latest market study on the Worldwide Automotive Engine Oil Additives Market delivers a pragmatic, decision-ready intelligence package tailored for C-suite and business-unit leaders planning for 2026. Our base-year assessment (2025) and a seven-year forecast (2026–2032) combine a rigorous market-sizing exercise with a forward-looking strategic playbook. The market has expanded from roughly USD 15.2 billion in 2020 to about USD 18.0 billion in 2025, and our model projects continued growth through 2032, reaching approximately USD 22.5 billion under the central scenario — an implied compound annual growth rate of 3.21% for the forecast period. Competitive dynamics remain concentrated (CR3 ~62.5%; CR5 ~81.2%), underscoring that a relatively small set of global players will continue to shape pricing, technology adoption, and standards compliance.
Worldwide Automotive Engine Oil Additives Market
Why this matters for 2026
-
Standards and regulations that became effective in 2025 and subsequent clarifications in 2026 materially alter the product and commercialization roadmap for additive suppliers and oil marketers. The transition window extended by standards bodies into late 2026 creates both tactical opportunities and strategic risks for market entrants and incumbents.
Worldwide Automotive Engine Oil Additives Market -
Volatility in base oil and additive feedstock pricing, driven by geopolitical events and supply-chain disruptions, has compressed margins and forced rapid re-prioritization of sourcing and hedging strategies in early 2026.
Worldwide Automotive Engine Oil Additives Market -
Technological expectations — notably around fuel-efficiency gains, low-speed pre-ignition (LSPI) mitigation, and reduced SAPS formulations — are now explicit procurement criteria for many OEMs and oil marketers, shifting R&D and commercialization calendars.
Market dynamics — what’s changing
Three broad forces are shaping the 2026 decision landscape for engine oil additive suppliers:
-
Regulatory and standards evolution: The introduction and adoption of the latest passenger car motor oil specifications (licensing effective in 2025) and companion API categories (including a new category addressing ultra-low viscosity grades) raise the technical bar for additive packages. The standards bodies’ decision to extend overlap periods into 2026 gives manufacturers extra runway but raises risk for those that delay.
-
Raw-material and cost pressures: Early 2026 saw base oil and additive costs spike due to geopolitical tensions and supply-chain constraints, with industry reports noting finished-lubricant and component price increases approaching the high teens in percentage terms. That environment favors suppliers with strong procurement sophistication, regional sourcing flexibility, or integrated upstream exposure.
-
Structural demand shifts: Vehicle electrification and hybridization create a complex demand profile. While full battery-electric vehicles reduce engine-oil demand for those powertrains, hybrid powertrains and a global vehicle parc that still includes a large installed base of internal-combustion engines preserve sizeable demand — but with altered product specifications and longer replacement cycles.
Competitive landscape — players to watch
The engine oil additives market remains technology- and relationship-driven. Our competitive assessment synthesizes public disclosures, standards participation, and product launches to highlight where advantaged players are focusing in 2026.
-
The Lubrizol Corporation (Wickliffe, Ohio): A large global supplier with recent launches that target compliance with the latest passenger car specifications. Their product cadence and strong OEM relationships make them a primary benchmark for additive performance and time-to-market.
-
Infineum International Limited (Abingdon, UK): Leveraging joint-venture scale and expertise in fuel-efficiency technologies, Infineum is focused on formulations that mitigate LSPI and align with ultra-low viscosity demands.
-
Afton Chemical Corporation (Richmond, Virginia): Broad focus across passenger-car and heavy-duty formulations with emphases on driveline and fuel-additive synergies that matter for hybrid platforms.
-
Chevron Oronite Company LLC (San Ramon, California): With a strong OEM-approval portfolio, their branded OLOA technologies remain relevant for companies seeking global compliance pathways.
-
BASF SE, Evonik Industries AG, LANXESS AG, Croda International, Vanderbilt Chemicals : European and specialty-chemistry players that bring critical competencies in antioxidants, viscosity-index improvers, bio-based friction modifiers, and extreme-pressure chemistries.
-
Selected China-based producers : Regional suppliers with high-volume manufacturing and cost-competitive positions that increasingly support global OEM supply chains and domestic mixer-customers.
These firms are deploying a mix of product development, standards engagement, and selective regional capacity investments. Recent notable developments include targeted product launches aligned to the new specifications and prominent industry exhibition activity that signal where R&D resources are concentrated.
Strategic imperatives for entrants and incumbents in 2026
Our research identifies a concise set of actions that materially affect three- to five-year outcomes. Companies that prioritize these moves will be better positioned to protect margin and capture share as the market re-prices and standards evolve.
-
Fast-track standards-aligned formulations. Firms must prioritize GF-7/API-SQ correlated technologies (fuel-economy, LSPI mitigation, piston cleanliness). A “standards-first” product roadmap reduces time-to-approval risk and shortens OEM qualification cycles.
-
Hedge input-cost volatility. Establish multi-sourcing strategies, strategic inventory positioning, and commodity-derivative hedges where feasible. Consider localized blending or toll-manufacturing agreements to reduce exposure to long-haul logistics shocks.
-
Defend and expand OEM channels. Invest in co-development programs and lab-to-vehicle validation capabilities. OEM approvals remain the steepest barrier to market entry; partnership models are often the fastest route across that barrier.
-
Differentiate on service and formulation intelligence. Offer customers not just additive packages but predictive lab data, blend optimization tools, and lifecycle cost modeling that directly tie additive selection to TCO improvements for oil marketers and fleets.
-
Prioritize sustainability and bio-based chemistries. Low-SAPS and bio-derived friction modifiers are moving from niche to procurement checklist — early investment reduces future retrofit costs and supports premium positioning.
-
Evaluate M&A and alliances selectively. With market concentration high, bolt-ons that close technological gaps (e.g., VII, LSPI chemistries) or provide regional manufacturing scale will generate disproportionate value versus greenfield investments.
What PW Consulting’s report delivers — the practical toolkit
This study is structured to be operationally useful for commercial, technical, and corporate-strategy teams preparing 2026 plans. Key deliverables include:
-
Verified market-sizing and scenario models (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity testing against alternative macro and raw-material cost trajectories.
-
Regulatory timelines and a standards-impact matrix mapping GF-7 / API updates to additive-technology requirements and likely OEM adoption curves.
-
Competitive heat maps that identify capability gaps at product, regional, and go-to-market levels — enabling prioritization of R&D and M&A targets.
-
Procurement playbooks addressing short-, medium-, and long-term sourcing tactics in the face of price shocks and supply disruptions.
-
Commercial templates for license negotiations, OEM trials, and oil-marketer conversion programs focused on minimizing cycle time to market.
How to use these insights in 2026
-
CEO / Board: Use the scenario outputs to stress-test earnings guidance and M&A prioritization against alternate raw-material and standards-transition timelines.
-
R&D Heads: Map portfolio roadmaps to the specifications matrix and prioritize chemistries linked to fuel-economy and LSPI outcomes; accelerate bench-to-dyno validation plans where possible.
-
Procurement / Supply Chain: Implement multi-sourcing strategies and define hedging triggers in procurement contracts; prioritize regional redundancy in critical intermediates.
-
Commercial Teams: Recalibrate pricing and value messaging to emphasize lifecycle cost savings, compliance assurance, and application-specific performance for hybrid engine platforms.
Conclusion — an operationally focused preview
For leaders who must make near-term resource-allocation and go-to-market decisions, the 2026 window is less about if change will occur and more about who adapts fastest. Our central forecast anticipates modest yet consistent growth across the seven-year horizon (2026–2032) and highlights how concentrated market structure advantages incumbents that can move quickly on standards, manage input volatility, and offer more than just chemistry — i.e., lab validation, OEM approvals, and commercial execution.
PW Consulting’s full report contains the granular segmentation, supplier matrices, and downloadable models that underpin the strategic guidance summarized here. For confidential briefings, interactive scenario runs tailored to your P&L, or to unlock the full dataset underlying our projections, please refer to the publication page linked from PW Consulting’s Worldwide Automotive Engine Oil Additives Market report announcement.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Packaging Reel Market to Reach USD 2,064.9 Million by 2032 at 5.18% CAGR — Asia Pacific Dominates 2025 Market with USD 682.8M, Top‑5 Hold 52.1%
By pmarketresearch, 2026-07-15
Worldwide Packaging Reel Market — Strategic Preview for 2026 Decision-Makers
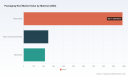
PW Consulting’s latest market study on the Worldwide Packaging Reel market equips corporate leaders with the strategic intelligence they need to make high-consequence decisions in 2026. Built on a five‑year historical base and a seven‑year forecast horizon, the report shows the global market expanding from a 2025 base of USD 1,450 Million to a materially larger opportunity by the end of the forecast window, driven by steady demand and product innovation. The study’s headline compound annual growth rate (CAGR) for the 2026–2032 forecast period is 5.18% — a signal that incumbents and new entrants alike must combine operational rigor with selective investment to capture profitable growth.
Worldwide Packaging Reel Market
What decision-makers should read first
- Macro positioning: The report translates topline market momentum into near‑term strategic choices — where to allocate capex, when to expand production footprints, and how to prioritize sustainability-linked investments.
- Competitive posture: We provide an evidence‑based view of competitive concentration and capability clusters to help procurement, product, and corporate development teams identify defensible plays and potential consolidation targets.
- Regulatory & input risks: The analysis integrates regulatory trajectories and raw‑material volatility scenarios so commercial leaders can stress‑test pricing and sourcing strategies before committing capital.
Why this market matters for 2026 strategy
Packaging reels remain a foundational upstream node in the flexible and industrial packaging value chain, feeding converters, OEMs and contract packers across electronics, medical, food, and consumer segments. The market’s steady expansion and the reported 5.18% CAGR reflect two concurrent dynamics: technology-driven premiumization (high‑barrier, mono‑material, and bio‑resin reels) and regulatory-driven substitution (increasing recyclability and recycled content mandates). For 2026, executives must treat packaging reels not as a commodity line item but as a strategic lever that affects product compliance, brand sustainability claims, and margin retention across downstream portfolios.
Worldwide Packaging Reel Market
Key trends shaping near‑term decisions
- Sustainability engineering: The transition toward recyclable mono‑materials and paper‑hybrid solutions is accelerating. Leading suppliers are rolling out recyclable film constructions and paper‑based reel covers to simplify conversion and end‑of‑life processing; these technologies are moving from demonstration to commercial deployment.
- Material and feedstock dynamics: Raw‑material cycles and resin availability remain a core earnings driver for reel manufacturers. Early 2024 saw downward pressure on certain polyethylene grades in North America, altering raw‑material spreads and creating short windows of procurement advantage. Buyers and hedgers should anticipate episodic price swings and plan inventory strategies accordingly.
- Regulatory tightening: Regional mandates are reshaping acceptable formats and effective cost structures. Across advanced markets, regulations are tightening recyclability and recycled content requirements; at the same time, select jurisdictions have introduced tax regimes and producer obligations that meaningfully shift cost calculus for low‑recycled content films.
- Trade and supply‑chain frictions: Trade measures and tariffs on certain origins continue to redirect flows, adding a layer of geopolitical risk to sourcing decisions. This environment favors multi‑supply portfolios and nearshoring for mission‑critical grades.
- Product innovation and premiumization: Expect sustained demand for barrier, medical‑grade, and high‑printability reels, as brand owners prioritize shelf‑life, safety, and aesthetic differentiation.
Competitive landscape — what the report reveals (and what it withholds)
Our competitive review profiles the primary global and regional players whose product strategies and recent initiatives are reshaping the market. The sector shows moderate concentration: the top three firms collectively account for a meaningful share of revenues, and the top five account for over half of market sales, implying that both scale and specialized capability matter. That concentration pattern presents clear strategic choices: scale through capacity and distribution, or focus on differentiated, higher‑margin niche capability.
Worldwide Packaging Reel Market
Highlights from company observations (summarized):
- Amcor plc leverages broad flexible‑film capabilities and is pivoting toward recyclable mono‑materials — visible through new showcase rollouts at major industry events.
- Berry Global Group applies polymer engineering expertise to develop bio‑resin and performance films tailored for form‑fill‑seal applications.
- Mondi is advancing paper‑based reel covers and hybrid constructions, positioning for customers seeking reduced plastic intensity.
- Huhtamäki and Constantia Flexibles continue to defend premium food and medical segments with high‑barrier co‑extrusions and laminated offerings.
- Regional champions such as Uflex and Cosmo Films are strengthening their export reach with jumbo‑reel capabilities and high‑printability grades, while Winpak and Sealed Air emphasize medical and protein‑focused barrier solutions.
The report includes granular company profiles — technology roadmaps, capacity footprints, and recent go‑to‑market moves — but, in keeping with our “trailer” approach, we intentionally limit the commercial release of certain segment‑level analytics in this preview. Subscribers obtain the full competitive matrix, sourcing maps and supplier scorecards in the complete dataset.
Operational playbook: what to do in 2026
Translate insight into action with a pragmatic three‑track playbook:
- Secure supply while you pivot. Lock short‑to‑medium contracts on strategic film grades during windows of raw‑material softness, while onboarding alternative suppliers for critical reels to mitigate tariff and logistics shocks.
- Invest selectively in sustainability engineering. Pilot mono‑material film formats on high‑visibility SKUs and use conversion cost analysis to quantify the total cost of ownership, including rebates, taxes and end‑of‑life logistics.
- Protect margin via product and commercial segmentation. Differentiate pricing by quality attributes (barrier performance, regulatory compliance, printability) rather than by commodity resin alone; use the report’s pricing and margin archetypes to build tiered commercial offers.
Report contents — practical tools inside
The full PW Consulting report is engineered for deployment by commercial, supply‑chain and corporate development teams. Key deliverables include:
- Topline market model (2020–2032) with scenario toggles for polymer price paths and regulatory shock events;
- Supplier scorecards and capability heat maps to accelerate sourcing and qual processes;
- Regulatory impact matrices crosswalked to reel formats and downstream conversion costs;
- Five validated buyer playbooks (procurement, product development, sustainability, pricing and M&A);
- M&A target shortlist methodology and deal comparators based on capability and regional fit;
- Interactive dashboards for total cost of ownership modeling across material, conversion and end‑of‑life channels.
Risks and scenario sensitivities
Our sensitivity work highlights three risk vectors that require continuous monitoring in 2026: raw‑material volatility, accelerated regulatory mandates (e.g., expanding recyclability and producer obligations), and trade‑policy shifts that can reroute supply flows. Each vector has asymmetric impacts across reel grades and customer segments; the report provides probability‑weighted scenarios and mitigation playbooks tied to procurement and pricing actions.
How PW Consulting helps you act
PW Consulting combines industry‑level data with transaction experience and operational know‑how. For 2026 planning cycles we offer modular engagements: a rapid two‑week supplier due‑diligence sprint, a six‑week commercial transformation program that uses our pricing archetypes, and a full strategic advisory package that includes M&A screening and post‑deal integration templates. Each engagement is grounded in the report’s validated dataset and built to translate insights into measurable outcomes.
Next steps
This release is a strategic preview intended to inform senior planning conversations. For access to the full dataset — including regional and end‑use splits, supplier financials, and the scenario dashboards — visit the PW Consulting report page. The full report contains the granular segmental tables and appendices that operational teams will use to finalize 2026 budgets, sourcing commitments, and R&D roadmaps.
In a market where regulatory timelines compress and material science advances unlock new formats, the opportunity for value creation is clear but conditional: firms that combine disciplined procurement, targeted innovation investment, and a governance process for regulatory change will convert market growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Packaging Reel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Education Computing Devices Market to Expand at a 14.5% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Education Computing Devices Market: Strategic Imperatives for 2026
PW Consulting — Executive Summary of the 2026 Strategic Outlook
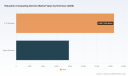
PW Consulting’s latest market study on the Worldwide Education Computing Devices Market (base year 2025, forecast 2026–2032) delivers a pragmatic playbook for executives, procurement leads, product strategists and policy teams planning for the next funding cycle. The global market, which reached roughly USD 22.45 billion in our base year, is projected to grow at a compound annual growth rate (CAGR) of approximately 14.5% through 2032 — reaching the mid-to-high tens of billions by the end of the forecast period. This trajectory is driven by a renewed emphasis on device-standardization in K–12 programs, expansion of connective solutions for underserved students, and rapid incorporation of AI-enabled capabilities at the device level.
Worldwide Education Computing Devices Market
Why this report matters for 2026 decision-making
-
Time-sensitive procurement and budget alignment — District and campus IT budgets that are being set in 2026 must now incorporate multi-year refresh cycles, connectivity allowances, and AI readiness. Our analysis quantifies how different refresh cadences and connectivity choices alter total cost of ownership (TCO) over typical 3–5 year program windows.
Worldwide Education Computing Devices Market -
Supplier selection under consolidation pressures — Market concentration metrics show a meaningful share held by the top vendors, creating both supply-side efficiencies and procurement risks. We map scenarios where an incumbent-led market compresses margins and where agile challengers can disrupt with differentiated services (managed deployments, SEND accessibility, AI toolchains).
Worldwide Education Computing Devices Market -
Regulatory and infrastructure contingency planning — Recent legal and policy moves affecting broadband classification and public-interest exceptions for educational traffic materially change how districts negotiate connectivity and content arrangements. The report provides scenario templates for contract language and capital planning in jurisdictions with divergent regulatory outcomes.
-
Operational playbooks for equitable access — Case studies and deployment lessons (including large-scale connected-device rollouts) reveal practical steps to reduce the digital divide without exposing procurement teams to unsustainable recurring costs.
What’s inside the report — practical, operational content (high level)
-
Forward-looking market sizing and scenario forecasting (2026–2032) with sensitivity testing for device-adoption rates, connectivity models, and policy outcomes.
-
Device-level capability matrices and procurement templates that translate vendor specs into classroom outcomes (durability, battery life, manageability, AI features, accessibility for SEND students).
-
Comprehensive TCO models and rollout phasing guides that combine capital, connectivity, service, and refresh assumptions so buyers can compare program-level economics rather than unit price alone.
-
Vendor scorecards and strategic positioning maps covering product portfolios, channel models, service capabilities and risk exposures — presented to support RFP design and supplier negotiations.
-
Supply-chain and component-risk assessments that translate macro inputs (materials costs, logistics, power/infrastructure commitments) into procurement contingencies.
-
Policy and regulatory playbooks that outline contract clauses, digital equity funding options, and model public-private partnership structures for connectivity and device-as-a-service programs.
Competitive landscape — how leading suppliers are positioning for growth
The market is shaped by a mix of legacy manufacturers, consumer-platform leaders, and cloud-native ecosystem players. Our qualitative competitive analysis highlights where incumbents are defending market share, where partnerships are unlocking access to large-scale programs, and where functional differentiation is creating new tiers of value.
-
HP Inc. — Strengths include education-tailored Chromebooks and laptops with a strong emphasis on durability, battery life and manageability for 1:1 programs. HP’s channel reach and managed service offers make it a first mover in districts seeking turnkey deployments.
-
Dell Technologies — Focuses on serviceability and integration at scale; strong in large public contracts and offers that integrate devices with lifecycle services. Recent large-city deployments exemplify Dell’s ability to synchronize device, cellular connectivity and logistics at municipal scale.
-
Lenovo — Combining competitive hardware economics with newer AI and connectivity features (e.g., next-gen Wi‑Fi) to target classroom resilience and performance. Lenovo’s product refreshes at industry events are geared towards blended learning models and 1:1 durability requirements.
-
Acer & ASUS — Both vendors push aggressive value propositions: Acer with budget-oriented options for large-scale rollouts, ASUS with differentiated features for accessibility (SEND) and ruggedized designs, plus recent launches emphasizing zero-touch enrollment and deployability at scale.
-
Apple & Samsung — Apple’s ecosystem approach (iPads/MacBooks and curricular partnerships) and Samsung’s premium displays/tablet lineup remain important in districts prioritizing content ecosystems and high-fidelity classroom displays respectively.
-
Google — As the steward of ChromeOS and the broader Chromebook ecosystem, Google’s platform plays a central role in educational software management, deployment, and cloud integration — further amplified by AI integrations at the platform layer and a substantial installed base globally.
Notable recent developments underscore the market’s operational dynamics: major product launches at education trade shows introduced devices with Wi‑Fi 7 and enhanced AI features; and large connected-device rollouts in major school systems demonstrate the continued policy push to close the digital divide through device + connectivity programs.
Regulatory and infrastructure signals shaping 2026 choices
-
Broadband policy volatility: Judicial and legislative developments around broadband classification in some jurisdictions increase the likelihood that procurement teams will face a patchwork of state- or district-level rules affecting zero‑rating, prioritized educational traffic, and funding eligibility.
-
Grid and data-center commitments: Recent public-private pledges to underwrite grid upgrades for data centers change operating cost assumptions for cloud‑dependent education services and should be modeled into long-term agreements for hosted learning platforms.
-
Permitted public-interest exceptions: In several markets, public-interest carve-outs for education traffic make zero-rating and prioritized educational content viable tactical levers to increase effective reach — but they also raise equity and competition questions that contracting authorities must address.
Actionable recommendations for leaders in 2026
-
Adopt a two-track procurement strategy: secure a baseline fleet for resilience (durable, manageable devices) while running pilot procurements for AI-enabled, connectivity-rich devices to test pedagogical impact before wide-scale investment.
-
Insist on outcome-based SLAs and bundled service contracts that align vendor incentives with uptime, student engagement metrics and accessibility outcomes — not just unit delivery milestones.
-
Stress-test procurement assumptions against regulatory scenarios (e.g., loss of federal net neutrality protections, state-level zero-rating rules) and build contractual flexibility for connectivity cost shifts.
-
Make energy and infrastructure risk a line item in vendor assessments. With new ratepayer protection initiatives affecting data-center costs, districts should require transparency on cloud hosting energy commitments and the vendor’s exposure to grid upgrades.
-
Leverage vendor competition: use a modular RFP approach that separates hardware, management software, cellular connectivity and pedagogical content to attract specialist bids and reduce single-vendor lock-in.
-
Prioritize accessibility and SEND features in procurement scoring. Recent product launches show vendors increasingly design for diverse learner needs; procurement frameworks must translate those capabilities into measurable classroom benefits.
Signals to monitor through 2026
-
Adoption rates of next‑gen connectivity (Wi‑Fi 7, integrated LTE/5G) in device SKUs and whether districts prioritize integrated cellular vs. separate hotspot programs.
-
Market-share movement among the top vendors and any M&A activity that could materially alter concentration dynamics and procurement leverage.
-
Policy shifts at federal and state levels on broadband classification, zero‑rating permissions, and capital funding availability for digital equity programs.
-
Vendor commitments on AI safety, privacy-by-design for student data, and device-level AI features that shift value from pure hardware to platform-enabled capabilities.
Next steps
If your organization is setting 2026 procurement cycles, negotiating multi-year district agreements, or building a product roadmap to serve educational customers, PW Consulting’s full report provides the detailed breakouts, vendor scorecards, and downloadable TCO models you need to convert strategy into executable plans. The public summary above intentionally highlights the strategic levers and withheld the granular device- and region-level financial tables that are included in the paid report in order to preserve the report’s proprietary value.
To download the full study, access vendor scorecards, and obtain bespoke advisory support for bid evaluation or vendor negotiation, please visit PW Consulting’s report page for the Worldwide Education Computing Devices Market or contact our advisory team for a briefing tailored to your program’s parameters.
— PW Consulting, Senior Strategy & Industry Analysis Team
For detailed analysis of this topic, please visit the official page: Worldwide Education Computing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Semiconductor Magnetic Sensor Market to Hit USD 5,995.97 Million by 2032 at 9.0% CAGR — Asia Pacific (USD 1,468.2M) and Automotive Demand Propel Growth
By pmarketresearch, 2026-07-15
PW Consulting: Worldwide Semiconductor Magnetic Sensor Market — Strategic Briefing for 2026 Decision‑Makers
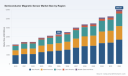
PW Consulting today publishes a strategic briefing based on our new Worldwide Semiconductor Magnetic Sensor Market study. The market reached approximately USD 3,280 Million in 2025 and, under the baseline scenario, is projected to expand to nearly USD 6,000 Million by 2032, representing a compound annual growth rate (CAGR) of about 9.0% across the 2026–2032 forecast window. These headline figures capture a technology inflection point: magnetic sensing is moving from component-level substitution toward system-level differentiation across automotive electrification, industrial automation, and power-electronics applications.
Worldwide Semiconductor Magnetic Sensor Market
Why 2026 Is a Pivotal Year for Strategic Choices
Organizations making product, supply chain, or M&A decisions in 2026 will act into a market that is materially larger and more dynamic than in the first half of the decade. After recovering from a 2020–2025 growth arc that lifted the market from roughly USD 2.15 Billion to USD 3.28 Billion, the industry is entering a phase where sensor performance, materials exposure, and integration with power‑electronics and software stacks determine commercial winners.
Worldwide Semiconductor Magnetic Sensor Market
At the same time, geopolitical and raw‑material developments are reframing risk calculations for 2026 budgeting cycles: export controls, tariffs, and the concentration of heavy‑rare‑earth refining change the cost and availability calculus for magnet-dependent sensor systems. Our report translates these macro trends into decision-ready options for product managers, procurement chiefs, and corporate strategists.
Worldwide Semiconductor Magnetic Sensor Market
What the Report Delivers: Practical, Executable Intelligence
- Integrated market model and scenarios: A calibrated demand model spanning 2020–2032 (base year 2025) with three-tier scenarios that isolate technology adoption curves, regulatory shocks, and supply‑side disruptions.
- Go‑to‑market playbooks: Category‑specific launches and commercial tactics that align product architectures to lead markets (automotive, industrial, power‑electronics, consumer and healthcare), including channel and pricing guidance.
- Technology & product roadmap assessments: Comparative appraisal of Hall, magnetoresistive families (TMR/AMR/GMR), and hybrid sensor-system approaches with technology readiness, cost trajectories, and performance envelopes.
- Supply‑chain risk and mitigation matrix: Material exposure mapping, dual‑sourcing options, foundry and packaging dependencies, and a practical checklist for near‑term inventory and qualification actions.
- Competitive playbook & M&A screen: Profiles of incumbent and emerging players, concentration metrics, capability gaps, bolt‑on targets, and partnership archetypes designed to accelerate route to market.
- Commercial metrics and BOM sensitivity analyses: Elasticity testing for price, margin, and cost-to-serve under alternative tariff and raw‑material scenarios — designed for CFO and product‑line owners.
- Primary research and validation: Supplier interviews, design‑win data, foundry capacity assessments, and customer demand signals that underpin the forecasts.
This is an operational report: each chapter closes with recommended next steps tailored by persona (CEOs, CTOs, procurement VPs, and corporate development teams), enabling rapid translation of insight into 90‑ to 180‑day action plans.
Competitive Landscape: Who Moves Markets in 2026
The semiconductor magnetic sensor market exhibits a moderate concentration: the top three firms collectively account for a majority share, and the top five approach a substantial control point of close to seven‑tenths of market revenue. That structure yields both stability and strategic friction — incumbents defend design wins through differentiated IP, while mid‑tier and specialty players exploit niche technologies and foundry partnerships to open new use cases.
- Allegro MicroSystems, Inc. — A leader in high‑performance Hall and TMR current-sensing, Allegro has accelerated its roadmap with acquisitions and launched high-bandwidth TMR solutions aimed at wide‑bandgap power electronics. These moves position Allegro to capture system‑level opportunities in EV traction and high‑speed converters.
- Infineon Technologies AG — With a broad XENSIV portfolio spanning Hall, AMR, GMR and TMR, Infineon is privileging system integration and automotive qualification. Its ongoing launches reinforce a strategy to bundle sensing with power and driver ICs for differentiated ADAS and motor-control solutions.
- NXP Semiconductors — Focused on automotive-grade magnetoresistive and ultra‑low‑power Hall solutions, NXP targets speed, angle, and position sensing where functional safety and energy efficiency are critical.
- Asahi Kasei Microdevices (AKM) & TDK Corporation — Both bring sensor material and device expertise; AKM’s tri‑axis offerings and TDK’s TMR angle sensors target compact, safety‑critical automotive applications.
- Melexis, STMicroelectronics, Honeywell, Texas Instruments, ABLIC — These firms combine strong automotive/industrial footprints with differentiated device portfolios: integrated 3D position sensors, ultra‑low‑power 3‑axis devices, aerospace/industrial systems, and mass‑market Hall switches respectively.
- Tower Semiconductor — As a foundry partner, Tower’s capability to integrate magnetoresistive sensors with specialty processes (including high‑temperature and GaN environments) presents an important risk‑mitigation and innovation pathway for OEMs seeking performance at scale.
Recent product activity through late 2025 underscores a fast‑moving competitive environment: new industrial reference designs and ultra‑low‑power 3‑axis modules, compact TMR angle sensors for safety applications, and high‑bandwidth TMR current sensors aimed at next‑generation power architectures. These launches are emblematic of a broader shift from commodity sensing to differentiated system capabilities.
Supply Chain & Geopolitics: Practical Implications for 2026 Planning
Material and regulatory dynamics are no longer peripheral risks; they are core drivers of sourcing and design strategy. Key developments that factor into 2026 decision‑making include export controls and licensing regimes that affect magnet and semiconductor material flows, concentrated refining capacity for heavy rare earths, and tariff regimes that change landed cost for finished assemblies. Additionally, shifts in related commodity pricing (for example, notable declines in battery pack costs in 2024) alter total system economics and shape OEM procurement priorities.
For executive teams, the tactical consequences are straightforward: (1) accelerate qualification of alternative magnet suppliers and magnet‑less architectures; (2) expand the universe of foundry and packaging partners capable of delivering mission‑grade performance; (3) bake regulatory and tariff scenarios into NPV and price elasticity models; and (4) reweight inventory policies for critical inputs where lead times and single‑source exposures remain high.
Strategic Playbook — Five Actions for 2026
- Stress‑test product roadmaps: Model three shock scenarios (moderate supply disruption, material price shock, and export restriction) and quantify impact on time‑to‑market and margin for each active program.
- Prioritize architecture bets: Decide where to allocate R&D spend between high‑end TMR/GMR, robust Hall solutions, and software‑defined sensor fusion that reduces magnet dependency.
- Secure multi‑vector supply: Combine dual‑sourcing for magnets with foundry diversification and pre‑qualified packaging options to remove single points of failure.
- Differentiate at system level: Invest in calibration, diagnostics, and domain‑specific software to turn sensing into a durable competitive advantage rather than a commodity component.
- Use M&A and partnerships tactically: Target capabilities that close gaps in materials, TMR IP, or high‑temperature process integration; structure deals to accelerate design‑win cycles and de‑risk supply exposure.
PW Consulting’s Report: How It Supports 2026 Decisions
Our report translates the market’s growth trajectory and risk environment into discrete, actionable programs. It combines an auditable market model (2020–2032), supplier benchmarking, product and BOM sensitivity tools, and a short‑list of strategic options keyed to three different corporate archetypes: scale incumbents, fast‑growing challengers, and design‑focused specialists. We deliberately publish a high‑level briefing here to surface the strategic direction; the full report contains the granular scenario outputs, segment level forecasts, and supplier scorecards required to execute those actions.
For executives assembling 2026 budgets, negotiating supplier contracts, or prioritizing R&D investments, the study provides both the evidence base and the practical steps necessary to convert market potential into sustainable revenue. If your team needs a customized briefing — for example, a focused scenario that quantifies exposure to a specific material constraint or a bespoke acquisition screen — PW Consulting can deliver a tailored engagement based on the underlying dataset and modeling framework.
To access the full intelligence package, including the segment‑level forecasts and supplier scorecards withheld in this briefing, please consult the PW Consulting Worldwide Semiconductor Magnetic Sensor Market report page or contact our industry practice. The full report contains the detailed breakdowns and executable templates that decision‑makers will need to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oat-based Cereal Market Poised to Grow at a 5.34% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Oat-based Cereal Market: Strategic Preview for 2026—What Senior Executives Need to Know
PW Consulting’s latest market study on the Worldwide Oat-based Cereal Market offers a forward-looking playbook for boards, strategy teams, and functional leaders preparing decisions in 2026. The market has demonstrated resilience and expansion through the early 2020s, rising from the low‑double-digit billions in 2020 to a projected global market size of roughly USD 14.25 billion in 2025. Our model forecasts continued momentum into the next planning cycle, with the sector approaching the low‑twenty billions by the end of the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 5.34% for that period. These headline dynamics create distinct opportunity windows—and real operational risks—that demand immediate action from manufacturers, retailers, ingredient suppliers, and investors.
Worldwide Oat-based Cereal Market
Why this report matters to 2026 decision-making
-
Precision for prioritization: The report translates macro growth into practical decision frames—helping executives prioritize R&D, route-to-market investments, and capital allocation across core programs without relying on intuition alone.
Worldwide Oat-based Cereal Market -
Timing of bets: Our forecast identifies when demand inflection points will create premiumization, value-tier expansion, or channel displacement pressures—critical for timing product launches and promotional spend in 2026.
Worldwide Oat-based Cereal Market -
Risk triage: By quantifying concentration in the competitive landscape and mapping systemic supply risks, the study supports scenario planning for recalls, raw-material volatility, and regulatory shifts.
-
Commercial playbooks: The report couples growth forecasts with go-to-market templates and retailer negotiation levers—designed for commercial teams to convert category momentum into share and margin gains.
Market snapshot and structural dynamics
Oat-based cereals have moved from a differentiated health niche to mainstream staple in many markets, driven by nutrition positioning (notably beta‑glucan and heart-health narratives), clean-label trends, and product innovation across formats. Our historical analysis shows steady expansion between 2020 and 2025, with an acceleration in premium and ready-to-eat segments. Looking ahead, a mid-single-digit CAGR of 5.34% over 2026–2032 implies a market that is large enough to justify scale investments yet fragmented enough to reward targeted differentiation and agile execution.
Concentration metrics in the report indicate a moderate level of market concentration: the top three players command over 40% of the market, while the top five approach the mid‑50s (percent). This structure favors incumbent brands with deep retail relationships and scale manufacturing—but also provides room for challenger brands, private label expansion, and regional specialists to carve out meaningful niches.
Supply-side and regulatory context impacting 2026 planning
-
Raw-material volatility: Oat prices have shown upward pressure, with U.S. average prices moving higher in 2023 due to acreage reductions. Procurement and operations teams must incorporate forward hedging, long-term contracting, and cultivar diversification into 2026 sourcing strategies to protect margins.
-
Labeling and health claims: Regulatory regimes continue to tilt in favor of evidence-based health messaging. The FDA’s labeling updates, which emphasize functional claims such as beta‑glucan’s contribution to heart health, and existing EU rules that set minimum thresholds for oat beta‑glucan claims, create both marketing advantages and compliance obligations. Product teams should align formulations to meet claim thresholds while preparing substantiation dossiers for new markets.
-
Food safety vigilance: High‑profile recalls in recent years have heightened buyer sensitivity and retailer audit intensity. Traceability, supplier qualification, and end-to-end quality assurance will be board-level priorities in 2026.
Competitive landscape: capabilities and gaps
Our report includes in-depth profiles of leading multinational and specialty players. Below is a synthesized strategic read of core incumbents and what their moves imply.
-
General Mills (Minneapolis, MN) — Leverages a globally recognized cereal franchise to extend oat-based innovations. Brand depth and SKU density create cross-sell opportunities, but scale portfolios must be balanced with agility to capture premium niche trends.
-
PepsiCo / Quaker Oats (Purchase, NY) — A historic oat player in ready-to-eat formats; its scale in ingredients, distribution, and co‑manufacturing remains a competitive moat. However, recent product-safety events have elevated reputational and operational risk, making investments in supply-chain transparency and rapid recall management non-negotiable.
-
WK Kellogg Co (Battle Creek, MI) — Strong in co‑branded and differentiated product forms. Kellogg’s challenge and opportunity are converting cereal heritage into oat-forward narratives that resonate with younger or health-first consumers.
-
Post Holdings (Brentwood, MO) — Competes through niche positioning and fiber-led messaging. Post’s playbook is instructive for companies aiming to scale high-fiber variants without ceding price competitiveness.
-
Specialist and regional players (Nature’s Path, Bob’s Red Mill, Weetabix, Nestlé, Hero Group) — These firms illustrate three viable routes to growth: organic/clean-label premiumization, artisanal and whole‑grain authenticity, and fortified/functional innovation. Their success underscores the importance of differentiated sourcing, small-batch innovation pipelines, and selective channel partnerships.
Recent developments that should shape 2026 plans
-
Product-safety events: Extended recalls tied to certain oat-based SKUs in late 2023–2024 have raised retailer and consumer expectations for traceability and rapid response systems.
-
New product introductions: Incumbents continue to invest in flavor and format innovation—demonstrating that incremental SKU refreshes remain a fast route to incremental sales if supported by trade presence.
-
Trade and demonstration activity: The visible presence of organic and high‑margin oat launches at industry shows signals that retailers will keep allocating shelf space to emerging oat propositions.
What the report contains (practical, decision‑ready modules)
-
Executive synthesis and 2026 action checklist—aligned to board timelines and annual planning cycles.
-
Market-size modeling and scenario forecasts—baseline, upside, and downside projections with sensitivity to raw-material and regulatory shocks.
-
Go-to-market playbooks—SKU rationalization, pricing ladders, pack-size optimization, and retailer negotiation templates tailored for different route-to-market strategies.
-
Supply-chain resilience toolkit—supplier scorecards, traceability requirements, and contingency playbooks for rapid recall events.
-
Competitive intelligence—detailed company profiles, innovation pipelines, M&A activity map, and benchmarking against best-practice KPIs.
-
Retail and channel strategy—omnichannel tactics and conversion levers for supermarkets, e‑commerce, and on‑the-go channels.
-
Regulatory and claims compendium—practical thresholds, labeling dos and don’ts, and dossier templates for health claim substantiation.
Actionable recommendations for 2026
-
Prioritize traceability and QA investments now—install batch-level traceability and rapid recall protocols as capital priorities to protect brand equity and avoid costly supply disruptions.
-
Design claim-compliant formulations—ensure new product concepts meet regulatory thresholds for beta‑glucan and other function-related claims before launch to avoid rework and market delays.
-
Hedge and diversify oat supply—combine forward contracts, geographic diversification, and varietal sourcing to limit commodity cost exposure.
-
Segment product tiers with clear margin strategies—reserve premium innovation budgets for formats and channels that can bear higher ASPs, while using targeted value SKUs to defend share in price-sensitive segments.
-
Invest in omnichannel conversion—use SKU and pack-size analytics to optimize the mix for digital shoppers versus brick-and-mortar buyers, and deploy subscription models where viable.
-
Explore selective M&A and JV opportunities—acquire capabilities in clean-label processing, organic certification, or regional distribution to accelerate entry into high-growth niches without diluting core brands.
-
Elevate sustainability narratives—with measurable claims (e.g., regenerative oats, reduced water footprint) that are auditable and resonate with retail sustainability scorecards.
Frequently asked strategic questions (preview)
-
How material is commodity risk to margin in 2026? Answer: Material enough to require proactive procurement hedging and contract strategies—our scenario work shows margin erosion under sustained price spikes without mitigation.
-
Should companies prioritize scale or premium niche in 2026? Answer: Both paths are viable. The right choice depends on your cost base, brand equity, and route-to-market advantages; the report provides a decision matrix to determine optimal focus.
-
What immediate steps should retailers take? Answer: Improve supplier auditing and SKU rationalization to reduce recall exposure and improve shelf productivity; our retailer playbook includes negotiation levers tied to safety and sustainability KPIs.
PW Consulting’s report is deliberately structured as a decision support system: it surfaces the hypotheses, validates them with granular modeling, and delivers playbooks and templates that management teams can operationalize during 2026 planning cycles. To preserve the strategic value of the dataset and support your planning workshops, we have intentionally omitted granular public exposure of core segment split data in this preview—those detailed tables, SKU-level analytics, and regional routing matrices are available in the full report.
For boards, strategy teams, and investor groups preparing 2026 plans, the full report is the single most efficient means to convert the macro tailwinds and tactical warnings summarized here into executable initiatives. Visit our official publication page to download the comprehensive study, access interactive dashboards, and schedule a briefing with PW Consulting’s senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Oat-based Cereal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Used Cooking Oil for Sustainable Aviation Fuel Market to Skyrocket from USD 2,865.4 Million in 2025 to USD 10,448.7 Million by 2032 at a 20.31% CAGR
By pmarketresearch, 2026-07-15
Used Cooking Oil for Sustainable Aviation Fuel: PW Consulting Strategic Briefing for 2026 Decision-Makers
Executive snapshot
The global market for used cooking oil (UCO) as a feedstock for sustainable aviation fuel (SAF) is shifting from opportunistic aggregation to strategic industrialisation. PW Consulting’s latest market study shows the UCO-for-SAF market growing from roughly USD 2.87 billion in 2025 to an expected USD 3.49 billion in 2026, and continuing on to an estimated USD 10.45 billion by 2032 — an implied compound annual growth rate of 20.31% for the forecast horizon. For executives making 2026 capital, procurement and partnership decisions, the window to secure resilient feedstock chains and value-capture routes is narrow but actionable. This briefing outlines the report’s strategic value, the drivers reshaping the market, competitive dynamics to watch, and the practical tools included in our full deliverable that boardrooms will need as SAF policy and commercial realities converge.
Used Cooking Oil for Sustainable Aviation Fuel Market
Why 2026 is a strategic inflection point
-
Policy front-loading: Aviation-specific mandates and national SAF programmes that became effective in 2025 are now binding commercial decisions in 2026. Early compliance pathways such as HEFA using UCO are the dominant near‑term route for many markets; evolving quota timetables materially change demand profiles for certified waste feedstocks.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Incentives and localisation: Regional incentive structures — notably production tax credits in North America with feedstock eligibility conditions — create asymmetries in feedstock economics and sourcing priorities. These rules are decisive when choosing between local aggregation, imports and co-processing strategies.
Used Cooking Oil for Sustainable Aviation Fuel Market -
Supply squeeze and price volatility: Increasing demand for both SAF and biodiesel has elevated UCO market tightness. Market participants are already experiencing significant price swings and episodic supply tightness, forcing procurement teams to decide between short-term spot purchases and longer-term offtake or vertical integration.
Market dynamics that will shape corporate plays in 2026
Our analysis highlights four interacting dynamics that should guide every 2026 strategic plan:
-
Demand certainty from regulatory mandates: Regional SAF blending mandates have moved the sector from speculative demand to structural offtake. Early-compliant feedstocks (notably UCO for HEFA pathways) are the default supply pool in many jurisdictions while alternative pathways scale.
-
Policy-driven regional arbitrage: Incentives that tie credits or subsidies to domestically sourced feedstock create trade flows that can rapidly realign procurement maps. Corporates must model both tariff and subsidy regimes simultaneously when sizing assets or negotiating supply.
-
Aggregation economics: Collecting UCO at scale requires dense logistics networks, contamination management and traceability systems. Scale and trusted collection partners materially lower delivered feedstock cost and quality risk.
-
Price and feedstock transparency: Volatility in bulk UCO prices has become a tactical variable for operations and contracting teams. Hedging tools, indexed contracts and blended feedstock strategies reduce short-term margin erosion but require robust data inputs.
Competitive landscape: positioning and strategic moves
The UCO-to-SAF ecosystem is already populated by a mixture of global refiners, specialised collectors, vertically integrated biofuel producers and national oil companies. Market concentration indicators in our study show a moderately consolidated structure: the top three firms account for around 38.4% of market supply by volume, while the top five approach approximately 52.2% — leaving meaningful room for strategic partnerships and consolidation targeted at the mid‑market.
Key strategic archetypes and representative players include:
-
Global integrated renewables leaders (scale + conversion capability): Companies with refinery footprints, proprietary HEFA capacity and aggregation networks are pursuing a full-value-chain play. Their advantage is end-to-end control of quality, certification and logistics, which shortens time-to-market for SAF sales and secures higher margin capture.
-
Collectors and logistics specialists: Firms focused on UCO aggregation, preprocessing and certification are increasingly critical partners for refiners and airlines. Their strategic options include exclusive long-term supply contracts, regional consolidation and investments in preprocessing to improve feedstock yields.
-
National oil companies and integrated refiners: State-backed and major refiners are deploying co-processing and dedicated HEFA units to secure domestic SAF supply. Their balance-sheet strength and fuel distribution networks accelerate market placement but require feedstock assurances that collectors must provide.
-
Emerging tech and regional converters: Smaller players and technology licensors are moving to prove scaleable, cost-competitive routes for converting UCO and other wastes. Their strategic value lies in niche capabilities and potential licence or JV upside with larger offtakers.
Recent market actions we highlight as case studies: long-term supply arrangements that lock volumes; first commercial shipments by refiners transitioning to SAF delivery; and plant ramp-ups returning capacity to market. These moves exemplify the strategic choices facing buyers and investors: secure contracted volumes at premium, invest in aggregation capability, or pursue co-processing to diversify feedstock options.
Strategic implications and recommended 2026 actions
-
Prioritise feedstock security over lowest-price procurement: Given mandate-driven demand and episodic price spikes, procurement strategies that prioritise multi-year, indexed offtakes and exclusive collection partnerships reduce supply risk and support financing of conversion assets.
-
Design contracts for policy and market volatility: Include clauses for subsidy reallocation, tariff shifts and feedstock eligibility changes. Where relevant, reserve capacity for domestic feedstock to retain incentive eligibility.
-
Invest in traceability and pre-processing: Quality variability is a persistent source of conversion inefficiency. Investment in preprocessing hubs, sampling protocols and digital traceability improves yield predictability and simplifies certification compliance.
-
Evaluate consolidation and partnership targets actively: The mid-market remains fragmented; acquisitive players can rapidly scale aggregation capabilities by targeting regional collectors and logistics specialists with strong local relationships.
-
Scenario-test conversion routes: Compare HEFA versus co-processing economics under differing feedstock availability, credit regimes and carbon prices. Align capital deployment with the route that best matches offtake structure and policy risk tolerance.
What PW Consulting’s report delivers to support 2026 decisions
Our full PW Consulting report is built as a practical decision-support suite for executives and investment committees. Deliverables include:
-
Proprietary market sizing and forecast model with downloadable worksheets — enabling custom scenario runs for prices, mandates and feedstock mixes across the 2026–2032 horizon.
-
Supply-chain maps and collection-density analytics — visualised catchment areas for aggregation hubs, estimated collection costs under differing contamination profiles, and logistics optimisation levers.
-
Contracting and procurement playbook — clause libraries for offtake, quality warranties, force majeure and indexation mechanisms adapted for UCO markets and incentive regimes.
-
Investment and M&A playbook — valuation templates, due-diligence checklists for feedstock assets, and integration roadmaps for collectors and converters.
-
Policy and incentive modelling toolkit — sensitivity analyses showing how mandate trajectories and tax-credit rules alter project IRRs and required offtake terms.
-
Competitive intelligence dossiers — strategic profiles of major collectors, refiners and converters, recent deal activity and a CR3/CR5 concentration dashboard to support strategic positioning.
-
Primary-data appendices: a curated dataset of supply agreements, recent commercial shipments and a vetted list of collection specialists and technology providers — maintained behind the report gateway.
To preserve the strategic value of the dataset and to respect commercial confidentiality in competitive segments, detailed regional and application-level splits and certain contract-level metrics are provided exclusively in the full report and interactive workbooks.
Closing guidance for boardrooms and investors
For corporate strategists, the next 12–18 months are a race for credible, contractually-secured feedstock and for conversion capacity alignment with offtake channels. For investors, the uneven regional incentive landscape and still-fragmented aggregation market create differentiated opportunities for roll-up strategies, strategic partnerships with refiners, and early-stage technology bets. PW Consulting’s analysis shows that participants who align procurement, policy hedging and vertically integrated economics early will be best placed to capture disproportionate value as SAF volumes transition from niche compliance to a structural fuel market.
How to access the full intelligence
This briefing is a strategic preview. Our comprehensive report contains the full datasets, model templates and supplier-level dossiers referenced above. For subscription access, bespoke briefings tailored to a company’s asset or procurement footprint, or to schedule a workshop on how to operationalise these insights in 2026, please visit PW Consulting’s report page or contact our advisory team.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Clover Leaf Oil Market to Hit USD 398.02 Million by 2032, Expanding at a 4.88% CAGR with Asia‑Pacific Leading at USD 111.62M
By pmarketresearch, 2026-07-15
Worldwide Clover Leaf Oil Market — Strategic Outlook for 2026: Operational Intelligence for Decision-Makers
Executive summary
PW Consulting’s latest market intelligence brief, "Worldwide Clover Leaf Oil Market," equips senior leaders with the directional clarity and executable insights required to shape strategy in 2026. Built on an empirical foundation spanning 2020–2025 and a firm projection through 2032, the study synthesizes market trajectories, competitive dynamics, supply-chain risk, regulatory trends, and commercial playbooks into a single decision-ready asset.
Worldwide Clover Leaf Oil Market
At the macro level, the clove leaf oil market reached a base-year size of USD 285.12 Million (2025) and is projected to expand at a compound annual growth rate (CAGR) of 4.88% over the 2026–2032 forecast window. PW Consulting’s modeled range positions the market at roughly USD 309.6 Million in 2026, rising toward approximately USD 398.0 Million by 2032. These headline metrics anchor the strategic imperatives that follow: this is a market large enough to justify targeted investment, but compact and concentrated enough that focused moves — in procurement, product innovation, and M&A — can materially reshape competitive positioning.
Worldwide Clover Leaf Oil Market
Why this report matters for 2026 decision cycles
- Timing: 2026 is a pivot year for buyers and producers as post-pandemic demand normalization converges with new regulatory and consumer-driven requirements for botanical extracts.
- Risk vs. Opportunity: Our scenario modeling shows that modest shifts in supply conditions or regulatory constraints can amplify price volatility and create short windows of strategic advantage. Firms that pre-emptively secure validated supply, diversify sourcing, or hedge exposure are likely to capture disproportionate margin upside.
- Actionability: The report converts macro projections into concrete commercial actions — from SKU rationalization and formulation swaps to supply agreements and targeted M&A screening criteria — enabling 90–120 day tactical plans and 3–5 year strategic roadmaps.
Market trajectory and the near-term outlook
PW Consulting’s time series analysis (2020–2025) reveals a market that has recovered unevenly from recent global disruptions, with underlying demand drivers (pharmaceuticals/dental, personal care & fragrances, food flavoring, and agricultural applications) diversifying the revenue base. Using a base year of 2025, the market exhibits a steady compound growth profile — a 4.88% CAGR across our 2026–2032 forecast — translating into mid-single-digit annual increments that are sufficient to support new capacity investments but sensitive to short-term supply shocks.
Worldwide Clover Leaf Oil Market
For 2026, our point forecast anticipates a continuation of moderate expansion to roughly USD 309.6 Million, reflecting a mix of demand recovery in legacy applications and incremental adoption in adjacent uses (for example, botanical-based actives and natural pest-control formulations). From a planning perspective, this trajectory signals that 2026 is a year for selective expansion rather than broad-scale capital outlays unless coupled with verified supply contracts or technology advantages that lower per-unit costs.
Competitive landscape — concentration, incumbents and disruption pathways
The clove leaf oil market demonstrates a moderate level of concentration: the top three suppliers account for just over forty percent of market share, while the top five account for roughly mid-fifties. This structure produces a market dynamic where leading incumbents exert price and quality leadership, yet meaningful share remains accessible through specialization, service differentiation, and verified traceability.
- Incumbent advantages: Scale players retain advantages in sourcing relationships, integrated processing, and certification capabilities — all significant barriers for new entrants seeking to supply regulated industries (pharma, food).
- Opportunities for challengers: Focused entrants that can demonstrate sustainability credentials, transparent traceability, or tailored technical services (customized grades, stabilized formulations) can capture adjacent share from larger players, particularly in premium segments.
- Disruption vectors: Contract farming partnerships, retrofitted distillation technologies that increase eugenol yield, and blockchain-enabled traceability are three practical disruption pathways that can confer defensible differentiation at relatively modest incremental investment.
Structural supply risks and regulatory context
Supply is inherently agricultural and therefore exposed to climatic variability, crop disease, and labor availability. In addition, regulatory scrutiny toward botanical extracts — spanning fragrance safety (IFRA-like guidance), food additive approvals, and pesticide registrations for agricultural applications — elevates compliance costs and elongates time-to-market for new formulations.
For 2026, decision-makers must consider an integrated risk framework that links agronomic variables (crop yields, planting cycles) with regulatory timelines and supply-chain logistics (shipping lead times, inspection regimes). The report provides scenario-based stress tests that quantify how defined disruptions could affect available volumes, procurement pricing, and margin sensitivities across commercial models.
Actionable content: what the report delivers to help you act in 2026
This release is structured to move beyond high-level forecasting. The study is organized into modular, practitioner-oriented deliverables designed for quick integration into procurement, R&D, commercial strategy, and corporate development workstreams. Highlights include:
- Demand and supply models with adjustable levers for price, yield, and demand elasticity — enabling rapid re-calibration under alternative assumptions.
- Price scenario analysis and break-even maps that show how input cost shifts propagate through to final-product margins across common formulations.
- Supplier due-diligence templates and a capability scoring model for evaluating third-party processors and farm partnerships.
- Regulatory-impact matrices and compliance timelines tailored to fragrance, food, and agricultural use-cases.
- A prioritized list of near-term (0–12 months) and medium-term (1–3 years) initiatives — from low-cost traceability pilots to acquisition screening criteria — that senior teams can operationalize immediately.
Strategic plays for 2026
Based on quantitative modeling and qualitative interviews, PW Consulting recommends that market participants consider a portfolio of plays calibrated to their role in the value chain:
- Buyers/brands: Lock in multi-year supply with quality-verified partners; develop dual-sourcing strategies; accelerate reformulation trials to reduce dependency on the highest-cost grades where possible.
- Processors/distributors: Invest selectively in yield-improving distillation upgrades and batch-level traceability; target premium segments with certified origin claims to capture margin expansion.
- Investors/M&A teams: Screen for targets that add farm-to-bottle traceability, proprietary processing methods, or market access in under-served application channels; prioritize deals where synergies compress compliance costs or accelerate new-product launches.
- R&D leaders: Prioritize product claims aligned with consumer clean-label trends and expand applications into agrochemical niches where natural pesticides command a premium and face lower reformulation barriers.
Report methodology and product scope
The study uses a transparent, reproducible methodology: historical analysis for 2020–2025; a 2025 base year; and forecast modeling for 2026–2032. Valuation and revenue figures are expressed in USD (Million). The market is segmented by region, product grade, and application to provide layered insight — from aggregated market sizing to targeted commercial playbooks. In line with our client-first approach, the summary published here intentionally omits detailed subsegment values; the full report contains the granular tables, regional splits, product-grade breakdowns, and application-level demand curves required to run internal scenario planning and financial modeling.
Who should read this report
Primary audiences include C-suite executives in ingredient supply, procurement heads, corporate development teams, product innovators, and sustainability leads. Secondary beneficiaries include private equity investors, commodity traders, and regulatory affairs teams looking to quantify exposure and identify opportunities in botanical extract markets.
Next steps and how to engage
PW Consulting has structured access to the full report and associated toolkits to support rapid operationalization:
- Full dataset and interactive models (available upon report purchase) for direct scenario simulations and exportable inputs for internal financial models.
- Custom briefing sessions and workshop packages to translate findings into a 90–120 day implementation plan tailored to your portfolio.
- Optional supplier diligence and acquisition screening support from our strategic transactions team.
In an industry where botanical provenance, compliance, and minor process improvements can yield outsized commercial returns, clarity of information becomes a competitive advantage. PW Consulting’s "Worldwide Clover Leaf Oil Market" report provides that clarity — delivering a concise, actionable picture of market-scale opportunity, measured risk, and pragmatic strategies to win in 2026 and beyond. For full subsegment tables, supplier assessments, and the interactive forecast workbook, please visit the official report page to access the complete research package.
For detailed analysis of this topic, please visit the official page: Worldwide Clover Leaf Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tissue Sectioning Market Set to Expand at a 6.42% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Tissue Sectioning Market — 2026 Strategic Outlook and Executive Preview
PW Consulting’s latest industry study on the Worldwide Tissue Sectioning Market provides a decision-grade intelligence package for executives planning capital allocation, product roadmaps, supply-chain moves, or M&A activity in 2026 and beyond. This executive preview synthesizes the report’s most consequential implications — combining recent market dynamics, competitive posture shifts, regulatory noise, and practical decision tools — to help senior leaders convert market signals into prioritized initiatives. Detailed segment tables and the full financial model remain available exclusively in the report.
Worldwide Tissue Sectioning Market
Executive summary: what the numbers mean for strategy
By our accounting (base year 2025), the worldwide tissue sectioning market reached USD 845.5 Million (Revenue Unit: Million, USD). After a steady recovery and expansion between 2020 and 2025, the market is forecast to grow through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.42%, reaching approximately USD 1,305 Million by 2032 under the baseline scenario. Market concentration is material: the top three players control a clear majority of industry revenues (CR3 ~58.4%), while the top five collectively account for roughly 72.1% of the market.
Worldwide Tissue Sectioning Market
These headline metrics are not an end in themselves. For leaders making 2026 choices, the key takeaways are directional: (1) a predictable mid-single-digit growth runway enables multi-year capital recovery models for instrument upgrades; (2) concentration favors platform incumbency strategies — scale, interoperability, and after-sales services remain potent competitive moats; and (3) structural decoupling between devices and assays (driven by digital pathology and multiomics workflows) is reshaping supplier bargaining power and product roadmaps.
Worldwide Tissue Sectioning Market
Why this matters to corporate decision-makers in 2026
- Capital allocation: With measured but persistent growth, organizations can justify targeted investments in automation and digital integration instead of broad fleet replacement. Prioritize investments with clear unit-economics and service-capture potential.
- Product strategy: Differentiation is migrating from mechanical precision alone to system-level interoperability (scanner, LIS, AI) and consumables economics. Roadmaps that integrate tissue sectioning hardware with downstream digital workflows will command premium positioning.
- M&A and partnerships: High market concentration creates attractive roll-up opportunities among niche equipment and consumables specialists. Strategic partnerships with digital pathology firms accelerate value capture and shorten adoption cycles.
- Regulatory and risk: FDA classifications and episodic recalls can abruptly reset procurement priorities. A disciplined regulatory playbook reduces business interruption risk and enhances buyer confidence.
What the PW Consulting report delivers (practical content)
The report goes well beyond descriptive narrative. It is structured as an operator’s playbook that includes:
- Proprietary market model (2020–2032) with scenario toggles for adoption, pricing, and reimbursement levers — exportable Excel files enable bespoke sensitivity analysis.
- Actionable segmentation framework and go-to-market archetypes for device OEMs, consumables suppliers, laboratory chains, and pathology service providers (note: granular segment figures are available in the full report).
- Competitive scorecards and capability maps that evaluate product portfolio breadth, digital integration, aftermarket/service strength, and regulatory posture for leading vendors.
- Supply-chain risk matrix and raw-material guidance highlighting single-source exposures and recommended mitigation levers.
- Tactical playbooks: procurement negotiation templates, three-year service-contract models, and a prioritized M&A diligence checklist tailored to tissue sectioning targets.
Competitive landscape — strengths, moves, and implications
The market is composed of well-established multinational platforms and a group of specialist regional players. Incumbent OEMs have competing imperatives: defend installed base economics while moving up the value chain into automation and digital interoperability. Recent industry moves illuminate these dynamics.
- Platform incumbents continue to leverage broad portfolios — from manual rotary microtomes to fully automated tissue sectioning lines — to cross-sell instruments, consumables, and service.
- Strategic partnerships are accelerating digital integration. A notable example is a 2025 strategic alliance between a leading histology equipment supplier and a digital pathology software firm to co-develop scanner-AI integrations that streamline the tissue-to-diagnosis workflow.
- End-user demand is being reshaped by diagnostic assay innovation. The market has seen product launches that materially reduce slide requirements for multiomics panels, prompting procurement to prioritize sectioning efficiency and sample conservation.
- Smaller specialized manufacturers sustain relevance by focusing on niche performance advantages (e.g., ultramicrotomy for electron microscopy, high-precision cryostats) and by serving geographies or customer segments underpenetrated by global OEMs.
For executives evaluating partners or targets, the report’s vendor scorecards distill comparative strengths across instrument precision, automation options, digital APIs, consumable economics, installed-base demographics, and service revenue margins.
Regulatory context and operational risk
Regulation is a persistent influence on procurement cycles and supplier selection. Devices in this category are classified under established FDA product codes for tissue processing equipment, which affects premarket expectations and post-market surveillance. Notably, recalls — even when limited in scope — can trigger expedited replacement cycles and spike demand for validated alternative systems. Supply-side strategy must therefore couple product development with disciplined post-market surveillance and recall-ready service capabilities.
On the materials side, blade metallurgy and consumables quality directly affect clinical performance and total cost of ownership. Technical guidance around specialty steels for blades underscores the link between upstream raw materials and downstream diagnostic accuracy — an area often undervalued in procurement decisions.
Five strategic plays for 2026 (prioritized)
- Accelerate digital interoperability: Implement API-first product designs and certify integrations with major digital pathology platforms. Short-term wins include reduced workflow friction and increased stickiness through software-driven services.
- Shift to outcome-linked commercial models: Test service-plus-consumables subscriptions that align pricing with throughput and histology turnaround-time guarantees, converting one-time instrument sales into predictable annuities.
- Protect and monetize installed base: Deploy remote diagnostics, preventive maintenance analytics, and consumable replenishment programs to lift service margins and reduce churn.
- Targeted M&A for capability gaps: Pursue tuck-ins that add specialized cryostats, ultramicrotomy, or consumables with repeatable gross margins and clear cross-sell paths. Use a checklist that emphasizes regulatory status, installed-base concentration, and digital readiness.
- Build supply resilience: Qualify secondary suppliers for critical raw materials (including blade metallurgy), establish strategic safety stock policies, and negotiate long-term offtake where necessary to protect production continuity.
Decision-support tools included with the report
To convert insight into executable plans, PW Consulting provides a suite of tools:
- Interactive financial model with scenario switches (price, uptake, service penetration).
- Vendor scorecard templates and RFP evaluation matrices tailored to tissue sectioning procurement.
- TCO and ROI calculators for capital investments in automated sectioning platforms.
- M&A diligence playbook and pro forma synergies estimator focused on instrument + consumable roll-ups.
- Regulatory impact simulator to quantify time-to-market and recall-cost scenarios under multiple regulatory jurisdictions.
How to use this intelligence in your 2026 planning cycle
Senior leaders should treat this report as an executable input to three board-level decisions commonly revisited during 2026 planning: 1) capital expenditure envelopes for diagnostic equipment; 2) prioritization of product development bets around automation and digital integration; and 3) M&A targets and partnership landscapes to accelerate scaling. Recommended next steps:
- Run a one-day strategy session using the report’s scenario model to stress-test your 36-month product roadmap against high- and low-adoption cases.
- Use the vendor scorecard to shortlist two preferred suppliers for pilot rollouts and negotiate pilot terms that include interoperability milestones and shared KPIs.
- Map your supply-chain single points of failure and implement at least two immediate mitigations for critical consumable exposures.
Final note — preview, not the full dataset
This release is intentionally diagnostic rather than exhaustive. We have emphasized actionable frameworks, competitive implications, and recommended plays while withholding the granular regional and product-level breakdowns that underpin our models. Those detailed tables, full Excel models, and the vendor-by-vendor revenue maps are available in the full PW Consulting Worldwide Tissue Sectioning Market report and are designed to support commercial diligence, investor memoranda, and board-ready strategic plans.
If your organization is preparing procurement, development, or M&A decisions in 2026, the insights and tools contained in the full report will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Worldwide Tissue Sectioning Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com