

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Packaging Reel Market to Reach USD 2,064.9 Million by 2032 at 5.18% CAGR — Asia Pacific Dominates 2025 Market with USD 682.8M, Top‑5 Hold 52.1%

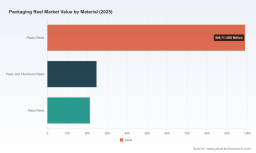
Worldwide Packaging Reel Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Packaging Reel market equips corporate leaders with the strategic intelligence they need to make high-consequence decisions in 2026. Built on a five‑year historical base and a seven‑year forecast horizon, the report shows the global market expanding from a 2025 base of USD 1,450 Million to a materially larger opportunity by the end of the forecast window, driven by steady demand and product innovation. The study’s headline compound annual growth rate (CAGR) for the 2026–2032 forecast period is 5.18% — a signal that incumbents and new entrants alike must combine operational rigor with selective investment to capture profitable growth.
Worldwide Packaging Reel Market
What decision-makers should read first
- Macro positioning: The report translates topline market momentum into near‑term strategic choices — where to allocate capex, when to expand production footprints, and how to prioritize sustainability-linked investments.
- Competitive posture: We provide an evidence‑based view of competitive concentration and capability clusters to help procurement, product, and corporate development teams identify defensible plays and potential consolidation targets.
- Regulatory & input risks: The analysis integrates regulatory trajectories and raw‑material volatility scenarios so commercial leaders can stress‑test pricing and sourcing strategies before committing capital.
Why this market matters for 2026 strategy
Packaging reels remain a foundational upstream node in the flexible and industrial packaging value chain, feeding converters, OEMs and contract packers across electronics, medical, food, and consumer segments. The market’s steady expansion and the reported 5.18% CAGR reflect two concurrent dynamics: technology-driven premiumization (high‑barrier, mono‑material, and bio‑resin reels) and regulatory-driven substitution (increasing recyclability and recycled content mandates). For 2026, executives must treat packaging reels not as a commodity line item but as a strategic lever that affects product compliance, brand sustainability claims, and margin retention across downstream portfolios.
Worldwide Packaging Reel Market
Key trends shaping near‑term decisions
- Sustainability engineering: The transition toward recyclable mono‑materials and paper‑hybrid solutions is accelerating. Leading suppliers are rolling out recyclable film constructions and paper‑based reel covers to simplify conversion and end‑of‑life processing; these technologies are moving from demonstration to commercial deployment.
- Material and feedstock dynamics: Raw‑material cycles and resin availability remain a core earnings driver for reel manufacturers. Early 2024 saw downward pressure on certain polyethylene grades in North America, altering raw‑material spreads and creating short windows of procurement advantage. Buyers and hedgers should anticipate episodic price swings and plan inventory strategies accordingly.
- Regulatory tightening: Regional mandates are reshaping acceptable formats and effective cost structures. Across advanced markets, regulations are tightening recyclability and recycled content requirements; at the same time, select jurisdictions have introduced tax regimes and producer obligations that meaningfully shift cost calculus for low‑recycled content films.
- Trade and supply‑chain frictions: Trade measures and tariffs on certain origins continue to redirect flows, adding a layer of geopolitical risk to sourcing decisions. This environment favors multi‑supply portfolios and nearshoring for mission‑critical grades.
- Product innovation and premiumization: Expect sustained demand for barrier, medical‑grade, and high‑printability reels, as brand owners prioritize shelf‑life, safety, and aesthetic differentiation.
Competitive landscape — what the report reveals (and what it withholds)
Our competitive review profiles the primary global and regional players whose product strategies and recent initiatives are reshaping the market. The sector shows moderate concentration: the top three firms collectively account for a meaningful share of revenues, and the top five account for over half of market sales, implying that both scale and specialized capability matter. That concentration pattern presents clear strategic choices: scale through capacity and distribution, or focus on differentiated, higher‑margin niche capability.
Worldwide Packaging Reel Market
Highlights from company observations (summarized):
- Amcor plc leverages broad flexible‑film capabilities and is pivoting toward recyclable mono‑materials — visible through new showcase rollouts at major industry events.
- Berry Global Group applies polymer engineering expertise to develop bio‑resin and performance films tailored for form‑fill‑seal applications.
- Mondi is advancing paper‑based reel covers and hybrid constructions, positioning for customers seeking reduced plastic intensity.
- Huhtamäki and Constantia Flexibles continue to defend premium food and medical segments with high‑barrier co‑extrusions and laminated offerings.
- Regional champions such as Uflex and Cosmo Films are strengthening their export reach with jumbo‑reel capabilities and high‑printability grades, while Winpak and Sealed Air emphasize medical and protein‑focused barrier solutions.
The report includes granular company profiles — technology roadmaps, capacity footprints, and recent go‑to‑market moves — but, in keeping with our “trailer” approach, we intentionally limit the commercial release of certain segment‑level analytics in this preview. Subscribers obtain the full competitive matrix, sourcing maps and supplier scorecards in the complete dataset.
Operational playbook: what to do in 2026
Translate insight into action with a pragmatic three‑track playbook:
- Secure supply while you pivot. Lock short‑to‑medium contracts on strategic film grades during windows of raw‑material softness, while onboarding alternative suppliers for critical reels to mitigate tariff and logistics shocks.
- Invest selectively in sustainability engineering. Pilot mono‑material film formats on high‑visibility SKUs and use conversion cost analysis to quantify the total cost of ownership, including rebates, taxes and end‑of‑life logistics.
- Protect margin via product and commercial segmentation. Differentiate pricing by quality attributes (barrier performance, regulatory compliance, printability) rather than by commodity resin alone; use the report’s pricing and margin archetypes to build tiered commercial offers.
Report contents — practical tools inside
The full PW Consulting report is engineered for deployment by commercial, supply‑chain and corporate development teams. Key deliverables include:
- Topline market model (2020–2032) with scenario toggles for polymer price paths and regulatory shock events;
- Supplier scorecards and capability heat maps to accelerate sourcing and qual processes;
- Regulatory impact matrices crosswalked to reel formats and downstream conversion costs;
- Five validated buyer playbooks (procurement, product development, sustainability, pricing and M&A);
- M&A target shortlist methodology and deal comparators based on capability and regional fit;
- Interactive dashboards for total cost of ownership modeling across material, conversion and end‑of‑life channels.
Risks and scenario sensitivities
Our sensitivity work highlights three risk vectors that require continuous monitoring in 2026: raw‑material volatility, accelerated regulatory mandates (e.g., expanding recyclability and producer obligations), and trade‑policy shifts that can reroute supply flows. Each vector has asymmetric impacts across reel grades and customer segments; the report provides probability‑weighted scenarios and mitigation playbooks tied to procurement and pricing actions.
How PW Consulting helps you act
PW Consulting combines industry‑level data with transaction experience and operational know‑how. For 2026 planning cycles we offer modular engagements: a rapid two‑week supplier due‑diligence sprint, a six‑week commercial transformation program that uses our pricing archetypes, and a full strategic advisory package that includes M&A screening and post‑deal integration templates. Each engagement is grounded in the report’s validated dataset and built to translate insights into measurable outcomes.
Next steps
This release is a strategic preview intended to inform senior planning conversations. For access to the full dataset — including regional and end‑use splits, supplier financials, and the scenario dashboards — visit the PW Consulting report page. The full report contains the granular segmental tables and appendices that operational teams will use to finalize 2026 budgets, sourcing commitments, and R&D roadmaps.
In a market where regulatory timelines compress and material science advances unlock new formats, the opportunity for value creation is clear but conditional: firms that combine disciplined procurement, targeted innovation investment, and a governance process for regulatory change will convert market growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Packaging Reel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com