

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Engine Oil Additives Market Set to Expand at a 3.21% CAGR, New Insights Reveal

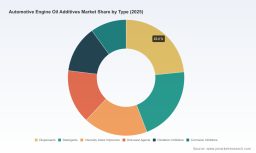
Worldwide Automotive Engine Oil Additives Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Automotive Engine Oil Additives Market delivers a pragmatic, decision-ready intelligence package tailored for C-suite and business-unit leaders planning for 2026. Our base-year assessment (2025) and a seven-year forecast (2026–2032) combine a rigorous market-sizing exercise with a forward-looking strategic playbook. The market has expanded from roughly USD 15.2 billion in 2020 to about USD 18.0 billion in 2025, and our model projects continued growth through 2032, reaching approximately USD 22.5 billion under the central scenario — an implied compound annual growth rate of 3.21% for the forecast period. Competitive dynamics remain concentrated (CR3 ~62.5%; CR5 ~81.2%), underscoring that a relatively small set of global players will continue to shape pricing, technology adoption, and standards compliance.
Worldwide Automotive Engine Oil Additives Market
Why this matters for 2026
-
Standards and regulations that became effective in 2025 and subsequent clarifications in 2026 materially alter the product and commercialization roadmap for additive suppliers and oil marketers. The transition window extended by standards bodies into late 2026 creates both tactical opportunities and strategic risks for market entrants and incumbents.
Worldwide Automotive Engine Oil Additives Market -
Volatility in base oil and additive feedstock pricing, driven by geopolitical events and supply-chain disruptions, has compressed margins and forced rapid re-prioritization of sourcing and hedging strategies in early 2026.
Worldwide Automotive Engine Oil Additives Market -
Technological expectations — notably around fuel-efficiency gains, low-speed pre-ignition (LSPI) mitigation, and reduced SAPS formulations — are now explicit procurement criteria for many OEMs and oil marketers, shifting R&D and commercialization calendars.
Market dynamics — what’s changing
Three broad forces are shaping the 2026 decision landscape for engine oil additive suppliers:
-
Regulatory and standards evolution: The introduction and adoption of the latest passenger car motor oil specifications (licensing effective in 2025) and companion API categories (including a new category addressing ultra-low viscosity grades) raise the technical bar for additive packages. The standards bodies’ decision to extend overlap periods into 2026 gives manufacturers extra runway but raises risk for those that delay.
-
Raw-material and cost pressures: Early 2026 saw base oil and additive costs spike due to geopolitical tensions and supply-chain constraints, with industry reports noting finished-lubricant and component price increases approaching the high teens in percentage terms. That environment favors suppliers with strong procurement sophistication, regional sourcing flexibility, or integrated upstream exposure.
-
Structural demand shifts: Vehicle electrification and hybridization create a complex demand profile. While full battery-electric vehicles reduce engine-oil demand for those powertrains, hybrid powertrains and a global vehicle parc that still includes a large installed base of internal-combustion engines preserve sizeable demand — but with altered product specifications and longer replacement cycles.
Competitive landscape — players to watch
The engine oil additives market remains technology- and relationship-driven. Our competitive assessment synthesizes public disclosures, standards participation, and product launches to highlight where advantaged players are focusing in 2026.
-
The Lubrizol Corporation (Wickliffe, Ohio): A large global supplier with recent launches that target compliance with the latest passenger car specifications. Their product cadence and strong OEM relationships make them a primary benchmark for additive performance and time-to-market.
-
Infineum International Limited (Abingdon, UK): Leveraging joint-venture scale and expertise in fuel-efficiency technologies, Infineum is focused on formulations that mitigate LSPI and align with ultra-low viscosity demands.
-
Afton Chemical Corporation (Richmond, Virginia): Broad focus across passenger-car and heavy-duty formulations with emphases on driveline and fuel-additive synergies that matter for hybrid platforms.
-
Chevron Oronite Company LLC (San Ramon, California): With a strong OEM-approval portfolio, their branded OLOA technologies remain relevant for companies seeking global compliance pathways.
-
BASF SE, Evonik Industries AG, LANXESS AG, Croda International, Vanderbilt Chemicals : European and specialty-chemistry players that bring critical competencies in antioxidants, viscosity-index improvers, bio-based friction modifiers, and extreme-pressure chemistries.
-
Selected China-based producers : Regional suppliers with high-volume manufacturing and cost-competitive positions that increasingly support global OEM supply chains and domestic mixer-customers.
These firms are deploying a mix of product development, standards engagement, and selective regional capacity investments. Recent notable developments include targeted product launches aligned to the new specifications and prominent industry exhibition activity that signal where R&D resources are concentrated.
Strategic imperatives for entrants and incumbents in 2026
Our research identifies a concise set of actions that materially affect three- to five-year outcomes. Companies that prioritize these moves will be better positioned to protect margin and capture share as the market re-prices and standards evolve.
-
Fast-track standards-aligned formulations. Firms must prioritize GF-7/API-SQ correlated technologies (fuel-economy, LSPI mitigation, piston cleanliness). A “standards-first” product roadmap reduces time-to-approval risk and shortens OEM qualification cycles.
-
Hedge input-cost volatility. Establish multi-sourcing strategies, strategic inventory positioning, and commodity-derivative hedges where feasible. Consider localized blending or toll-manufacturing agreements to reduce exposure to long-haul logistics shocks.
-
Defend and expand OEM channels. Invest in co-development programs and lab-to-vehicle validation capabilities. OEM approvals remain the steepest barrier to market entry; partnership models are often the fastest route across that barrier.
-
Differentiate on service and formulation intelligence. Offer customers not just additive packages but predictive lab data, blend optimization tools, and lifecycle cost modeling that directly tie additive selection to TCO improvements for oil marketers and fleets.
-
Prioritize sustainability and bio-based chemistries. Low-SAPS and bio-derived friction modifiers are moving from niche to procurement checklist — early investment reduces future retrofit costs and supports premium positioning.
-
Evaluate M&A and alliances selectively. With market concentration high, bolt-ons that close technological gaps (e.g., VII, LSPI chemistries) or provide regional manufacturing scale will generate disproportionate value versus greenfield investments.
What PW Consulting’s report delivers — the practical toolkit
This study is structured to be operationally useful for commercial, technical, and corporate-strategy teams preparing 2026 plans. Key deliverables include:
-
Verified market-sizing and scenario models (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity testing against alternative macro and raw-material cost trajectories.
-
Regulatory timelines and a standards-impact matrix mapping GF-7 / API updates to additive-technology requirements and likely OEM adoption curves.
-
Competitive heat maps that identify capability gaps at product, regional, and go-to-market levels — enabling prioritization of R&D and M&A targets.
-
Procurement playbooks addressing short-, medium-, and long-term sourcing tactics in the face of price shocks and supply disruptions.
-
Commercial templates for license negotiations, OEM trials, and oil-marketer conversion programs focused on minimizing cycle time to market.
How to use these insights in 2026
-
CEO / Board: Use the scenario outputs to stress-test earnings guidance and M&A prioritization against alternate raw-material and standards-transition timelines.
-
R&D Heads: Map portfolio roadmaps to the specifications matrix and prioritize chemistries linked to fuel-economy and LSPI outcomes; accelerate bench-to-dyno validation plans where possible.
-
Procurement / Supply Chain: Implement multi-sourcing strategies and define hedging triggers in procurement contracts; prioritize regional redundancy in critical intermediates.
-
Commercial Teams: Recalibrate pricing and value messaging to emphasize lifecycle cost savings, compliance assurance, and application-specific performance for hybrid engine platforms.
Conclusion — an operationally focused preview
For leaders who must make near-term resource-allocation and go-to-market decisions, the 2026 window is less about if change will occur and more about who adapts fastest. Our central forecast anticipates modest yet consistent growth across the seven-year horizon (2026–2032) and highlights how concentrated market structure advantages incumbents that can move quickly on standards, manage input volatility, and offer more than just chemistry — i.e., lab validation, OEM approvals, and commercial execution.
PW Consulting’s full report contains the granular segmentation, supplier matrices, and downloadable models that underpin the strategic guidance summarized here. For confidential briefings, interactive scenario runs tailored to your P&L, or to unlock the full dataset underlying our projections, please refer to the publication page linked from PW Consulting’s Worldwide Automotive Engine Oil Additives Market report announcement.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Engine Oil Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com