

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Oat-based Cereal Market Poised to Grow at a 5.34% CAGR Through 2032

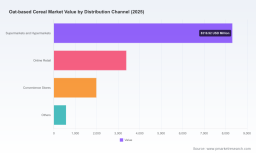
Worldwide Oat-based Cereal Market: Strategic Preview for 2026—What Senior Executives Need to Know
PW Consulting’s latest market study on the Worldwide Oat-based Cereal Market offers a forward-looking playbook for boards, strategy teams, and functional leaders preparing decisions in 2026. The market has demonstrated resilience and expansion through the early 2020s, rising from the low‑double-digit billions in 2020 to a projected global market size of roughly USD 14.25 billion in 2025. Our model forecasts continued momentum into the next planning cycle, with the sector approaching the low‑twenty billions by the end of the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 5.34% for that period. These headline dynamics create distinct opportunity windows—and real operational risks—that demand immediate action from manufacturers, retailers, ingredient suppliers, and investors.
Worldwide Oat-based Cereal Market
Why this report matters to 2026 decision-making
-
Precision for prioritization: The report translates macro growth into practical decision frames—helping executives prioritize R&D, route-to-market investments, and capital allocation across core programs without relying on intuition alone.
Worldwide Oat-based Cereal Market -
Timing of bets: Our forecast identifies when demand inflection points will create premiumization, value-tier expansion, or channel displacement pressures—critical for timing product launches and promotional spend in 2026.
Worldwide Oat-based Cereal Market -
Risk triage: By quantifying concentration in the competitive landscape and mapping systemic supply risks, the study supports scenario planning for recalls, raw-material volatility, and regulatory shifts.
-
Commercial playbooks: The report couples growth forecasts with go-to-market templates and retailer negotiation levers—designed for commercial teams to convert category momentum into share and margin gains.
Market snapshot and structural dynamics
Oat-based cereals have moved from a differentiated health niche to mainstream staple in many markets, driven by nutrition positioning (notably beta‑glucan and heart-health narratives), clean-label trends, and product innovation across formats. Our historical analysis shows steady expansion between 2020 and 2025, with an acceleration in premium and ready-to-eat segments. Looking ahead, a mid-single-digit CAGR of 5.34% over 2026–2032 implies a market that is large enough to justify scale investments yet fragmented enough to reward targeted differentiation and agile execution.
Concentration metrics in the report indicate a moderate level of market concentration: the top three players command over 40% of the market, while the top five approach the mid‑50s (percent). This structure favors incumbent brands with deep retail relationships and scale manufacturing—but also provides room for challenger brands, private label expansion, and regional specialists to carve out meaningful niches.
Supply-side and regulatory context impacting 2026 planning
-
Raw-material volatility: Oat prices have shown upward pressure, with U.S. average prices moving higher in 2023 due to acreage reductions. Procurement and operations teams must incorporate forward hedging, long-term contracting, and cultivar diversification into 2026 sourcing strategies to protect margins.
-
Labeling and health claims: Regulatory regimes continue to tilt in favor of evidence-based health messaging. The FDA’s labeling updates, which emphasize functional claims such as beta‑glucan’s contribution to heart health, and existing EU rules that set minimum thresholds for oat beta‑glucan claims, create both marketing advantages and compliance obligations. Product teams should align formulations to meet claim thresholds while preparing substantiation dossiers for new markets.
-
Food safety vigilance: High‑profile recalls in recent years have heightened buyer sensitivity and retailer audit intensity. Traceability, supplier qualification, and end-to-end quality assurance will be board-level priorities in 2026.
Competitive landscape: capabilities and gaps
Our report includes in-depth profiles of leading multinational and specialty players. Below is a synthesized strategic read of core incumbents and what their moves imply.
-
General Mills (Minneapolis, MN) — Leverages a globally recognized cereal franchise to extend oat-based innovations. Brand depth and SKU density create cross-sell opportunities, but scale portfolios must be balanced with agility to capture premium niche trends.
-
PepsiCo / Quaker Oats (Purchase, NY) — A historic oat player in ready-to-eat formats; its scale in ingredients, distribution, and co‑manufacturing remains a competitive moat. However, recent product-safety events have elevated reputational and operational risk, making investments in supply-chain transparency and rapid recall management non-negotiable.
-
WK Kellogg Co (Battle Creek, MI) — Strong in co‑branded and differentiated product forms. Kellogg’s challenge and opportunity are converting cereal heritage into oat-forward narratives that resonate with younger or health-first consumers.
-
Post Holdings (Brentwood, MO) — Competes through niche positioning and fiber-led messaging. Post’s playbook is instructive for companies aiming to scale high-fiber variants without ceding price competitiveness.
-
Specialist and regional players (Nature’s Path, Bob’s Red Mill, Weetabix, Nestlé, Hero Group) — These firms illustrate three viable routes to growth: organic/clean-label premiumization, artisanal and whole‑grain authenticity, and fortified/functional innovation. Their success underscores the importance of differentiated sourcing, small-batch innovation pipelines, and selective channel partnerships.
Recent developments that should shape 2026 plans
-
Product-safety events: Extended recalls tied to certain oat-based SKUs in late 2023–2024 have raised retailer and consumer expectations for traceability and rapid response systems.
-
New product introductions: Incumbents continue to invest in flavor and format innovation—demonstrating that incremental SKU refreshes remain a fast route to incremental sales if supported by trade presence.
-
Trade and demonstration activity: The visible presence of organic and high‑margin oat launches at industry shows signals that retailers will keep allocating shelf space to emerging oat propositions.
What the report contains (practical, decision‑ready modules)
-
Executive synthesis and 2026 action checklist—aligned to board timelines and annual planning cycles.
-
Market-size modeling and scenario forecasts—baseline, upside, and downside projections with sensitivity to raw-material and regulatory shocks.
-
Go-to-market playbooks—SKU rationalization, pricing ladders, pack-size optimization, and retailer negotiation templates tailored for different route-to-market strategies.
-
Supply-chain resilience toolkit—supplier scorecards, traceability requirements, and contingency playbooks for rapid recall events.
-
Competitive intelligence—detailed company profiles, innovation pipelines, M&A activity map, and benchmarking against best-practice KPIs.
-
Retail and channel strategy—omnichannel tactics and conversion levers for supermarkets, e‑commerce, and on‑the-go channels.
-
Regulatory and claims compendium—practical thresholds, labeling dos and don’ts, and dossier templates for health claim substantiation.
Actionable recommendations for 2026
-
Prioritize traceability and QA investments now—install batch-level traceability and rapid recall protocols as capital priorities to protect brand equity and avoid costly supply disruptions.
-
Design claim-compliant formulations—ensure new product concepts meet regulatory thresholds for beta‑glucan and other function-related claims before launch to avoid rework and market delays.
-
Hedge and diversify oat supply—combine forward contracts, geographic diversification, and varietal sourcing to limit commodity cost exposure.
-
Segment product tiers with clear margin strategies—reserve premium innovation budgets for formats and channels that can bear higher ASPs, while using targeted value SKUs to defend share in price-sensitive segments.
-
Invest in omnichannel conversion—use SKU and pack-size analytics to optimize the mix for digital shoppers versus brick-and-mortar buyers, and deploy subscription models where viable.
-
Explore selective M&A and JV opportunities—acquire capabilities in clean-label processing, organic certification, or regional distribution to accelerate entry into high-growth niches without diluting core brands.
-
Elevate sustainability narratives—with measurable claims (e.g., regenerative oats, reduced water footprint) that are auditable and resonate with retail sustainability scorecards.
Frequently asked strategic questions (preview)
-
How material is commodity risk to margin in 2026? Answer: Material enough to require proactive procurement hedging and contract strategies—our scenario work shows margin erosion under sustained price spikes without mitigation.
-
Should companies prioritize scale or premium niche in 2026? Answer: Both paths are viable. The right choice depends on your cost base, brand equity, and route-to-market advantages; the report provides a decision matrix to determine optimal focus.
-
What immediate steps should retailers take? Answer: Improve supplier auditing and SKU rationalization to reduce recall exposure and improve shelf productivity; our retailer playbook includes negotiation levers tied to safety and sustainability KPIs.
PW Consulting’s report is deliberately structured as a decision support system: it surfaces the hypotheses, validates them with granular modeling, and delivers playbooks and templates that management teams can operationalize during 2026 planning cycles. To preserve the strategic value of the dataset and support your planning workshops, we have intentionally omitted granular public exposure of core segment split data in this preview—those detailed tables, SKU-level analytics, and regional routing matrices are available in the full report.
For boards, strategy teams, and investor groups preparing 2026 plans, the full report is the single most efficient means to convert the macro tailwinds and tactical warnings summarized here into executable initiatives. Visit our official publication page to download the comprehensive study, access interactive dashboards, and schedule a briefing with PW Consulting’s senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Oat-based Cereal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com