

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide TRIS Buffer Market Poised to Hit USD 498.29 Million by 2032, Growing at a 6.32% CAGR

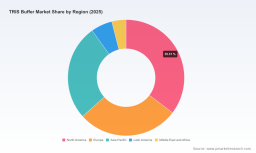
Worldwide TRIS Buffer Market — Strategic Preview for 2026 Decisions
PW Consulting’s newest market research preview on the Worldwide TRIS Buffer Market delivers a compact, decision-ready briefing for executives, procurement leaders, and R&D strategists preparing plans in 2026. Drawing on an extended historical series (2020–2025) and a seven-year forecast horizon (2026–2032), this analysis synthesizes commercial, supply-chain, regulatory, and competitive signals that will materially affect sourcing, pricing, and investment choices for biological-grade and industrial TRIS products.
Worldwide TRIS Buffer Market
Why this preview matters to 2026 strategy
- Actionability: The report translates market dynamics into practical options — procurement hedges, supplier playbooks, and contingency scenarios — so you can move from insight to implementation during the year ahead.
- Timing: With macro momentum and regulatory inflection points materializing in 2026, the choices made this year will determine cost exposure and capacity access through the next planning cycle.
- Focus: We spotlight risk vectors that most commonly derail TRIS-dependent programs — raw-material volatility, concentrated production nodes, and evolving trade remedies — and provide decision trees to prioritize mitigation investments.
Market trajectory — macro facts you can act on
At the macro level, the TRIS buffer market has demonstrated steady expansion across the 2020–2025 period, growing from a defined base to a significantly larger market in the 2025 base year (reported in USD Million). Our modeling projects continued growth through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.32%, reaching an estimated market size by 2032 that represents a material upside to current capacity plans. These headline dynamics create a planning imperative for firms whose workflows or product pipelines depend on TRIS buffers.
Worldwide TRIS Buffer Market
Two strategic implications follow immediately. First, buyers should expect upward pressure on availability and premiums for higher-purity grades unless supply-side capacity is actively expanded or demand-side substitution accelerates. Second, the market scale and steady CAGR justify targeted investments in supplier qualification, dual-sourcing contracts, and inventory optimization for organizations that cannot tolerate disruption in nucleic-acid workflows, protein purification, or bioprocess buffers.
Worldwide TRIS Buffer Market
Supply-side dynamics and raw-material signals
Our industry diagnostics identify three supply-side drivers that will shape 2026 outcomes:
- Capacity versus consumption balance: Global production capability for the underlying chemical reached industry-scale volumes in recent years, and available evidence shows that installed capacity has historically sat only modestly above consumption. That cushion gives manufacturers limited room to absorb demand spikes without invoking price adjustments or allocation logic.
- Input-cost sensitivity: Nearly one-third of producers report raw-material cost fluctuations as a primary constraint on both production intensity and price stability. For buying organizations, this translates into an elevated probability of mid-cycle price renegotiations unless contracts include explicit indexation or fixed-price windows.
- Quality segmentation: Downstream users increasingly differentiate between analytical/biological grades and industrial grades. Premium supply chains for life-science applications remain concentrated among vendors that operate to recognized quality systems and compendial standards; as a result, lead times and qualification overheads for high-purity TRIS remain higher than for commodity grades.
Regulatory and trade environment — a 2026 inflection
Regulatory activity has heightened systemic risk in the TRIS market. In 2026 a major North American manufacturer initiated antidumping and countervailing duty actions that, if sustained, could lead to steep tariff overlays on certain import flows. That petition alleges very large dumping margins and signals an elevated chance of trade remedies that would reallocate demand toward domestically produced and regionally sourced inventory.
For corporate decision-makers, the practical consequence is clear: procurement strategies that were optimized for a low-tariff environment must be stress-tested for scenarios that include import restrictions and sudden shifts in landed cost. The report provides a pragmatic regulatory risk matrix and scenario templates that quantify the impact of tariff-like measures on landed cost, supplier scores, and switching thresholds.
Competitive landscape — who matters and why
The TRIS market displays moderate concentration, with the top-tier suppliers capturing a meaningful share of commercial volumes while a broader set of regional producers supply differentiated grade and packaging options. A compact set of global incumbents and specialized manufacturers control critical capacity and certified grades; their strategic moves will influence supply reliability and price dynamics into 2026 and beyond.
- Integrated, dual-site manufacturers — exemplified by a fully integrated supplier operating production facilities in North America and Europe — provide resilience for regulated customers through regional manufacturing redundancy and ISO-certified quality systems. Recent capacity additions and product-line expansions by such players have strengthened their position in regulated supply chains.
- Regional specialty producers in Asia supply large volumes across multiple purity tiers and remain an essential source of scale for global buyers. These suppliers are the backbone of commodity availability but face increasing scrutiny from cost- and standards-driven buyers when qualification for bioprocess-grade materials is required.
- Large lab-supply and life-science distributors and brands retain outsized influence over channel dynamics and customer access. Their extended product catalogs, distribution networks, and value-added services (e.g., custom buffer formulation, smaller package sizes, and traceable quality testing) make them preferred partners for research and clinical laboratories seeking fast fulfillment and technical support.
The full report contains detailed supplier profiles, capacity maps, and a five-point supplier-risk scoring model that synthesizes quality certifications, manufacturing footprint, regulatory exposure, and supply-chain flexibility — a practical toolset for developing sourcing strategies that balance cost, lead time, and compliance.
Recent industry developments that change the playbook
- Capacity investments: Several suppliers expanded production capabilities or buffer-preparation capacity in 2025 and 2026, a response to demand growth in life sciences and to customers seeking regional supply assurance.
- Channel realignment: New and expanded distribution agreements across North America and Europe are shortening time-to-market for certain high-purity buffer portfolios, while also introducing contractual interdependencies that merit closer review in procurement negotiations.
- Trade-action risk: The filing of trade remedy petitions in 2026 has already changed risk-appetite for some buyers; contingency sourcing plans and supplier diversification strategies are now moving from “nice to have” to “table stakes.”
What PW Consulting’s report delivers — practical content summary
This preview is purpose-built to motivate and guide executive action. The full report (base year 2025, forecast through 2032) contains the following operational modules designed for immediate use by strategy, procurement, and product-development teams:
- Demand-modeling engine: A configurable model that maps use-cases to volumes and stress-tests demand under scenario assumptions (pandemic re-runs, accelerated therapeutic pipelines, tariff events).
- Supply-mapping and capacity dashboard: Geospatial overlay of certified manufacturing assets, lead-time bands, and grade capabilities to support dual-sourcing and nearshoring decisions.
- Price-sensitivity and cost-to-serve analysis: Indexed cost scenarios that incorporate raw-material volatility and common supplier contract terms.
- Quality and regulatory playbooks: Checklists and qualification templates for ACS/ISO/cGMP claims, plus a regulatory risk matrix for trade-remedy scenarios and import compliance.
- M&A and CAPEX scoring: A rapid due-diligence framework to evaluate acquisition targets, tolling partners, and greenfield investments against demand forecasts and strategic fit.
- Procurement negotiation toolkit: Template SLAs, penalty structures, and inventory policy algorithms tailored to TRIS-grade distinctions.
How to use the intelligence — five recommended next moves for 2026
- Conduct a quick supplier-stress test: Use the supply-mapping output to identify single points of failure for any grade of TRIS used across your product and research portfolio.
- Lock a short-duration hedge on premium volumes: For organizations with low tolerance for quality-risk, secure fixed-price or capped-price windows for a portion of demand while maintaining spot flexibility for the remainder.
- Qualify a secondary regional supplier now: Even a limited qualification program reduces exposure to regulatory or logistical chokepoints and is typically faster and cheaper than emergency onboarding later.
- Integrate regulatory scenarios into procurement playbooks: Add simple decision gates that trigger alternative sourcing or inventory actions when trade-remedy or antidumping case statuses cross predefined thresholds.
- Use the M&A scoring tool for vertical options: If supply security is strategic, the scoring framework helps rapidly assess whether acquisition, tolling agreements, or long-term capacity investments make sense relative to outsourcing.
Conclusion — why 2026 is a strategic inflection year
The TRIS buffer market’s steady growth and the concentration of certified production capacity create both opportunity and risk. Growth justifies investment in resilience and supplier relationships; regulatory motion and input-cost volatility demand operational rigor. PW Consulting’s report is designed to turn macro visibility — a clear CAGR and multi-year market trajectory — into micro-level decisions: who to qualify, how much inventory to hold, and when to invest in capacity versus contract protection.
For sourcing leaders and corporate strategists, the most valuable edge in 2026 will be the ability to translate market-scale signals into executable supplier and procurement strategies before adversarial events (tariffs, capacity shortfalls, or raw-material spikes) force rationing decisions. Our full report equips teams with the models, playbooks, and supplier intelligence required to make those calls with confidence.
Get the complete intelligence
This preview is intentionally high-level to highlight the strategic thrusts and operational levers that matter most. The full Worldwide TRIS Buffer Market report provides the granular segmentation, supplier scoring, and downloadable decision tools that procurement, R&D, and corporate development teams will use to operationalize the recommendations above. Visit our report page to access full data tables, scenario models, and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Worldwide TRIS Buffer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com