

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Baggage Packaging Service Market to Reach USD 1,453.93 Million by 2032, Expanding at a 6.51% CAGR

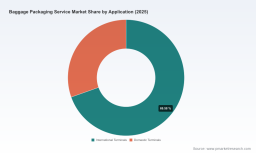
Worldwide Baggage Packaging Service Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Baggage Packaging Service market delivers an executive-grade synthesis designed to inform corporate strategy, procurement, sustainability programs, and M&A diligence in 2026. With a clearly defined base year of 2025 and a focused forecast horizon through 2032, this study converts granular operational realities into boardroom-ready strategic options. The market is on a sustained growth trajectory — our model shows a mid-single-digit compound annual growth rate (CAGR) of 6.51% across the forecast window, moving total industry revenue from a 2025 baseline to an expected market size approaching USD 1.45 billion (Million USD unit) by 2032.
Worldwide Baggage Packaging Service Market
Why this report matters for 2026 planning
-
Timing: Airlines, airport operators, and vendor partners are revising service contracts and capital plans in 2026. The market’s predictable growth and concentration profile create a narrow window for tactical moves — whether to secure capacity, lock in technology licensing, or accelerate sustainable-material transitions.
Worldwide Baggage Packaging Service Market -
Investment clarity: The report translates revenue trajectories into cash-flow implications for service operators and OEMs of wrapping equipment, enabling CFOs and strategy leads to stress-test investment cases against realistic adoption curves and operational KPIs.
Worldwide Baggage Packaging Service Market -
Regulatory foresight: An integrated compliance playbook anticipates the operational impact of mounting packaging Extended Producer Responsibility (EPR) rules and state-level mandates in major markets, enabling preemptive cost allocation and supplier negotiations.
-
Competitive playbook: We map competitive strengths and recent product moves to expose where premium service differentiation (technology, sustainability, and traceability) will command margin premium vs. where scale and network density remain decisive.
High-level market dynamics — what’s driving growth and disruption
-
Demand-side tailwinds: Travel recovery, greater baggage protection expectations, and heightened hygiene considerations continue to drive per-bag uptake of protection services in terminals and intermodal hubs. Our scenario framework quantifies adoption under conservative, base, and upside travel scenarios so clients can align capacity investments with risk appetite.
-
Supply-side pressures: The sector remains dependent on polymer films (primarily LDPE and LLDPE). Volatility in plastics input prices is material — for example, US producer-price indices for plastics films remain elevated through early 2026 — creating near-term cost push that operators must either absorb, hedge, or pass through via pricing models.
-
Regulatory closure: EPR regimes now span multiple US states and expanding international frameworks, shifting end-of-life costs onto producers and service providers. Operators who integrate recyclable or biodegradable film options early will mitigate fee exposure and gain procurement leverage with airports setting sustainability targets.
-
Technology and automation: Innovations in automated wrapping platforms, digital tracking (including NFC-enabled solutions), and material-efficiency improvements are changing unit economics. New machine generations reduce film consumption per bag and speed throughput — critical where labor cost or terminal dwell constraints limit manual service rollouts.
Competitive landscape — synthesis and strategic implications
-
Market structure: The baggage packaging service market is moderately concentrated. The top three incumbent groups account for a meaningful share of revenue, while the top five consolidate a clear majority. That structure creates differentiated dynamics: large operators secure airport concessions and roll out equipment networks quickly; mid-tier players compete on local presence, specialized service packages, or sustainability credentials.
-
Profiles to watch:
-
Safe Bag S.p.A. (TraWell) — a technical and network leader in airport baggage protection and tracing. Their recent product introduction of a next-generation automatic wrapping platform includes NFC-based digital tracking and a material-efficiency lift that reduces film consumption per bag — a commercially significant improvement for both cost and sustainability KPIs.
-
Secure Wrap (US) — a market-leading operator in TSA-authorized services, notable for tamper-evident offerings and operational conveniences such as complimentary rewraps after security inspection. Their product and service positioning make them a valuable partner for carriers and airport retail programs.
-
BagWrap, Wrap N’ Fly, TrueStar Group (Wrap and Fly), Seal & Go, Encalm Enwrap, and Excess Baggage Company — collectively they demonstrate two strategic playbooks: (1) franchise/network expansion with standardized equipment and rapid terminal deployment; and (2) differentiation via sustainability and local-market customization, including biodegradable film options and premium hygiene claims.
-
-
Recent strategic moves: Several vendors have moved from pilot to commercial roll-out of sustainable films and digitally-enabled wrapping systems. A notable case is the introduction of an automated platform that integrates bag-level NFC tracking while reducing film consumption materially — the kind of capability that compresses operating cost per bag and supports product premiumization in high-traffic terminals.
Operational levers and commercial models we analyze
-
Contract structures: Per-bag fees, revenue-share concessions, and blended fixed-plus-variable agreements each trade off risk differently between airports, vendors, and airlines. Our report models profit and cash-flow outcomes for each arrangement across occupancy and traffic scenarios.
-
Cost pass-through frameworks: We provide elasticities and practical clauses to incorporate material-price volatility and EPR fee exposures into long-term supply contracts.
-
Capex and fleet planning: For airport retailers and equipment providers, we deliver a deployment prioritization matrix that links terminal throughput, dwell time, and labor availability to equipment spec choices (manual, semi-automatic, fully automatic).
-
Sustainability transition roadmap: A decision tree and supplier-selection scorecard evaluate trade-offs between 100% recyclable films, biodegradable options, and mixed-material strategies — including life-cycle and end-of-life cost modeling under emerging EPR regimes.
Risk vectors — what to watch in 2026
-
Policy shock: Accelerated or broadened EPR laws could materially change the cost profile for operators who retain end-of-life responsibility for films. We quantify the sensitivity of unit economics to incremental per-ton fees phased in across state and international programs.
-
Input-price inflation: Elevated polymer film prices compress gross margins unless operators can lock supply or pass through costs. Hedging and strategic vendor partnerships are now part of best-practice procurement playbooks.
-
Technology adoption risk: Early movers in automatic wrapping and digital tracking gain operating leverage; late adopters risk margin erosion and concession loss. Our deployment scenarios indicate payback periods under different traffic-density assumptions.
-
Reputational/consumer risk: Sustainability claims must be verifiable. Operators who rush to biodegradable labeling without chain-of-custody evidence will face reputational penalties when airports and consumers demand proof.
What the PW Consulting report delivers (practical, actionable modules)
-
Market model and scenarios: A transparent financial model with base, upside, and downside demand curves and a stress-tested P&L for operators and equipment OEMs.
-
Supplier benchmark: Capability matrices, go-to-market approaches, and a comparative rubric that surfaces where to partner, acquire, or compete.
-
Procurement playbook: Contract templates, pass-through mechanisms, and negotiation tactics specific to airports, concession managers, and airlines.
-
Sustainability and compliance toolkit: EPR impact assessment, transition roadmap to recyclable/biodegradable films, and sample reporting templates for regulator and corporate sustainability teams.
-
M&A and partnership targets: Screening criteria and shortlists for strategic buyers seeking scale, technology, or geographic footholds — accompanied by valuation sensitivities.
-
Primary research appendix: Interview summaries with airport procurement leads, operators, and polymer suppliers, plus methodology transparency for in-market intelligence.
How leading organizations should act in 2026
-
Airports and concessionaires: Prioritize concession structures that align incentives for sustainability and throughput efficiency. Incorporate outcome-based KPIs (e.g., film consumption per bag, customer satisfaction scores) into contracts to capture upside from technology-led efficiency gains.
-
Operators and franchisees: Accelerate pilots of automatic platforms in high-density terminals and secure exclusive or semi-exclusive equipment arrangements where footfall justifies capex. Leverage digital tracking to create ancillary revenue streams (lost-luggage proof-of-service, branded protection bundles).
-
Buyers and private equity: Target assets that combine network density with demonstrable intellectual property in packaging efficiency or digital traceability. Our valuation playbook shows where multiples expand for technology-enabled operators versus purely local service providers.
-
Material suppliers and OEMs: Invest in verified recyclable or biodegradable materials and quantify end-of-life downstream costs transparently; early certification will be a competitive advantage as EPR fees mature.
PW Consulting’s Worldwide Baggage Packaging Service Market report is intentionally designed as a strategic instrument: it delivers the analytical depth required to make 2026 decisions with confidence while reserving proprietary segmentation tables and raw datasets for report subscribers. Senior executives and procurement teams who need the complete dataset, modeling workbook, and supplier scorecards are invited to access the full report on our website or contact our research desk for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Baggage Packaging Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com