

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Steady Growth: Worldwide Automotive Water Separation Systems Market Set to Expand at a 5.02% CAGR Through 2032

Worldwide Automotive Water Separation System Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Automotive Water Separation System market delivers a focused, decision-grade briefing designed to support executive choices in 2026. Grounded in an independent base-year analysis (2025) and a 2026–2032 forecast horizon, this briefing synthesizes market sizing, regulatory drivers, supply-chain stress points, and competitive moves into actionable implications for OEMs, Tier‑1 suppliers, aftermarket players and strategic investors.
Worldwide Automotive Water Separation System Market
Why this market matters in 2026
Water contamination in liquid fuels remains a mission‑critical reliability and regulatory issue for internal combustion powertrains—especially in commercial and off‑road segments where exposure to moisture and biodiesel blends is higher. Our report estimates the global market at USD 1,462 Million (base year 2025), and projects a steady recovery and expansion through the forecast period at a compound annual growth rate (CAGR) of 5.02%, reaching roughly USD 2,060 Million by 2032. This growth trajectory reflects a combination of regulatory tightening, technology refresh cycles among large fleets, and material‑led cost dynamics that will shape supplier positioning and procurement strategies in 2026.
Worldwide Automotive Water Separation System Market
Report scope — what’s inside (practical and operational)
- Market sizing and multi‑scenario forecasts (2026–2032) with sensitivity analyses reflecting regulatory and raw‑material shocks.
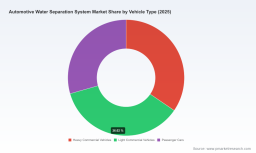
- Detailed segmentation frameworks (by region, vehicle type and component) and demand drivers — note: detailed split tables and proprietary datapacks are available in the full report.
- Regulatory and standards impact assessment (EN 590, EPA requirements, Euro legislation) and compliance roadmaps for product teams and certification managers.
- Technology trends and R&D horizon‑mapping for filter media, coalescing membranes and sensor/electronic integration, with TRL (technology readiness level) scoring.
- Supply‑chain heat‑map and raw‑material risk register (including glass microfiber and polymer membranes), plus alternative sourcing and hedging tactics.
- Competitor benchmarking, product portfolio mapping, supplier nomination case studies and likely OEM sourcing priorities.
- M&A and partnership opportunity matrix with valuation multiples and integration risk flags for strategic buyers.
- Operational playbooks for procurement, engineering and aftermarket commercial teams — from design‑to‑cost to warranty mitigation.
High‑impact takeaways for 2026 executives
- Prioritize regulatory‑constrained performance: Standards such as EN 590 and EPA testing thresholds are not static. Design and procurement teams must lock product specifications to meet or exceed mandated water‑removal efficiencies to avoid retrofits and warranty exposures.
- Mitigate raw‑material exposure now: Glass microfiber price inflation and constrained borosilicate supplies have already driven cost pressure. Sourcing teams should implement multi‑tier supplier strategies, qualify alternative media (including polymer coalescers) and negotiate indexed contracts to limit margin erosion.
- Invest selectively in sensor integration: Hybrid mechanical/electronic separators that provide real‑time water detection are moving from premium to mainstream in higher‑duty segments. Fleet operators will pay for predictive maintenance signals that reduce downtime and fuel‑system damage.
- Plan for technological bottlenecks: Coalescing polymer membranes face technical limits in achieving sub‑50 ppm water removal required for some future emissions and fuel‑quality scenarios. Roadmaps should hedge between incremental improvements and partnerships with membrane innovators.
- Address channel economics: Aftermarket and service networks represent both a revenue stream and a reputational risk. Warranty‑backed replacement programs combined with OEM approved maintenance bundles can capture recurring revenue while reducing catastrophic failure claims.
Competitive landscape — who’s shaping 2026 supplier pools
The market remains moderately consolidated with a small group of established filter and filtration systems manufacturers commanding a meaningful share of global OEM and aftermarket nominations. Key companies profiled in the report include:
Worldwide Automotive Water Separation System Market
- Donaldson Company (Bloomington, MN, USA) — advancing media science with recent Synteq XP upgrades aimed at improved efficiency on low‑sulfur fuels.
- Parker Hannifin (Racor Division, Cleveland, OH, USA) — cementing OEM relationships through strategic nominations for next‑gen truck platforms.
- Cummins Inc. (Fleetguard Division, Columbus, IN, USA) — integrating NanoNet separators with engine platforms and securing ISO‑level validations.
- Mann+Hummel and Mahle (Germany) — competing on multifunction filter assemblies for both passenger and commercial applications.
- Hengst SE, Sogefi Group, Separ Sweden, Davco Technology (Eaton) and Baldwin Filters — each defending niche strengths ranging from swirl separation technologies to heavy‑duty modular systems.
Recent competitive moves — product launches, OEM nominations and validation milestones — point to a market where OEM preference and co‑development agreements materially influence supplier selection. The report contains granular vendor scorecards and decision trees used by procurement committees when evaluating nomination rounds.
Regulation, raw materials and technology — dynamics that will decide winners
- Regulatory pressure: EN 590 and analogous standards enforce low allowable water content in diesel; U.S. EPA testing regimes require high removal efficiencies for some nonroad applications. These standards raise the bar for filter performance and can shorten product life cycles.
- Material cost shocks: 2024 saw material cost increases in key media inputs; a 15% price uptick in glass microfiber (driven by borosilicate production constraints) is indicative of recurring volatility that must be modeled into product costing and contract terms.
- Technology bottlenecks and opportunities: While coalescing elements remain core, polymer membrane technologies face challenges meeting ultra‑low water thresholds demanded by future regulations (e.g., Euro 7‑era specifications). Conversely, innovations in sensor/electronics are creating differentiation opportunities for suppliers that can deliver prognostics alongside filtration.
- Market concentration: The market exhibits moderate concentration among the top suppliers, which has implications for negotiating leverage and the speed of innovation diffusion. Our concentration analysis and CRx metrics are included in the full report.
Action checklist for 2026 — what each stakeholder should do next
- OEM product and systems engineering: Commission accelerated validation cycles for separators under expected fuel blend and contamination cases; prioritize modular designs that ease upgrades to meet tightening standards.
- Tier‑1 suppliers: Fast‑track co‑development agreements with membrane and sensor specialists; run cost‑to‑serve analyses for integrated assemblies versus component-only sales.
- Fleet operators and LCV/HCV buyers: Insist on in‑service water‑detection reporting and align warranties to demonstrable separator performance; consider retrofit campaigns where risk exposure is highest.
- Procurement: Introduce multi‑year supply agreements with pass‑through cost mechanisms and develop dual‑sourcing for high‑risk media categories.
- Private equity / strategic investors: Target bolt‑on opportunities where proprietary media or sensor IP can be combined with scale operations to improve margins and accelerate adoption in large OEM pipelines.
Risk scenarios and contingency planning
In addition to the base forecast (5.02% CAGR), the report models three scenario paths: a regulatory‑tightening scenario that accelerates adoption and raises average selling prices; a raw‑material shock scenario that compresses supplier margins and favors vertically integrated players; and a technology disruptive scenario where a membrane breakthrough displaces incumbent media. Each scenario includes trigger indicators and a recommended tactical playbook for fast response.
How PW Consulting’s analysis translates to boardroom decisions
Executives use this briefing to prioritize capital allocation, define supplier qualification criteria, and align product roadmaps with compliance timelines. The combination of bottom‑up sizing, scenario planning, supplier scorecards and a pragmatic procurement playbook provides the evidence base required to: (a) green‑light R&D investments, (b) renegotiate nominations with OEMs, and (c) execute M&A or partnership moves with a defensible valuation thesis.
Next steps — gaining access to the full intelligence
This article is a strategic preview designed to surface the analysis, implications and actionable pathways that PW Consulting delivers. It intentionally omits the full split‑level tables and proprietary datapacks (regional, vehicle‑type and component breakdowns) to preserve the commercial value of the dataset. Subscribers and clients receive the complete quantitative appendices, supplier due‑diligence files, and bespoke scenario modelling templates that are essential for executing the 2026 plays outlined above.
To obtain the full Worldwide Automotive Water Separation System Market report, detailed vendor scorecards, and an executive briefing tailored to your organisation’s role in the value chain, please contact PW Consulting or visit our research portal for subscription and advisory options.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Water Separation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com