

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Josamycin Market Poised for 4.19% CAGR from USD 185.5 Million (2025) as Asia Pacific Leads with USD 89.48 Million
By pmarketresearch, 2026-07-15
Worldwide Josamycin Market: Strategic Brief for 2026 Decision-Makers
PW Consulting’s latest market study on the worldwide Josamycin market delivers a focused, actionable intelligence package designed to support executive decision-making throughout 2026. Drawing on a verified historical window (2020–2025) with base year 2025 and a forward-looking forecast to 2032, the report combines top-down market sizing with qualitative competitive assessment, regulatory scanning, and operational playbooks. At the macro level, the market reached USD 185.5 Million in 2025 and, under our base-case assumptions, is projected to expand at a compound annual growth rate (CAGR) of 4.19% through 2032, reaching approximately USD 247.4 Million. These headline figures frame the near-term growth opportunity, while our research highlights the structural dynamics that will drive value for manufacturers, distributors, and investors in 2026 and beyond.
Worldwide Josamycin Market
Why this report matters for 2026 strategy
-
Decision-grade market sizing: The study reconciles disparate public and proprietary sources into a single, audited time series for 2020–2025 and a transparent forecasting framework for 2026–2032 — enabling scenario planning and sensitivity testing that CFOs and BD teams can operationalize.
Worldwide Josamycin Market -
Regulatory risk overlay: With Josamycin’s patchwork approval footprint — notably its continued lack of FDA approval in North America and existing classifications under global stewardship frameworks — regulatory constraints are now a primary determinant of go-to-market choices. The report maps market access constraints to realistic commercial outcomes.
Worldwide Josamycin Market -
Supply-chain stress testing: Recent policy moves and input-cost volatility (including tariffs on APIs implemented in 2025 and broad API price fluctuations) have reshaped procurement strategy. The analysis provides procurement playbooks for hedging, contract structuring, and near-shore sourcing to preserve margins.
-
Concentration and competitive posture: Industry concentration is material — our assessment shows a three-firm concentration (CR3) consistent with a market where leading players control a meaningful share of commercial supply, and a five-firm concentration (CR5) that indicates oligopolistic tendencies meriting tailored competitive strategies.
Market overview: core trends and implications
Over the historical window we analyzed, the Josamycin market has shown resilience against broad antibiotic commoditization pressures, driven by legacy formulations, regional treatment protocols, and pockets of prescriber preference. The base-year market size of USD 185.5 Million (2025) and the 4.19% forecast CAGR to 2032 underscore a moderate growth trajectory — attractive for focused investments but insufficient to justify undifferentiated capacity expansion without clear route-to-market advantages.
Three structural forces will shape 2026 outcomes:
-
Regulatory access and stewardship: Inclusion in WHO’s List of Medically Important Antimicrobials imposes stewardship obligations that influence prescribing, reimbursement, and labeling strategies. Simultaneously, the absence of FDA approval restricts North American commercialization and redirects commercial effort toward permissive jurisdictions.
-
Supply economics: API sourcing dynamics remain pivotal. Tariff regimes introduced in 2025 and ongoing API price movements from major sourcing regions have compressed margins and increased the value of supply certainty — particularly for tablet formulations that remain the largest commercial presentation by value.
-
Lifecycle signals: Localized brand actions, such as the suspension of certain reference products in parts of the EU, create tactical windows for generics and for manufacturers pursuing differentiated clinical or commercial positioning. Concurrently, new clinical activity (for example, recent real-world trials initiated in selected markets) may prompt demand spikes or repositioning in therapeutic guidelines.
Competitive landscape: profiles and strategic takeaways
Our competitive assessment separates players into API suppliers, formulators/marketers, and integrated manufacturers — each class presenting distinct strategic opportunities and risks.
-
API suppliers: Companies with established GMP-certified APIs and consistent global listings — including Japan-headquartered producers and multiple Chinese manufacturers — dominate the upstream landscape. Their value propositions are built on regulatory compliance, reliable batch quality, and logistical reach. For buyers, emphasis should be placed on multi-source qualification, long-term off-take agreements with price-adjustment clauses, and on-site or virtual audit capabilities to mitigate tariff- and inspection-related disruptions.
-
Originator and marketer incumbents: Legacy brands and originator firms maintain strategic leverage via brand recognition, formulation know-how, and regulatory dossiers in key markets. These players can defend pricing in protected markets but are vulnerable in jurisdictions where reference products are suspended or where generics can rapidly scale.
-
Regional formulators and generic houses: Several regional manufacturers and generics houses have tactical advantages in cost and local market knowledge. They are often first to exploit regulatory vacuums created by reference suspensions or supply shocks. For multinational firms, partnership or licensing with these regional players can accelerate entry while spreading regulatory and commercial risk.
Notable market actors analyzed in the report include established API producers with Japanese and Chinese manufacturing footprints, European generics houses active in specific markets, and Chinese formulators with domestic market presence. Each profile includes an assessment of manufacturing credentials, regulatory posture, historical product positioning, and practical implications for partnership or M&A screening.
Regulatory and clinical developments to watch in 2026
-
FDA status: Continued absence of FDA approval will keep North America a complex and limited opportunity — but it also protects price levels in markets where Josamycin remains an approved option.
-
Stewardship obligations: WHO classification requires companies to build stewardship programs into commercial launches and tender responses; payers increasingly demand antimicrobial stewardship commitments as part of procurement.
-
Clinical activity: The initiation of real-world trials and other clinical research in select markets serves as both a demand indicator and a data-generation opportunity. Sponsors should evaluate how trial results could alter treatment algorithms and reimbursement in targeted geographies.
Actionable recommendations for 2026
-
Secure supply and cost predictability: Prioritize multi-sourced API contracts with staggered delivery profiles, incorporate tariff-pass-through triggers, and lock in quality audits to avoid production interruptions.
-
Pursue market access where regulatory windows exist: Redirect commercial resources toward regions with established approval or where regulatory pathways are accessible, while maintaining a watchful register on evolving clinical evidence that could open new territories.
-
Explore targeted partnerships: For firms without local regulatory expertise, selective licensing or distribution partnerships with regional formulators can accelerate revenue with limited capital outlay.
-
Embed stewardship into commercialization: Design marketing, post-marketing surveillance, and formulary submissions around antimicrobial stewardship to pre-empt payer pushback and to satisfy procurement tender criteria.
-
Prepare for scenario volatility: Use the report’s scenario module to stress-test profitability under variations in API pricing, tariff regimes, and regulatory shifts — and align capex and inventory decisions to the most probable scenarios.
What the full report delivers (practical components)
PW Consulting’s full report is a practical toolkit, not just an overview. Clients receive:
-
Comprehensive market model: Time-series demand and revenue model (2020–2025 historical, 2026–2032 forecast) delivered in editable format to run custom scenarios using your input assumptions.
-
Competitive intelligence dossiers: Detailed profiles, production footprints, regulatory dossiers, and supplier-risk scores for the key upstream and downstream players in the Josamycin ecosystem.
-
Supply-chain heatmaps: Source-risk assessments, tariff exposure matrices, and procurement playbooks to reduce production and margin volatility.
-
Regulatory tracker and impact assessment: Jurisdiction-by-jurisdiction summary of approval status, stewardship implications, and practical steps for dossier submission or lifecycle management.
-
Go-to-market templates: Tender response frameworks, pricing models, and JV/licensing term sheets designed for rapid execution.
Consistent with the “trailer” approach of this release, we have intentionally showcased analytical direction and strategic conclusions while reserving the granular segmentation tables, per-region/per-application breakdowns, and downloadable models for the full report. These withheld datasets are the core intelligence assets that accelerate execution for commercial teams, procurement heads, and corporate strategy groups.
Closing: where this fits into 2026 corporate priorities
For pharmaceutical manufacturers, distributors, and investors evaluating mid-cycle allocations in 2026, Josamycin represents a niche but stable market with pockets of upside linked to regulatory shifts, clinical trial outcomes, and supply disruptions. The modest-but-steady growth trajectory — underpinned by a 4.19% CAGR to 2032 and corroborated by our 2025 base-year audit — supports targeted investments that emphasize supply security, market access nuance, and stewardship alignment. Companies that align contracting, regulatory strategy, and clinical evidence generation will capture disproportionate value relative to those relying on commodity playbooks.
To access the full dataset, regional and application-level segmentation, and the executable playbooks referenced above, visit the PW Consulting report page for the Worldwide Josamycin Market. Our analysts stand ready to deliver tailored briefings and to run bespoke scenario simulations that map your opportunity set to operational realities in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Josamycin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide GMP Protein (E. coli) Contract Manufacturing Market to Expand from USD 1,585.4 Million in 2025 to USD 3,396.75 Million by 2032 at an 11.45% CAGR
By pmarketresearch, 2026-07-15
Worldwide GMP Protein (E. coli) Contract Manufacturing Market — Strategic Preview for 2026 Decision-Makers
As biomanufacturing leaders recalibrate supply chains and product roadmaps for the post‑pandemic era, understanding the trajectory of GMP contract manufacturing for E. coli‑expressed proteins is essential. PW Consulting’s latest market research — anchored on a 2025 base, a historical window that spans 2020–2025, and a forecast horizon covering 2026–2032 — shows clear, actionable signals for commercial planners, R&D chiefs, and corporate development teams. The market in focus reached USD 1,585.4 Million in 2025 and is projected to grow to USD 3,396.75 Million by 2032, representing a compounded annual growth rate (CAGR) of 11.45% through the forecast period. This growth, and the structural forces behind it, should shape capital allocation and outsourcing strategies into 2026 and beyond.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market
Why the E. coli GMP protein CDMO market matters in 2026
-
Cost and speed advantages. E. coli platforms continue to offer a compelling combination of rapid strain development, high volumetric productivity and relatively lean facility footprints compared with mammalian systems. These attributes make microbial manufacturing the default choice for certain therapeutic classes and many research‑to‑clinic programs where time and cost are primary constraints.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market -
Expanding product set. The market expansion is driven by a diverse set of protein classes — from enzymes and cytokines to antibody fragments and recombinant vaccines — creating a multi‑modal demand profile that CDMOs must service with flexible process toolboxes and regulatory readiness.
Worldwide GMP Protein (E. coli) Contract Manufacturing Market -
Regulatory tightening raises quality and analytics stakes. Recent guidance from regulators emphasizes enhanced characterization and control of host cell proteins (HCP) and residual host DNA in E. coli‑derived products. Expect increased demand for orthogonal assays, platform‑specific HCP panels (per USP <1132> and FDA guidance), and deeper lot‑release analytics to meet FDA, EMA and ICH expectations.
-
Mid‑market consolidation and capability densification. The market’s competitive footprint shows material share concentration across leading global CDMOs, while a broad mid‑tier of specialist providers continues to compete on niche capabilities such as ultra‑low endotoxin processing, inclusion body refolding, or pDNA co‑manufacturing. This structure creates optionality for buyers but also raises M&A interest among scale players seeking capability filling and geographic reach.
What PW Consulting’s report delivers — practical content that matters to executives
-
Strategic playbook: decision frameworks that translate market growth signals and regulatory changes into operational moves (e.g., when to insource versus partner, and the minimum analytics footprint required for clinical versus commercial programs).
-
Provider scorecards: a repeatable vendor evaluation template that weights technical capabilities, regulatory track record, capacity elasticity, and commercial terms — ready to deploy for RFP shortlisting and supplier risk assessments.
-
Techno‑economic models: build‑to‑buy calculators and scenario analyses that quantify the cost and timeline implications of key choices (fermentation scale, DSP approach, endotoxin and HCP control strategies) without exposing confidential client inputs.
-
Regulatory checklists and analytical roadmaps: a set of step‑by‑step controls and recommended orthogonal assay suites to meet USP/ICH/EMA expectations for E. coli‑derived products.
-
Capacity and supply maps: an interactive view of global GMP capacity trends and strategic hubs (note: detailed regional and application splits are available in the full report).
-
M&A and partnership playbook: criteria for bolt‑on acquisitions, co‑development partnerships, and licensing agreements that accelerate pDNA/ protein co‑manufacturing or secure platform technologies.
Competitive landscape — reading the vendor map in 2026
The vendor landscape is multifaceted: global scale players, specialty microbial CDMOs, and regional mid‑market providers each play distinct roles in the value chain. Our analysis of leading providers identifies three strategic positioning archetypes that buyers should consider when selecting partners.
-
Global integrators with breadth: Firms such as Lonza and AGC Biologics offer integrated service suites and global footprint advantages — useful for sponsors seeking single‑partner solutions spanning development through commercial supply. These providers often win on risk reduction, regulatory history, and the ability to absorb scale‑up complexity across sites.
-
Technology specialists: Companies like Wacker Biotech and MicroProtein Technologies (MPT) differentiate on proprietary secretion or refolding platforms and on expertise with challenging inclusion body projects. Sponsors with molecules that require unusual downstream processing or specialized refolding strategies should prioritize such specialists early in candidate selection.
-
Regional and niche providers: A cohort including Bionova Scientific, HIPRA Biotech Services, 53Biologics, Elise Biopharma, Richter BioLogics, Biovian (3PBIOVIAN), List Labs and Xpress Biologics (Polyplus/Sartorius) combine regulatory compliance with cost‑competitive, agile services. Strategic actions among these providers — for example, Bionova’s recent licensing partnership for high‑efficiency pDNA production (Feb 2026) and HIPRA’s expanded E. coli capability set (Jan 2025) — indicate continued specialization and selective capability buildouts.
Notably, the market exhibits moderate concentration: the top three providers account for a material share of spend while the top five capture just over half of the market. That structure favours both risk‑averse consolidation plays by large sponsors and opportunistic growth for skilled mid‑tier CDMOs that can demonstrate regulatory compliance and technical differentiation.
Regulatory and operational imperatives that will shape sourcing decisions
-
Analytics infrastructure is non‑negotiable. The combination of FDA guidance on HCP characterization, ICH Q6B expectations and EMA practice means sponsors and CDMOs must invest in orthogonal assay capability and platform‑specific HCP panels during late preclinical and early clinical stages.
-
Process robustness reduces lifecycle costs. Investments in host cell engineering, secretion systems, and refolding technologies lower downstream burden and reduce lot failures; the return on investment is particularly clear where commercial demand and high yields drive volume economics.
-
Workforce and quality systems are enduring differentiators. Large‑scale E. coli manufacturing requires highly trained personnel and mature QMS to pass regulatory scrutiny; these are harder to build than cleanroom capacity and are often the gating factor in vendor selection.
-
Dual sourcing and geographic flexibility mitigate geopolitical and supply risks. Given the pace of market growth and localized regulatory enforcement, having a primary and a qualified secondary CDMO — ideally in complementary regulatory jurisdictions — is prudent for late‑stage programs.
Actionable recommendations for 2026
-
Prioritize analytics before scale. Build or partner for orthogonal HCP and residual DNA testing early in late discovery to avoid costly process rework.
-
Match vendor archetype to program risk. Use global integrators for complex, global launches; choose specialists for technically demanding molecules; leverage regional players for cost‑sensitive, early‑phase projects that require agility.
-
Negotiate flexibility into CDMO contracts. Include options for scale steps, capacity hold, and technology transfer timelines to adapt as programs progress to pivotal and commercial stages.
-
Invest in platform technologies selectively. For sponsors with pipeline breadth in enzyme, cytokine, or antibody fragment spaces, platform investments in secretion or refolding technologies can yield multi‑product upside.
-
Model capacity at scenario level. Use forward scenarios tied to the market’s expected growth to 2032 (from USD 1,585.4 Million in 2025 to USD 3,396.75 Million in 2032 at an 11.45% CAGR) to decide timing and scale of CAPEX or partner commitments.
How PW Consulting supports executive decisions
We translate market data into executable plans. Our engagements commonly include: bespoke vendor diligence and scorecards; CAPEX/OPEX and cost‑of‑goods modeling for build versus buy; regulatory readiness audits with prioritized remediation roadmaps; and M&A advisory focused on capability fills and geographic expansion. For sponsors considering partnership or capacity investments in 2026, PW Consulting provides hands‑on support from RFP through tech transfer.
This preview intentionally highlights strategic trends and the practical content of our analysis while withholding granular segment‑level tables and vendor share breakdowns that are part of the full report. Those detailed splits and downloadable templates are available on the PW Consulting report page for organizations that require the complete dataset and reproducible models to inform procurement, manufacturing and M&A decisions.
For detailed analysis of this topic, please visit the official page: Worldwide GMP Protein (E. coli) Contract Manufacturing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Multi‑Gigabit Switches Market to Grow from USD 7,280 Million in 2025 at 18.52% CAGR, Reaching USD 23,915.12 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Multi-Gigabit Switches Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market research — the Worldwide Multi-Gigabit Switches Market report — provides a forward-looking playbook designed to inform high-stakes infrastructure and sourcing decisions in 2026. Built on a 2025 base and a 2026–2032 forecast horizon, the study models demand across enterprise, edge, and data center environments and quantifies a clear growth runway: the market rises from USD 7,280.0 Million in 2025 to an anticipated USD 23,915.12 Million by 2032, reflecting a compound annual growth rate (CAGR) of 18.52%. This preview highlights the report’s strategic value without publishing the granular segment-level datapoints reserved for subscribers.
Worldwide Multi-Gigabit Switches Market
Why 2026 is an inflection year for multi-gigabit networking
-
Converging technology trends are accelerating multi-gig adoption. Wi‑Fi 7, higher-power PoE++ for AI-driven surveillance and access points, and persistent demand for low-latency uplinks in hybrid work models are moving organizations away from legacy 1GbE boundaries.
Worldwide Multi-Gigabit Switches Market -
Infrastructure economics are shifting. Data center shell-and-core construction costs are edging higher, and electricity is a dominant portion of operating expense; these dynamics force buyers to weigh CAPEX upgrades against long-term OPEX implications when choosing switch platforms and architectures.
Worldwide Multi-Gigabit Switches Market -
Supply-chain and regulatory volatility matter. Raw-material and fiber deployment cost outlooks indicate renewed pressure on rollout economics in 2026, while recent changes in U.S. net neutrality policy create asymmetric opportunities and risks for service providers and large enterprise networking buyers.
High-level findings every CIO and VP of Infrastructure should bookmark
-
Market trajectory: Robust expansion through 2032 — the multi-gigabit switches market is on a sustained growth path that will reshape refresh cycles, vendor roadmaps, and procurement cadence.
-
Concentration and competitive posture: Market concentration metrics show the top three and five vendors account for a majority share, signaling both entrenched incumbency and meaningful opportunities for specialist and regional players to capture niche use cases.
-
Product mix is shifting: Buyers are increasingly prioritizing multi-speed flexibility, integrated PoE power budgets for AI/IoT endpoints, and uplink bandwidth options that align with edge-to-cloud topologies.
-
Cost of ownership is the new battleground: Energy consumption, cooling, and lifecycle modularity (upgradability of optics and line cards) are as decisive in vendor selection as raw per-port pricing.
Competitive landscape — capabilities and strategic implications
-
Cisco Systems — Enterprise-grade breadth and long-term platform roadmaps make it the default choice for large campus and blended campus/datacenter deployments. Strategy for buyers: leverage Cisco’s ecosystem for integration benefits, but pressure vendors on modular upgrade economics and advanced telemetry licensing.
-
Arista Networks — Strength in high-performance 10G+ switching for cloud and hyperscale environments positions Arista as a primary option for spine/leaf and performance-sensitive fabrics. Strategy: evaluate Arista where low-latency and programmability justify premium pricing.
-
Juniper Networks — A balanced play across carrier and enterprise verticals with routing/switching integration advantages. Strategy: consider Juniper for unified control-plane scenarios and where MPLS/segment-routing interoperability is required.
-
Hewlett Packard Enterprise (Aruba) — Strong campus orientation with Aruba CX series emphasizes manageability and wireless-wireline convergence; attractive for organizations prioritizing a single-vendor experience for wireless and wired infrastructure.
-
Ubiquiti, NETGEAR, TP‑Link, QNAP, D‑Link — These vendors drive price-performance at the SMB/prosumer and edge tiers. Recent product rollouts from QNAP and D‑Link illustrate how lower-cost 2.5G/5G/10G options are blurring the lines of capability between consumer-grade and commercial switches. Strategy: use these suppliers for rapid, low-cost edge refreshes but validate management and lifecycle support for larger rollouts.
-
Specialists and industrial vendors (TRENDnet, Omnitron, Lantronix, PLANET, Zyxel, EnGenius) — Focused portfolios deliver hardened designs, extended temperature ranges, and higher PoE budgets for industrial, surveillance, and transportation deployments. EnGenius’s 2025 launch of a Layer 2+ multi-gig PoE++ product illustrates the intersection of Wi‑Fi 7 readiness and AI surveillance requirements.
Recent market activity that matters to procurement calendars
-
Product introductions targeting Wi‑Fi 7 and PoE++ workloads have proliferated among both mainstream and specialist suppliers — expect refreshed product lines and aggressive mid-cycle pricing through 2026.
-
Vendors are increasingly segmenting firmware and management features into tiered offerings; buyers should map feature entitlements to multi-year TCO rather than initial sticker price.
What the PW Consulting report gives you — practical, actionable deliverables
-
Decision frameworks and procurement playbooks: A step-by-step buyer’s guide for vendor shortlisting, RFP construction, PoE power budgeting, port-speed planning, and migration windows optimized for 2026 capital cycles.
-
Dynamic TCO models: Configurable templates that incorporate CAPEX, energy/OPEX, cooling impacts, and optics refresh schedules so you can stress-test scenarios under different electricity cost and data center build-cost assumptions.
-
Vendor benchmarking and negotiation cushions: Comparative profiles and negotiation levers aligned with feature sets, warranty terms, and lifecycle upgrade paths — designed to reduce procurement friction and manage total lifecycle spend.
-
Risk and compliance register: Practical mitigations for raw-material inflation, fiber deployment cost spikes, and regulatory shifts affecting service providers and large enterprise buyers.
-
Use-case playbooks: Ready-to-execute architectures for campus Wi‑Fi 7 rollouts, AI surveillance and PoE++ deployments, SMB edge refreshes, and spine-leaf data center designs — each with configuration checklists and staging considerations.
Deployment scenarios — how to translate the forecast into rollout decisions
-
Campus and Enterprise: Prioritize modular switches that scale uplink capacity without full-chassis replacement; map PoE budgets to anticipated AI/IoT growth rather than current device counts.
-
Edge and SMB: Favor low-cost multi-gig variants with simplified management for rapid deployment, but include a support-path clause in procurement to preserve future scalability.
-
Data Center: For spine/leaf fabrics, ensure vendor roadmaps accommodate 10G+ uplink aggregation and optics standardization to avoid stranded investments as traffic profiles evolve.
-
Industrial/OT: Validate hardware-level robustness and PoE temperature derating. Specialist providers offer hardened options that justify premium in non-office environments.
Decision framework for executives in 2026 — five immediate actions
-
Run a demand heatmap: Identify which business units will require increased uplink or PoE capacity in the next 12–24 months and align procurement cycles accordingly.
-
Incorporate energy sensitivity into vendor evaluations: Use the report’s TCO templates to simulate electricity-driven OPEX scenarios given current industry data on data center power spending.
-
Negotiate modular options and trade-in paths: Secure contractual language that reduces refresh risk and clarifies optics/line-card upgrade pricing.
-
Assess regulatory exposure: For service providers and large campus operators, model business-impact scenarios stemming from recent regulatory shifts.
-
Plan staged rollouts to capture price declines: Use pilot deployments to validate vendor claims and reserve budget for accelerated deployments if fiber and equipment costs stabilize.
Why PW Consulting’s report is indispensable for 2026 strategy
This report combines a robust historical base (2020–2025), a clearly stated base year (2025), and a granular forecast period (2026–2032) with proprietary demand models, vendor scorecards, and scenario stress-testing tools. It synthesizes market sizing, competitive concentration metrics, and forward-looking trend analysis into operational guidance for CIOs, procurement leads, and infrastructure architects. While this preview summarizes the strategic implications, the full report contains the detailed segment-level intelligence, vendor scorecards, downloadable TCO models, and executable RFP language that teams need to move from planning to procurement.
Next steps
For organizations preparing capital and operational plans in 2026, the right time to act is now: align budgets to anticipated growth vectors, stress-test energy and build-cost sensitivity assumptions, and engage vendors with a clear roadmap for modular upgrades. PW Consulting’s full Worldwide Multi‑Gigabit Switches Market report delivers the datasets, scenario models, and commercial playbooks that translate forecasted market momentum into defensible sourcing decisions. Access the full report to obtain the granular segmentation, vendor worksheets, and downloadable tools referenced in this preview.
For detailed analysis of this topic, please visit the official page: Worldwide Multi-Gigabit Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ammonium Polyvanadate Market Poised to Expand at an 8.9% CAGR, New Report Reveals
By pmarketresearch, 2026-07-15
Worldwide Ammonium Polyvanadate (APV) Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
As the ammonium polyvanadate (APV) market transitions from cyclical raw-material dynamics to structurally higher demand, corporate leaders must recalibrate supply, product, and investment strategies for 2026 and beyond. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — projects the global APV market to grow from an estimated USD 455.12 Million in 2025 to USD 826.67 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.9% over the forecast period. Short-term momentum is already visible with the market expected to approach roughly USD 494 Million in 2026.
Worldwide Ammonium Polyvanadate (APV) Market
Why this matters for 2026 decision-makers
- Timing of capital deployment: With an accelerating CAGR, investment windows for capacity upgrades, purification technology, and backward integration will tighten. Executives need to prioritize near-term projects that unlock optionality—scalable modules, variable-cost furnaces, and partnerships that can be ramped quickly.
- Supply security and strategic sourcing: The APV value chain is tightly linked to the geography and politics of primary vanadium feedstocks. Raw material concentration and geopolitical shifts are creating new supply risks and price volatility that directly affect APV producers and their buyers.
- Product and market segmentation: End-market demand drivers are evolving (steel alloys vs. chemical catalysts vs. energy storage). Successful players will pair product-grade strategies (technical vs. high-purity positioning) with end-customer routes-to-market rather than treating all APV as a commodity.
Macroeconomic and raw-material context shaping the market
Three structural realities define the near-term landscape. First, global vanadium production remains concentrated — recent authoritative sources estimate global contained vanadium output around 100,000 metric tons in 2023, with China accounting for a dominant share. Second, geopolitical developments have reduced output from certain producers, introducing regional disruption risks. Third, policymakers are treating vanadium as strategic: the European Union’s inclusion of vanadium on its Critical Raw Materials list is a clear signal that regulatory and subsidy frameworks will increasingly influence where and how APV-related investments are made.
Worldwide Ammonium Polyvanadate (APV) Market
For APV stakeholders, these realities translate into actionable risk vectors: feedstock provenance, trade and tariff exposure, and regulatory compliance complexity. Companies that align procurement, processing location choices, and customer contracts with these vectors will be better positioned to stabilize margins and capture growth.
Worldwide Ammonium Polyvanadate (APV) Market
Market dynamics and demand drivers
- Steel and ferroalloys remain the anchor demand pool, underpinning baseline APV volumes and pricing coherence.
- Catalysts and chemical-grade applications continue to support a premium band in the value chain, tightening requirements around impurity profiles and certification.
- Energy storage — notably vanadium redox flow batteries (VRFBs) — presents asymmetric upside. While still at an earlier adoption stage relative to traditional uses, the storage segment’s growth path acts as a strategic lever for producers that can supply high-purity APV at scale.
PW Consulting’s model combines historical production and end-market adoption curves with scenario overlays for VRFB roll-out, steel demand elasticity, and regulatory shifts. The result is a robust base-case outlook and two alternative scenarios that quantify upside from accelerated battery deployment and downside from tightened raw-material bottlenecks.
Competitive landscape — what incumbents are doing
The APV market exhibits moderate concentration: the combined share of the top three firms is substantial but not dominant, and the top five firms hold a meaningful majority of market share. That structure creates both defensive advantages for incumbent producers and entry opportunities for well-capitalized challengers or specialized niche players.
- EVRAZ plc (Moscow) : A vertically integrated vanadium producer with established APV output tied to ferrovanadium and steel applications. Strengths include captive feedstock and downstream integration, which underpin resilience to spot feedstock swings. Watch for export/production adjustments in response to ongoing sanctions dynamics.
- Panzhihua Iron and Steel Group Vanadium Titanium New Material Technology (Panzhihua, China) : Integrated sourcing from vanadium-titanium magnetite gives this group cost and scale advantages. Their strategy emphasizes large-scale V2O5 and ferrovanadium throughput, with APV positioned as a key intermediate. Expect continued focus on process efficiency and domestic supply security.
- Chengde Xinhua Hebei Vanadium Products (Chengde, China) : Specializes in APV from slag streams, catering to chemical and metallurgical markets. Their niche in slag-derived APV creates flexibility in feedstock choice and downstream customization.
- Hebei Jianlong Vanadium Products (Qian'an, China) : Focused on producing APV as an intermediate for high-purity V2O5. Technical capabilities in purification make Jianlong relevant to battery and catalyst supply chains that demand tighter specifications.
- Treibacher Industrie AG (Althofen, Austria) : European supplier of commercial-grade APV to catalysts and specialty chemicals. Their footprint and product breadth make them an attractive partner for customers seeking stable European-origin supply amid wider geopolitical uncertainty.
Collectively, these firms illustrate three strategic playbooks: (1) vertical integration and feedstock control, (2) specialization into higher-margin, high-purity streams, and (3) geographic differentiation to serve regionally sensitive customers. For 2026, the interplay among these approaches will determine who captures incremental volume and margin.
Actionable insights and recommended moves for 2026
- Prioritize flexible, staged capacity investments: Favor modular expansions and retrofits that can switch between technical and high-purity product streams with limited downtime.
- Lockfeedstocks with blended sourcing strategies: Combine long-term offtakes, strategic stocks, and toll-processing partnerships to smooth feedstock cost volatility.
- Differentiate through quality and service, not just price: Buyers of APV will increasingly pay a premium for certified high-purity material and traceable provenance, especially in energy storage and specialty chemicals segments.
- Use the procurement calendar to hedge geopolitics: With production shifts and trade policy risks, aligning procurement and sales contracts to regional policy signals will reduce exposure to sudden supply shocks.
- Consider M&A or JV plays selectively: Targets with access to non-China feedstocks, or with proven high-purity purification technology, should be prioritized for inorganic growth.
What the PW Consulting report delivers (practical, executable content)
This report is deliberately structured for commercial utility. Key deliverables include:
- Validated global APV market sizing and a seven-year forecast (2026–2032) with scenario sensitivity to battery adoption, steel demand shifts, and raw-material disruptions.
- Cost-to-serve models and price-band matrices for technical vs. high-purity product streams, enabling unit-economics analysis for greenfield and brownfield investments.
- Supply-chain risk heatmaps, including feedstock exposure by supply route, logistics chokepoints, and regulatory risk overlays tied to critical-raw-material policy changes.
- Competitive benchmarking: capacity maps, technology gap analysis, and M&A candidate screening criteria tailored for both strategic and financial acquirers.
- Commercial playbooks for producers and buyers: contracting templates, hedging approaches, and go-to-market segmentation that link product specification to buyer willingness-to-pay.
- Operational diagnostic tools: an APV plant readiness checklist, capex prioritization matrix, and process control improvement levers to lift yield and reduce impurity-related downgrades.
To respect client confidentiality and maintain competitive value, the report previews high-level trends and supplier strategies in this public release while reserving detailed subsegment numbers, region-by-region allocations, and company-level production volumes for the full report and data packs.
How to use this intelligence in 2026 planning cycles
For CEOs and line managers planning 2026 budgets, the report offers three immediate use-cases:
- Capex prioritization: Rank near-term projects by NPV under the PW Consulting base and upside scenarios, and fast-track those with shorter payback and higher optionality.
- Procurement redesign: Shift from spot buying to blended sourcing contracts with volume-flex options and supplier scorecards tied to traceability and regulatory compliance.
- Commercial strategy refresh: Re-segment customer accounts by value (not just volume) to align premium product availability with buyers willing to pay for higher purity and guaranteed provenance.
Conclusion — the strategic window is now
APV is no longer a back-office intermediated input; it is a strategic pivot point in several supply chains — from ferroalloys to catalysts to grid-scale energy storage. The market’s projected expansion from an estimated USD 455.12 Million in 2025 to USD 826.67 Million by 2032 at an 8.9% CAGR creates a narrow window for value capture. Firms that align feedstock sourcing, product differentiation, and capacity flexibility will secure outsized returns in 2026 and beyond.
PW Consulting’s full Worldwide Ammonium Polyvanadate (APV) Market report contains the granular segmentations, regional allocations, and executable financial models that corporate leaders will need to convert this strategic preview into operational advantage. For those ready to move from insight to action, the full dataset and advisory options are available through our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial‑Grade Borated Polyethylene Market Set to Expand at a 5.18% CAGR Through 2032
By pmarketresearch, 2026-07-15
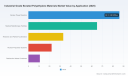
Industrial Grade Borated Polyethylene Materials Market: Strategic Imperatives for 2026
Executive summary
PW Consulting’s latest market intelligence on industrial grade borated polyethylene (BPE) delivers a focused strategic playbook for executives making near-term and medium-term decisions in 2026. Built from primary interviews, plant-level supply chain mapping, patent landscaping and proprietary financial modelling, the report quantifies the market’s current footprint and projects a clear growth trajectory: the industry base reaches roughly USD 217 million in 2025 and is forecast to expand to just over USD 309 million by 2032, implying a compound annual growth rate of approximately 5.18% across the 2026–2032 forecast window.
Industrial Grade Borated Polyethylene Materials Market
Why this matters for 2026 decision-makers
-
Capital allocation: With predictable, mid-single-digit CAGR, BPE is transitioning from a niche safety commodity to a portfolio-level component in energy, medical and defense asset plans. CFOs and strategy leads must now weigh steady organic growth against options for targeted capacity investments or bolt-on acquisitions.
Industrial Grade Borated Polyethylene Materials Market -
Supply chain resilience: Lead times and certification requirements increasingly differentiate suppliers. Procurement teams need an evidence-based sourcing matrix rather than ad-hoc vendor selection to avoid schedule slippage on nuclear and medical projects.
Industrial Grade Borated Polyethylene Materials Market -
Regulatory and technical risk: Compliance with military and nuclear specifications and the long service-life expectations of spent-fuel and reactor applications create unique product qualification burdens. Engineering and quality heads must plan multiyear validation programs now to be procurement-ready for projects coming online in the late 2020s.
Market dynamics driving 2026 choices
Demand is being shaped by three durable vectors: the continued renewal and expansion of civilian nuclear capacity in several markets; steady growth in medical radiotherapy infrastructure; and ongoing investments in research facilities and defense platforms that require certified neutron shielding. These drivers interact with supply-side realities—manufacturing capacity, certification lead times, and the availability of boron-loaded feedstocks—to determine who wins competitive opportunities.
Regulatory frameworks and military specifications remain a gating factor. Our analysis highlights the practical implications of long-standing standards that govern material composition and aging allowances for spent-fuel and naval applications. For procurement and engineering teams this means qualification timelines can be measured in quarters, not weeks—impacting vendor selection, contract terms and contingency planning.
Segmentation and product evolution (what we analyze, not what we disclose)
The report dissects the market across product formulations, boron loading bands, and application end-markets, and it tracks price and performance trade-offs between low-, mid- and high-loading variants. We do not publish the complete breakdown in this executive summary – the enclosed analysis in the full report preserves granular split data – but our findings emphasize a clear trend: customers increasingly demand higher functional density (more boron per unit volume) where mass and footprint matter, while cost-sensitive applications continue to favor standard loading grades with optimized manufacturing tolerances.
From a materials perspective, manufacturers are investing in process controls and secondary operations (CNC, waterjet cutting, custom fabrication) to expand addressable use-cases. For manufacturers and OEMs, the choice is between expanding fabrication capabilities to capture margin or outsourcing value-added work to regional partners for speed to market.
Competitive landscape — who to watch and why
The BPE supply base blends legacy specialty plastics producers, regional fabricators, and a growing pool of lower-cost suppliers. Our competitive review focuses on strategic positioning rather than raw sales figures, identifying the capabilities that matter most in 2026:
-
Proprietary processing and dimensional control. Firms that own specialized sheet extrusion or flattening processes provide differentiating product consistency for critical shielding panels—an important selling point in medical vault and reactor applications.
-
Certification and quality systems. Manufacturers registered to military and aerospace specifications and to ITAR/ASTM regimes shorten procurement cycles for defense and nuclear customers and justify premium pricing.
-
Customization and downstream services. Suppliers offering extensive CNC/waterjet cutting, custom blocking, and in-house fabrication capture additional value and reduce integration risk for installers and EPC firms.
-
Geographic and logistical reach. Regional stocking and quick-ship capabilities matter for time-sensitive retrofits and site fit-outs.
Illustrative vendor profiles in the report highlight how market participants are leveraging these capabilities. Some firms emphasize proprietary processing and flatness control to serve high-spec industrial customers; others compete on breadth of boron-loading options and aggressive lead times. Recent market activity—trade show visibility by marquee producers and strategic partnerships with national nuclear programs—reinforces a maturing commercial ecosystem where reputation, certification and service depth shape win rates.
Supply, pricing and margin dynamics
Raw-material cost sensitivity and the unit economics of higher-loading formulations drive product-level margin dispersion. Manufacturers with vertically integrated compounding or tight supplier agreements for boron additives maintain better gross margins when market prices spike. At the same time, buyers increasingly demand supplier-level transparency on aging performance and hydrogen density characteristics for long-life installations—creating an opportunity for suppliers that can demonstrate robust testing and lifecycle assurances.
Risk, regulation and compliance checklist for 2026
-
Material specifications: Close adherence to established military and nuclear material specifications is non-negotiable for many end markets. Expect procurement to require documented testing and traceability as part of standard RFPs.
-
Qualification lead times: Allow for extended validation timelines, especially when switching suppliers or introducing new boron loadings on certified projects.
-
Geopolitical and trade exposure: Sourcing strategies should model supply interruptions and potential tariff or export-control impacts across manufacturing nodes.
-
Lifecycle performance: Design safety margins and maintenance plans must account for conservative hydrogen-density de-ratings applied by regulators to account for aging.
Actionable guidance and tools included in the report
PW Consulting delivers pragmatic, decision-grade instruments tailored for 2026 execution:
-
Interactive financial model: Sensitivity-tested cash flow scenarios across capacity expansion, price compression and raw-material volatility.
-
Supplier selection matrix: A weighted evaluation framework that maps performance, certifications, lead times and after-sales capabilities to buyer priorities.
-
Go-to-market playbooks: Segmented strategies for suppliers targeting nuclear, medical and defense channels, including recommended commercial terms and partnership structures.
-
M&A and partnership shortlist methodology: A reproducible approach to identifying targets or JV partners that close capability gaps while preserving certification continuity.
-
Risk heat map: A triaged view of operational, regulatory and market risks with mitigation options and contingency triggers.
Implications for key stakeholders
-
Corporate Strategy: The market’s established growth profile makes BPE a defendable area for strategic focus. Decisions in 2026 should prioritize deals and investments that shorten customer qualification cycles and expand fabrication services.
-
Procurement: Implement the supplier selection matrix to balance cost, certification time and continuity risk. Prioritize dual-sourcing for mission-critical projects.
-
R&D and Engineering: Invest in accelerated qualification protocols for higher-loading materials and composite laminates that meet both neutron attenuation and longevity requirements.
-
Investors: Expect stable volumetric growth with pockets of premium margin for certified, service-rich suppliers. Private equity and strategic buyers should look for differentiated service models and certification-led barriers to entry.
What the full report provides (and why you’ll want it)
The complete PW Consulting report extends the preview above into a comprehensive suite of intelligence: detailed market sizing and verified time-series demand, scenario-based forecasts, supplier benchmarking, a complete regulatory compliance matrix, price index analysis and a downloadable financial model. To preserve competitive value for clients and to adhere to our “trailer” approach, we intentionally withhold certain granular segmentation tables and vendor share breakouts from this press release. These are available in the full report where subscribers can also access raw data and our underlying assumptions.
Next steps
For strategy teams preparing budgets and procurement pipelines in 2026, now is the time to validate assumptions, test alternative sourcing scenarios, and align certification roadmaps with project timelines. PW Consulting is offering limited advisory slots to translate this market intelligence into a tailored sourcing or M&A plan that fits your organization’s risk appetite and growth objectives.
To access the full report, download the data workbook, or schedule a briefing with our senior industry analysts, please visit the PW Consulting report page or contact our research desk for a confidential discussion.
For detailed analysis of this topic, please visit the official page: Industrial Grade Borated Polyethylene Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fire and Gas Detection Systems Market Forecast to Hit USD 11,654.91 Million by 2032, Growing at a 6.5% CAGR
By pmarketresearch, 2026-07-15
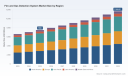
Worldwide Fire and Gas Detection System Market — Strategic Briefing for 2026 Decisions
As organizations across energy, industrial, and commercial sectors reassess risk, continuity, and capital allocation for 2026, the fire and gas detection market stands out as a critical, steadily expanding category of industrial safety spend. Our new PW Consulting report, based on a 2025 baseline and a detailed 2020–2025 historical reconstruction, projects the global fire and gas detection systems market to continue growing at a compound annual growth rate (CAGR) of approximately 6.5% through the 2026–2032 forecast horizon. By 2032 the market is expected to be materially larger than in 2025, reflecting durable demand drivers and accelerating technology adoption.
Worldwide Fire and Gas Detection System Market
Why this report matters for 2026 enterprise decisions
-
Timing of capital commits: With predictable mid-single-digit CAGR growth and clear regulatory momentum, 2026 is a window to prioritize investments in sensor modernization, system integration, and field-service capabilities before supplier consolidation and component supply pressures materially alter pricing and lead-times.
Worldwide Fire and Gas Detection System Market -
Risk-adjusted supplier selection: The market exhibits meaningful concentration among leading suppliers (our competitive concentration metrics show top-three and top-five firms holding a dominant share), which shapes negotiation dynamics for OEMs, systems integrators, and end-users alike. Procurement strategies that emphasize dual sourcing, long-term contracts for critical sensor components, and collaboration on calibration/maintenance will reduce operational disruption risk.
Worldwide Fire and Gas Detection System Market -
Regulatory compliance AND competitive advantage: Recent standards activity—most notably updates that integrate gas detection modalities and open-path/ultrasonic detection into mainstream fire alarm practice—means compliance programs can no longer be a checkbox exercise. Early adopters of integrated detection and predictive monitoring can convert regulatory compliance investments into uptime and insurance-cost advantages.
-
Service and software monetization: As sensors become connected and analytics mature, service-led business models (SaaS for monitoring, predictive maintenance contracts) will generate higher-margin revenue streams and lock-in across installed bases—an urgent consideration for 2026 product roadmap and sales-compensation design.
What operational intelligence the PW Consulting report provides
-
Actionable market sizing and revenue trajectories — comprehensive annualized market totals from our 2025 base through 2032, underpinned by component-level drivers and validated with vendor shipment proxies and buyer surveys.
-
Demand-driver decomposition — granular narrative on macro, regulatory and sectoral drivers (oil & gas, industrial processing, commercial infrastructure, energy systems), including the role of occupational safety standards and industry-specific certification regimes.
-
Supply-chain risk map — supplier tiering for critical components (electrochemical cells, IR/optical optics, semiconductor sensors), lead-time sensitivity, and single-point-of-failure assessment, with mitigation playbooks for OEM procurement teams.
-
Competitive heatmaps and vendor scorecards — qualitative and quantitative benchmarking for leading suppliers across technology breadth, geographic reach, go-to-market model, installed-base service capabilities, and partnership ecosystems.
-
Commercial playbooks — GTM segmentation frameworks for incumbents and challengers, pricing and bundling strategies for integrated hardware+software offers, and channel optimization tactics for system integrators.
-
M&A and investment framework — valuation build-ups, integration risk checklists, and a shortlist methodology for target screening based on technology fit, recurring revenue profile, and aftermarket services potential.
-
Scenario and sensitivity models — baseline (central) forecast aligned with the 6.5% CAGR, plus upside and downside scenarios that stress-test adoption curves, component price inflation, and regulatory acceleration.
Key market dynamics to watch in 2026
-
Regulatory convergence: Standard-setting bodies are actively revising guidance to more tightly integrate multiple detection modalities (gas, open-path, ultrasonic, smoke) into coherent alarm and response workflows. This raises the bar for systems that can demonstrate interoperability and standardized signaling.
-
Sensor technology evolution: Advances in miniaturization, optical components and semiconductor-based sensing are enabling longer range, greater selectivity, and lower false-alarm rates. Equally important is the convergence of IoT connectivity and edge analytics to enable predictive maintenance—turning detection hardware into a data asset.
-
Raw material and component concentration: Production of key elements—precision optics, specialty semiconductors, and electrochemical cells—remains concentrated and sensitive to supply shocks. Vendors and buyers must plan for constrained cycles and prioritize strategic inventories for mission-critical deployments.
-
Service digitalization: Remote calibration, automated reporting, and subscription-based safety monitoring are emerging as differentiators, shifting lifetime value calculations for installed-base management.
Competitive landscape: profile highlights and implications
The competitive field contains a mix of diversified industrial conglomerates, specialized sensors firms, and service-focused entrants. Leading global OEMs bring breadth—integrating detection hardware with process automation and building-management platforms—while niche players excel at high-performance sensing for specialized hazards (e.g., hydrogen, hydrocarbon flame spectroscopy).
-
Honeywell International Inc. — Offers broad fixed and portable portfolios and integrated safety solutions across oil & gas and industrial verticals; strategic advantage lies in scale, channel reach, and integration with building/process controls.
-
MSA Safety Incorporated — Known for industrial-grade fixed detection and open-path technologies; active in standards dialogue and trade forums, shaping the compliance environment that will influence procurement cycles.
-
Drägerwerk AG — Strong in optical flame and multi-gas detection with deep maritime and petrochemical credentials; technology-led differentiation in hostile-environment sensing.
-
Emerson, Siemens, ABB, Johnson Controls — Large automation and building systems players that incorporate fire and gas detection into broader safety and control systems, creating opportunities for platform-driven locking and cross-sell.
-
Specialists (Teledyne, FGD, ESP, Industrial Scientific, Autronica) — Offer high-performance detectors and service models for niche applications where performance or certification is the procurement driver.
Market concentration metrics in our analysis indicate that the top three suppliers together command a significant portion of global revenue, while the top five account for well over half of the market—an important consideration for vendors pursuing scale and for buyers negotiating long-term service agreements.
Recent developments with strategic implication (early 2026)
-
Standards and industry events: MSA’s presence at NFPA conferences and sessions on integrating gas detection with NFPA 72 reflect regulatory attention that will shape procurement specifications and retrofit cycles.
-
Product innovation: The launch of optically enhanced long-range flame detectors signals continuing incremental innovation in detector performance—an accelerant for replacement demand in specialist environments.
-
Trade-show activity by mid-market and HVACR-focused vendors underscores channel-based demand creation in building and institutional segments, expanding the addressable market for certain sensor types.
Practical recommendations for 2026 decision-makers
-
For OEMs and product leaders: Prioritize modular, software-enabled product architectures that support remote diagnostics and subscription services. Allocate R&D budget to optics and semiconductor partnerships to de-risk supply and improve performance.
-
For systems integrators and service providers: Build interoperable stacks that satisfy evolving regulatory test points; invest in training and digital platforms to monetize recurring aftermarket services.
-
For procurement and operations teams in end-user groups: Adopt a risk-tiering approach—segregate assets by consequence and apply differing procurement/contracting strategies for mission-critical vs. commoditized sites. Insist on SLAs that include remote calibration and predictive maintenance metrics.
-
For investors and PE sponsors: Focus due diligence on recurring aftermarket revenues, installed-base service economics, and supplier diversification strategies. Targets with strong software or connectivity capabilities command a premium in integration scenarios.
Scenarios you should model now
-
Baseline: Continued steady adoption in regulated industries and retrofit cycles consistent with the 6.5% CAGR—favors balanced investments in product refresh and service expansion.
-
Upside: Rapid acceleration of IoT adoption, stricter regulation, and successful field deployments of AI-driven diagnostics—creates a window for premium pricing and rapid aftermarket growth.
-
Downside: Component shortages or commoditization of basic detectors compress margins and delay retrofit cycles—necessitates contingency inventory strategies and margin-protecting partnerships.
Next steps and how PW Consulting can support your 2026 strategy
Our report serves as a playbook for leaders needing to make high-confidence decisions in 2026—whether that's prioritizing R&D funding, structuring M&A diligence, negotiating multi-year supplier contracts, or redesigning service offers. The public summary presented here outlines the strategic contours; the full PW Consulting Worldwide Fire and Gas Detection System Market report provides the detailed models, vendor scorecards, scenario tables, and executable templates that executives and investors require.
For boards and executive teams preparing 2026 budgets, the decision levers are clear: accelerate sensor modernization where safety and continuity impacts are highest, lock down critical supply access, and convert detection hardware into a services-driven revenue stream. Access the full report to review our detailed forecasts, segmentation matrices, vendor scorecards, and the operational checklists you can implement this fiscal year.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cloud VPN Market to Reach USD 42.16 Billion by 2032, Growing at a 15% CAGR from USD 15.85 Billion in 2025
By pmarketresearch, 2026-07-15
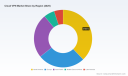
Worldwide Cloud VPN Market — 2026 Strategic Brief
Executive Summary
PW Consulting’s latest market study on the Worldwide Cloud VPN market identifies the sector as a critical infrastructure layer for secure hybrid and multi‑cloud architectures. With the market reaching approximately USD 15.9 billion in our 2025 base year and a robust 15.0% compound annual growth rate projected through our 2026–2032 forecast window, Cloud VPN is transitioning from a tactical remote‑access tool into a strategic networking and security fabric for enterprises, service providers, and regulated industries alike. By 2032, our model projects the market to exceed USD 42 billion, underscoring important strategic inflection points that enterprise decision‑makers must address in 2026.
Worldwide Cloud VPN Market
Why This Report Matters for 2026 Decision‑Making
-
Timing: 2026 is the first pivotal year in which regulatory, energy, and architectural dynamics converge to materially change procurement and deployment economics for Cloud VPN solutions.
Worldwide Cloud VPN Market -
Scope: The report bridges enterprise architecture considerations (SASE, ZTNA, SD‑WAN integration), cloud vendor strategy, operational cost modeling, and regulatory compliance — enabling board‑level clarity for capital allocation and migration sequencing.
Worldwide Cloud VPN Market -
Actionability: Our deliverables are not theoretical — they contain pragmatic playbooks for vendor selection, migration roadmaps, procurement negotiation levers, and TCO scenarios calibrated to contemporary power, labor, and regulatory shocks.
What the Report Contains — Practical Outputs
-
Executive Decision Frameworks: Clear decision trees that align network security posture, performance SLAs, and regulatory constraints to candidate architectures (cloud‑native VPN, managed VPN, ZTNA overlays, or SASE‑first approaches).
-
TCO and Scenario Models: Bottom‑up and sensitivity models that quantify CAPEX/OPEX tradeoffs for in‑house vs. managed deployments, including energy and labor cost scenarios that are particularly relevant to North American and European deployments.
-
Vendor Diagnostic Scorecards: Comparative assessments across security, scalability, manageability, and compliance dimensions — tailored to common enterprise buying personas (CISO, CIO, network architect, and procurement).
-
Regulatory and Data‑Sovereignty Mapping: A compliance playbook that maps major regulatory regimes — including critical changes effective as of 2025 — to deployment patterns and contract clauses buyers should require.
-
Migration Playbooks and Runbooks: Step‑by‑step migration and rollback procedures for hybrid and brownfield environments, including recommended observability KPIs and performance test scripts.
-
M&A and Partnering Playbooks: Strategic criteria for inorganic play or partnerships (technology fit, customer overlap, and integration risk), supported by our market concentration analysis and competitive positioning insights.
Market Health and Competitive Dynamics
The Cloud VPN market is growing rapidly but remains moderately concentrated: the top three vendors account for just over one‑third of the market while the top five approach roughly half the market. This concentration profile creates an environment where scale and platform integration matter, but differentiated security and operational economics create opportunities for challengers and specialist providers. Expect continued vendor consolidation around SASE, zero‑trust and managed service offerings as buyers seek to reduce operational complexity.
Vendor Landscape — Strategic Profiles and Implications
-
Cisco Systems, Inc. — Cisco leverages its SASE and SD‑WAN portfolios to offer integrated cloud‑delivered VPN capabilities. For enterprises with large legacy footprints and complex WANs, Cisco’s breadth and channel ecosystem remain a compelling option. Our analysis highlights integration economics and operational maturity as Cisco’s core strengths.
-
Microsoft Corporation — Azure VPN Gateway is positioned for enterprises prioritizing deep hybrid integration with Azure services. Microsoft’s differentiator is its cloud‑native identity and identity‑driven networking constructs, which align well with organizations standardizing on Microsoft stacks.
-
Amazon Web Services, Inc. — AWS’s recent introduction of a VPN Concentrator (Nov 2025) materially affects multi‑site low‑bandwidth topologies by simplifying Transit Gateway attachments. AWS remains the strategic choice for organizations prioritizing native integration with AWS networking and scalability patterns.
-
Google LLC — Google Cloud VPN targets high‑performance, dynamic routing scenarios and is attractive for latency‑sensitive or multi‑cloud networking architectures where performance and programmability are prioritized.
-
Huawei Technologies — Huawei’s cloud VPN offerings are positioned to serve hybrid enterprises in select markets; their strategy emphasizes tight integration with enterprise networking stacks.
-
Palo Alto Networks — Prisma Access integrates ZTNA and VPN functionality inside a security‑first SASE approach, appealing strongly to security‑led buying centers focused on risk reduction.
-
Fortinet — FortiGate VM and Fortinet’s SASE portfolio continue to attract buyers seeking consolidated firewall and VPN capabilities with competitive TCO for throughput‑intensive use cases.
-
Zscaler — Zscaler’s cloud‑native private access is marketed as a VPN replacement in many use cases; organizations pursuing aggressive zero‑trust transformations will evaluate Zscaler as a strategic alternative.
-
Cloudflare — Cloudflare’s Zero Trust and WARP offerings, reinforced by a February 2026 partnership with Mastercard to enhance cyber defenses, are increasingly relevant for distributed workforce and application security plays where developer experience and cost efficiency matter.
-
Check Point , Oracle , and Array Networks — These vendors occupy niche or vertically focused positions; Check Point and Oracle align with security and cloud platform integrators respectively, while Array targets application delivery and secure gateway use cases.
Regulatory, Infrastructure, and Operational Headwinds
Three categories of external forces will determine winner and loser strategies in 2026:
-
Regulatory Pressure: New rules such as the U.S. Department of Justice’s Bulk Data Rule (effective 2025) and regional initiatives like the EU’s DORA stipulate stricter controls over data flows, auditability, and resilience. These requirements will force architectural changes (e.g., localized processing, enhanced logging) and influence vendor selection and contractual terms.
-
Data Sovereignty and Localisation: Expanding local processing and storage mandates are reshaping deployment topologies. Buyers must align network segmentation, segmentation of management planes, and contractual commitments to meet localized compliance without excessive fragmentation.
-
Infrastructure Economics: Power and labor cost dynamics are increasingly material. Our research accounts for significant electricity demand increases in data center hubs — and localized wholesale price shocks — which will influence the cost competitiveness of cloud‑hosted VPN services versus on‑prem or regionally hosted alternatives.
Strategic Imperatives for 2026
-
Embed Compliance into Architecture: Design VPN and access architectures with regulatory controls and auditability as non‑negotiable requirements rather than retrofits.
-
Prioritize Operational Visibility: Require vendors to deliver pragmatic observability capabilities — latency, path‑performance, and security telemetry — as part of procurement acceptance criteria.
-
Adopt Phased Migration with KPIs: Use staged migrations with defined performance and security KPIs to validate ZTNA overlays, SASE pilots, and managed VPN swaps before wide rollout.
-
Model Energy and Labor Sensitivities: Integrate energy and staffing scenarios into your TCO model to avoid surprise increases in run‑rate costs during 2026–2028.
-
Negotiate Resilience and Data Handling SLAs: Contract clauses must specify jurisdictional constraints, audit access, incident response obligations, and exit procedures to prevent lock‑in and compliance gaps.
What PW Consulting Recommends Next
For enterprise leaders preparing 2026 budgets and technology roadmaps, our report is designed to convert macro trends into board‑level decisions and procurement checklists. Use the report to:
-
Choose an architecture pattern that aligns with both performance needs and expected regulatory constraints;
-
Validate vendor economics under multiple energy and labor scenarios;
-
Identify acquisition or partnership targets that accelerate secure access capabilities or reduce operational complexity;
-
Establish a compliance‑first procurement process with clear exit and audit mechanisms.
Data Availability and Next Steps
To preserve the strategic value of our primary data assets while encouraging direct engagement with PW Consulting, this brief intentionally omits detailed segmented tables and region/application‑level breakdowns. Subscribers to the full Worldwide Cloud VPN Market report receive complete year‑by‑year datasets, vendor benchmarking matrices, and downloadable TCO models for adaptation to organization‑specific inputs.
PW Consulting’s senior analysts are available to conduct executive briefings, vendor short‑lists, and tailored TCO workshops. For organizations that require immediate operational guidance, we recommend commissioning a 4‑week Rapid Assessment that maps your current VPN estate to a compliant, resilient, and cost‑efficient target architecture for 2026–2028.
Contact PW Consulting to access the full report, data tables, and advisory offerings — and equip your leadership with the strategic intelligence required to make confident Cloud VPN decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cloud VPN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Parallel Weld Heads Market (Base Year 2025) to Hit USD 294.06 Million by 2032 at 6.24% CAGR — Asia Pacific Tops with USD 82.56M as Air‑Actuated Heads and Battery Tab Welding Drive Growth
By pmarketresearch, 2026-07-15
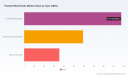
Worldwide Parallel Weld Heads Market: Strategic Insights for 2026 Decision-Making
Executive summary
As manufacturers accelerate electrification, miniaturization, and high-volume micro-joining, parallel weld heads have moved from a niche engineering convenience to a strategic component in modern assembly lines. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—quantifies this shift. The global market for parallel weld heads was valued at approximately USD 192.5 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.24% through 2032, reaching a market size in the high hundreds of millions by the end of the forecast period.
Worldwide Parallel Weld Heads Market
This release is intended as a concise executive primer for C-suite leaders, supply chain managers, and product strategy teams evaluating capex, sourcing, and M&A choices in 2026. It outlines why parallel weld heads matter strategically, the near-term risks that will shape procurement and design decisions, and the operational levers companies should prioritize. To maintain the report’s role as a commercial research product, detailed segment-level tables and granular regional/application splits are intentionally withheld in this preview—interested parties will find the full datasets and interactive models on the report landing page.
Worldwide Parallel Weld Heads Market
Why parallel weld heads are a 2026 strategic priority
-
Enabler of electrification and micro-joining: Parallel weld heads are central to battery tab welding, micro resistance spot welding, and assemblies where single-sided access or tight geometry constraints exist. As battery pack production scales and sensor/electronics assemblies proliferate, investment in parallel welding capability becomes a competitive necessity rather than a specialty option.
Worldwide Parallel Weld Heads Market -
Productivity and repeatability imperatives: High-throughput operations require weld heads that deliver consistency across millions of cycles. Suppliers who pair mechanical design with control firmware and fixture integration provide measurable yield improvement—an increasingly important bargaining chip in supplier selection.
-
Installed-base service economics: Aftermarket support (spares, electrodes, calibration) is a significant and growing margin pool. Firms that architect for serviceability and instrumented diagnostics can convert capital sales into annuity-style revenue streams.
-
Supply chain sensitivity: The industry’s exposure to copper and alloy price volatility, longer lead times for specialty alloys, and consumable shortages means procurement strategies (safety stock, hedging, multi-sourcing) directly affect production continuity and unit costs.
What PW Consulting’s report delivers (practical, executable content)
-
Value-driven market model: A transparent topo-down and bottom-up model with 2020–2025 historical calibration and 2026–2032 scenario outputs. The model is parameterized for alternative demand trajectories and raw-material-price shock scenarios so decision-makers can stress-test capital plans.
-
Supplier scorecards and technology maps: Comparative assessments of the leading OEMs and specialist distributors across product families (pneumatic, electromagnetic, motorized, manual) that highlight differentiation in precision, force range, integration support, and service footprint.
-
Operational playbooks and checklists: Integration templates for cell design, electrode lifecycle management, and process qualification tailored to battery pack, medical device, and microelectronics workflows—aimed at shortening time-to-volume and improving first-pass yield.
-
Procurement and risk tools: Recommended contract structures, a supplier shortlisting framework, and inventory hedging protocols addressing raw-material volatility and critical-lead-time items (electrodes, actuator assemblies, specialty cabling).
-
Go-to-market and M&A guidance: Prioritized white-space maps (qualitative by region and application), partnership archetypes, and transaction frameworks for strategic acquisitions that capture aftermarket and systems-integration value.
Competitive landscape — who matters and why
The parallel weld head ecosystem features a mix of specialized OEMs, integrators, and distributors. Our analysis identifies several strategically important players—each representing different routes to market and capability stacks that buyers should evaluate through both technical and commercial lenses.
-
Sunstone Welders — a design-focused OEM with product lines optimized for micro resistance spot welding and battery tab workflows. Sunstone’s emphasis on same-side electrode access and compact mechanical packaging makes it a frequent first choice for battery module OEMs and laboratories transitioning to production. Recent product comparisons and bench-testing content indicate Sunstone is actively framing its products within complete micro-welding workflows.
-
AMADA WELD TECH — a broad-line resistance welding supplier with deep application engineering resources. AMADA’s portfolio spans pneumatic to motorized and servo-actuated solutions, making it attractive to Tier-1 integrators requiring standardized, scalable systems. Their strength lies in configuration breadth and cross-application credibility across electronics, medical, and automotive sectors.
-
TJ Snow — operates as a key distributor and integrator for specialist parallel weld head lines, positioning itself as a systems enabler for battery pack manufacturing. For buyers prioritizing turnkey readiness and local support, channel partners like TJ Snow reduce technical integration risk.
-
Advanced Integrated Technologies (A‑I‑T) — focuses on ultra-low-force electromagnetic micro weld heads that are purpose-built for precision micro-joining. Their offerings are relevant to customers prioritizing delicate assemblies, such as medical sensors and fine-wire interconnects, where control over contact force and repeatability is paramount.
-
C‑Welding — a distributor network that extends OEM reach into aerospace, automotive, electronics, and medical device manufacturing. Distributors like C‑Welding are often the bridge for small-to-mid-size manufacturers who need local testing, spares, and rapid on-site response.
Strategic takeaways: the vendor landscape is characterized by product specialization combined with distribution partnerships. Buyers will need to weigh OEM innovation against integrator service capabilities, and prioritize suppliers that can demonstrate measurable uptime and electrode lifecycle economics.
Market dynamics, risks, and 2026 tactical responses
-
Raw material volatility: Copper and specialty alloy price swings have impacted procurement and cost forecasting across the resistance welding value chain. For 2026, manufacturers should incorporate raw-material sensitivity bands into capital budgeting, pursue dual sourcing for critical consumables, and evaluate strategic inventory policies for electrodes and contact caps.
-
Lead time and supply constraints: Extended lead times for specialty components and coating processes are already influencing project schedules. Tactical responses include qualifying alternate electrode coatings, modularizing actuator assemblies to simplify repairs, and locking long-lead items earlier in the project lifecycle.
-
Precision and regulatory demands: Automotive, aerospace, and medical customers increasingly demand documented repeatability and process traceability. Weld heads that integrate sensing for force, displacement, and energy delivery—plus digital logging—provide competitive differentiation for suppliers and risk mitigation for OEMs.
-
Application-driven technological choices: Parallel gap (series) welding remains the technique of choice where single-sided access is required. Strategic product decisions should therefore be grounded in a clear mapping from part geometry and materials to weld head actuation technology (pneumatic vs. electromagnetic vs. servo/motorized).
How enterprises should use this research in 2026
-
Capital planning: Time capex to coincide with the maturation of suppliers’ field-proven designs and to capture favorable procurement windows when raw-material price volatility stabilizes.
-
Supplier selection: Use a bifurcated approach—partner with an OEM for technology roadmap alignment and a local integrator/distributor for rapid deployment and aftermarket support.
-
Design for assembly: Incorporate welding constraints early in product design cycles (electrode access, fixturing provision, heat management) to avoid late-stage rework and qualification delays.
-
Service and aftermarket strategy: Capture higher lifetime value by investing in remote diagnostics, consumable subscription models, and structured training for in-house maintenance teams.
-
M&A and partnerships: Consider bolt-on acquisitions that deliver field service capability, consumable manufacturing, or regional distribution networks to accelerate go-to-market and aftermarket capture.
Conclusion and next steps
Parallel weld heads are transitioning from specialist tooling to a strategic enabler in high-growth industrial segments. PW Consulting’s analysis shows a stable growth trajectory with mid-single-digit CAGR through the end of the forecast period, underpinned by electrification and micro-joining demand. For executive teams planning 2026 investments, the core recommendation is to treat welding capability as a systems decision—one that combines mechanical design, control strategy, consumables sourcing, and aftermarket economics.
For readers ready to operationalize these insights, the full report contains detailed segment tables, scenario-model downloads, supplier scorecards, and integration playbooks. These resources are designed to turn market intelligence into executable choices—from tender design and supplier contracts to M&A screening and capex phasing. Visit our report page to access the complete dataset, interactive models, and a downloadable executive briefing tailored to your sector.
For detailed analysis of this topic, please visit the official page: Worldwide Parallel Weld Heads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com