

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Ammonium Polyvanadate Market Poised to Expand at an 8.9% CAGR, New Report Reveals

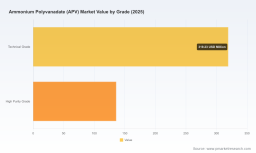
Worldwide Ammonium Polyvanadate (APV) Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
As the ammonium polyvanadate (APV) market transitions from cyclical raw-material dynamics to structurally higher demand, corporate leaders must recalibrate supply, product, and investment strategies for 2026 and beyond. PW Consulting’s latest market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — projects the global APV market to grow from an estimated USD 455.12 Million in 2025 to USD 826.67 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.9% over the forecast period. Short-term momentum is already visible with the market expected to approach roughly USD 494 Million in 2026.
Worldwide Ammonium Polyvanadate (APV) Market
Why this matters for 2026 decision-makers
- Timing of capital deployment: With an accelerating CAGR, investment windows for capacity upgrades, purification technology, and backward integration will tighten. Executives need to prioritize near-term projects that unlock optionality—scalable modules, variable-cost furnaces, and partnerships that can be ramped quickly.
- Supply security and strategic sourcing: The APV value chain is tightly linked to the geography and politics of primary vanadium feedstocks. Raw material concentration and geopolitical shifts are creating new supply risks and price volatility that directly affect APV producers and their buyers.
- Product and market segmentation: End-market demand drivers are evolving (steel alloys vs. chemical catalysts vs. energy storage). Successful players will pair product-grade strategies (technical vs. high-purity positioning) with end-customer routes-to-market rather than treating all APV as a commodity.
Macroeconomic and raw-material context shaping the market
Three structural realities define the near-term landscape. First, global vanadium production remains concentrated — recent authoritative sources estimate global contained vanadium output around 100,000 metric tons in 2023, with China accounting for a dominant share. Second, geopolitical developments have reduced output from certain producers, introducing regional disruption risks. Third, policymakers are treating vanadium as strategic: the European Union’s inclusion of vanadium on its Critical Raw Materials list is a clear signal that regulatory and subsidy frameworks will increasingly influence where and how APV-related investments are made.
Worldwide Ammonium Polyvanadate (APV) Market
For APV stakeholders, these realities translate into actionable risk vectors: feedstock provenance, trade and tariff exposure, and regulatory compliance complexity. Companies that align procurement, processing location choices, and customer contracts with these vectors will be better positioned to stabilize margins and capture growth.
Worldwide Ammonium Polyvanadate (APV) Market
Market dynamics and demand drivers
- Steel and ferroalloys remain the anchor demand pool, underpinning baseline APV volumes and pricing coherence.
- Catalysts and chemical-grade applications continue to support a premium band in the value chain, tightening requirements around impurity profiles and certification.
- Energy storage — notably vanadium redox flow batteries (VRFBs) — presents asymmetric upside. While still at an earlier adoption stage relative to traditional uses, the storage segment’s growth path acts as a strategic lever for producers that can supply high-purity APV at scale.
PW Consulting’s model combines historical production and end-market adoption curves with scenario overlays for VRFB roll-out, steel demand elasticity, and regulatory shifts. The result is a robust base-case outlook and two alternative scenarios that quantify upside from accelerated battery deployment and downside from tightened raw-material bottlenecks.
Competitive landscape — what incumbents are doing
The APV market exhibits moderate concentration: the combined share of the top three firms is substantial but not dominant, and the top five firms hold a meaningful majority of market share. That structure creates both defensive advantages for incumbent producers and entry opportunities for well-capitalized challengers or specialized niche players.
- EVRAZ plc (Moscow) : A vertically integrated vanadium producer with established APV output tied to ferrovanadium and steel applications. Strengths include captive feedstock and downstream integration, which underpin resilience to spot feedstock swings. Watch for export/production adjustments in response to ongoing sanctions dynamics.
- Panzhihua Iron and Steel Group Vanadium Titanium New Material Technology (Panzhihua, China) : Integrated sourcing from vanadium-titanium magnetite gives this group cost and scale advantages. Their strategy emphasizes large-scale V2O5 and ferrovanadium throughput, with APV positioned as a key intermediate. Expect continued focus on process efficiency and domestic supply security.
- Chengde Xinhua Hebei Vanadium Products (Chengde, China) : Specializes in APV from slag streams, catering to chemical and metallurgical markets. Their niche in slag-derived APV creates flexibility in feedstock choice and downstream customization.
- Hebei Jianlong Vanadium Products (Qian'an, China) : Focused on producing APV as an intermediate for high-purity V2O5. Technical capabilities in purification make Jianlong relevant to battery and catalyst supply chains that demand tighter specifications.
- Treibacher Industrie AG (Althofen, Austria) : European supplier of commercial-grade APV to catalysts and specialty chemicals. Their footprint and product breadth make them an attractive partner for customers seeking stable European-origin supply amid wider geopolitical uncertainty.
Collectively, these firms illustrate three strategic playbooks: (1) vertical integration and feedstock control, (2) specialization into higher-margin, high-purity streams, and (3) geographic differentiation to serve regionally sensitive customers. For 2026, the interplay among these approaches will determine who captures incremental volume and margin.
Actionable insights and recommended moves for 2026
- Prioritize flexible, staged capacity investments: Favor modular expansions and retrofits that can switch between technical and high-purity product streams with limited downtime.
- Lockfeedstocks with blended sourcing strategies: Combine long-term offtakes, strategic stocks, and toll-processing partnerships to smooth feedstock cost volatility.
- Differentiate through quality and service, not just price: Buyers of APV will increasingly pay a premium for certified high-purity material and traceable provenance, especially in energy storage and specialty chemicals segments.
- Use the procurement calendar to hedge geopolitics: With production shifts and trade policy risks, aligning procurement and sales contracts to regional policy signals will reduce exposure to sudden supply shocks.
- Consider M&A or JV plays selectively: Targets with access to non-China feedstocks, or with proven high-purity purification technology, should be prioritized for inorganic growth.
What the PW Consulting report delivers (practical, executable content)
This report is deliberately structured for commercial utility. Key deliverables include:
- Validated global APV market sizing and a seven-year forecast (2026–2032) with scenario sensitivity to battery adoption, steel demand shifts, and raw-material disruptions.
- Cost-to-serve models and price-band matrices for technical vs. high-purity product streams, enabling unit-economics analysis for greenfield and brownfield investments.
- Supply-chain risk heatmaps, including feedstock exposure by supply route, logistics chokepoints, and regulatory risk overlays tied to critical-raw-material policy changes.
- Competitive benchmarking: capacity maps, technology gap analysis, and M&A candidate screening criteria tailored for both strategic and financial acquirers.
- Commercial playbooks for producers and buyers: contracting templates, hedging approaches, and go-to-market segmentation that link product specification to buyer willingness-to-pay.
- Operational diagnostic tools: an APV plant readiness checklist, capex prioritization matrix, and process control improvement levers to lift yield and reduce impurity-related downgrades.
To respect client confidentiality and maintain competitive value, the report previews high-level trends and supplier strategies in this public release while reserving detailed subsegment numbers, region-by-region allocations, and company-level production volumes for the full report and data packs.
How to use this intelligence in 2026 planning cycles
For CEOs and line managers planning 2026 budgets, the report offers three immediate use-cases:
- Capex prioritization: Rank near-term projects by NPV under the PW Consulting base and upside scenarios, and fast-track those with shorter payback and higher optionality.
- Procurement redesign: Shift from spot buying to blended sourcing contracts with volume-flex options and supplier scorecards tied to traceability and regulatory compliance.
- Commercial strategy refresh: Re-segment customer accounts by value (not just volume) to align premium product availability with buyers willing to pay for higher purity and guaranteed provenance.
Conclusion — the strategic window is now
APV is no longer a back-office intermediated input; it is a strategic pivot point in several supply chains — from ferroalloys to catalysts to grid-scale energy storage. The market’s projected expansion from an estimated USD 455.12 Million in 2025 to USD 826.67 Million by 2032 at an 8.9% CAGR creates a narrow window for value capture. Firms that align feedstock sourcing, product differentiation, and capacity flexibility will secure outsized returns in 2026 and beyond.
PW Consulting’s full Worldwide Ammonium Polyvanadate (APV) Market report contains the granular segmentations, regional allocations, and executable financial models that corporate leaders will need to convert this strategic preview into operational advantage. For those ready to move from insight to action, the full dataset and advisory options are available through our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Ammonium Polyvanadate (APV) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com