

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fire and Gas Detection Systems Market Forecast to Hit USD 11,654.91 Million by 2032, Growing at a 6.5% CAGR

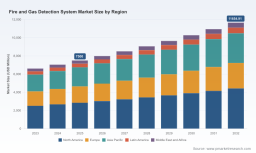
Worldwide Fire and Gas Detection System Market — Strategic Briefing for 2026 Decisions
As organizations across energy, industrial, and commercial sectors reassess risk, continuity, and capital allocation for 2026, the fire and gas detection market stands out as a critical, steadily expanding category of industrial safety spend. Our new PW Consulting report, based on a 2025 baseline and a detailed 2020–2025 historical reconstruction, projects the global fire and gas detection systems market to continue growing at a compound annual growth rate (CAGR) of approximately 6.5% through the 2026–2032 forecast horizon. By 2032 the market is expected to be materially larger than in 2025, reflecting durable demand drivers and accelerating technology adoption.
Worldwide Fire and Gas Detection System Market
Why this report matters for 2026 enterprise decisions
-
Timing of capital commits: With predictable mid-single-digit CAGR growth and clear regulatory momentum, 2026 is a window to prioritize investments in sensor modernization, system integration, and field-service capabilities before supplier consolidation and component supply pressures materially alter pricing and lead-times.
Worldwide Fire and Gas Detection System Market -
Risk-adjusted supplier selection: The market exhibits meaningful concentration among leading suppliers (our competitive concentration metrics show top-three and top-five firms holding a dominant share), which shapes negotiation dynamics for OEMs, systems integrators, and end-users alike. Procurement strategies that emphasize dual sourcing, long-term contracts for critical sensor components, and collaboration on calibration/maintenance will reduce operational disruption risk.
Worldwide Fire and Gas Detection System Market -
Regulatory compliance AND competitive advantage: Recent standards activity—most notably updates that integrate gas detection modalities and open-path/ultrasonic detection into mainstream fire alarm practice—means compliance programs can no longer be a checkbox exercise. Early adopters of integrated detection and predictive monitoring can convert regulatory compliance investments into uptime and insurance-cost advantages.
-
Service and software monetization: As sensors become connected and analytics mature, service-led business models (SaaS for monitoring, predictive maintenance contracts) will generate higher-margin revenue streams and lock-in across installed bases—an urgent consideration for 2026 product roadmap and sales-compensation design.
What operational intelligence the PW Consulting report provides
-
Actionable market sizing and revenue trajectories — comprehensive annualized market totals from our 2025 base through 2032, underpinned by component-level drivers and validated with vendor shipment proxies and buyer surveys.
-
Demand-driver decomposition — granular narrative on macro, regulatory and sectoral drivers (oil & gas, industrial processing, commercial infrastructure, energy systems), including the role of occupational safety standards and industry-specific certification regimes.
-
Supply-chain risk map — supplier tiering for critical components (electrochemical cells, IR/optical optics, semiconductor sensors), lead-time sensitivity, and single-point-of-failure assessment, with mitigation playbooks for OEM procurement teams.
-
Competitive heatmaps and vendor scorecards — qualitative and quantitative benchmarking for leading suppliers across technology breadth, geographic reach, go-to-market model, installed-base service capabilities, and partnership ecosystems.
-
Commercial playbooks — GTM segmentation frameworks for incumbents and challengers, pricing and bundling strategies for integrated hardware+software offers, and channel optimization tactics for system integrators.
-
M&A and investment framework — valuation build-ups, integration risk checklists, and a shortlist methodology for target screening based on technology fit, recurring revenue profile, and aftermarket services potential.
-
Scenario and sensitivity models — baseline (central) forecast aligned with the 6.5% CAGR, plus upside and downside scenarios that stress-test adoption curves, component price inflation, and regulatory acceleration.
Key market dynamics to watch in 2026
-
Regulatory convergence: Standard-setting bodies are actively revising guidance to more tightly integrate multiple detection modalities (gas, open-path, ultrasonic, smoke) into coherent alarm and response workflows. This raises the bar for systems that can demonstrate interoperability and standardized signaling.
-
Sensor technology evolution: Advances in miniaturization, optical components and semiconductor-based sensing are enabling longer range, greater selectivity, and lower false-alarm rates. Equally important is the convergence of IoT connectivity and edge analytics to enable predictive maintenance—turning detection hardware into a data asset.
-
Raw material and component concentration: Production of key elements—precision optics, specialty semiconductors, and electrochemical cells—remains concentrated and sensitive to supply shocks. Vendors and buyers must plan for constrained cycles and prioritize strategic inventories for mission-critical deployments.
-
Service digitalization: Remote calibration, automated reporting, and subscription-based safety monitoring are emerging as differentiators, shifting lifetime value calculations for installed-base management.
Competitive landscape: profile highlights and implications
The competitive field contains a mix of diversified industrial conglomerates, specialized sensors firms, and service-focused entrants. Leading global OEMs bring breadth—integrating detection hardware with process automation and building-management platforms—while niche players excel at high-performance sensing for specialized hazards (e.g., hydrogen, hydrocarbon flame spectroscopy).
-
Honeywell International Inc. — Offers broad fixed and portable portfolios and integrated safety solutions across oil & gas and industrial verticals; strategic advantage lies in scale, channel reach, and integration with building/process controls.
-
MSA Safety Incorporated — Known for industrial-grade fixed detection and open-path technologies; active in standards dialogue and trade forums, shaping the compliance environment that will influence procurement cycles.
-
Drägerwerk AG — Strong in optical flame and multi-gas detection with deep maritime and petrochemical credentials; technology-led differentiation in hostile-environment sensing.
-
Emerson, Siemens, ABB, Johnson Controls — Large automation and building systems players that incorporate fire and gas detection into broader safety and control systems, creating opportunities for platform-driven locking and cross-sell.
-
Specialists (Teledyne, FGD, ESP, Industrial Scientific, Autronica) — Offer high-performance detectors and service models for niche applications where performance or certification is the procurement driver.
Market concentration metrics in our analysis indicate that the top three suppliers together command a significant portion of global revenue, while the top five account for well over half of the market—an important consideration for vendors pursuing scale and for buyers negotiating long-term service agreements.
Recent developments with strategic implication (early 2026)
-
Standards and industry events: MSA’s presence at NFPA conferences and sessions on integrating gas detection with NFPA 72 reflect regulatory attention that will shape procurement specifications and retrofit cycles.
-
Product innovation: The launch of optically enhanced long-range flame detectors signals continuing incremental innovation in detector performance—an accelerant for replacement demand in specialist environments.
-
Trade-show activity by mid-market and HVACR-focused vendors underscores channel-based demand creation in building and institutional segments, expanding the addressable market for certain sensor types.
Practical recommendations for 2026 decision-makers
-
For OEMs and product leaders: Prioritize modular, software-enabled product architectures that support remote diagnostics and subscription services. Allocate R&D budget to optics and semiconductor partnerships to de-risk supply and improve performance.
-
For systems integrators and service providers: Build interoperable stacks that satisfy evolving regulatory test points; invest in training and digital platforms to monetize recurring aftermarket services.
-
For procurement and operations teams in end-user groups: Adopt a risk-tiering approach—segregate assets by consequence and apply differing procurement/contracting strategies for mission-critical vs. commoditized sites. Insist on SLAs that include remote calibration and predictive maintenance metrics.
-
For investors and PE sponsors: Focus due diligence on recurring aftermarket revenues, installed-base service economics, and supplier diversification strategies. Targets with strong software or connectivity capabilities command a premium in integration scenarios.
Scenarios you should model now
-
Baseline: Continued steady adoption in regulated industries and retrofit cycles consistent with the 6.5% CAGR—favors balanced investments in product refresh and service expansion.
-
Upside: Rapid acceleration of IoT adoption, stricter regulation, and successful field deployments of AI-driven diagnostics—creates a window for premium pricing and rapid aftermarket growth.
-
Downside: Component shortages or commoditization of basic detectors compress margins and delay retrofit cycles—necessitates contingency inventory strategies and margin-protecting partnerships.
Next steps and how PW Consulting can support your 2026 strategy
Our report serves as a playbook for leaders needing to make high-confidence decisions in 2026—whether that's prioritizing R&D funding, structuring M&A diligence, negotiating multi-year supplier contracts, or redesigning service offers. The public summary presented here outlines the strategic contours; the full PW Consulting Worldwide Fire and Gas Detection System Market report provides the detailed models, vendor scorecards, scenario tables, and executable templates that executives and investors require.
For boards and executive teams preparing 2026 budgets, the decision levers are clear: accelerate sensor modernization where safety and continuity impacts are highest, lock down critical supply access, and convert detection hardware into a services-driven revenue stream. Access the full report to review our detailed forecasts, segmentation matrices, vendor scorecards, and the operational checklists you can implement this fiscal year.
For detailed analysis of this topic, please visit the official page: Worldwide Fire and Gas Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com