

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Fencing Lame Market Forecast to Reach USD 69.37 Million by 2032, Expanding at a 4.15% CAGR
By pmarketresearch, 2026-07-15
Worldwide Fencing Lame Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting today releases a strategic preview of our forthcoming Worldwide Fencing Lame Market report, designed to equip manufacturers, brands, federations, distributors and private equity investors with the decision-grade intelligence they need for 2026. Drawing on a proprietary synthesis of historical sales trajectories, material- and standards-driven dynamics, supplier registration regimes, and a concentrated competitive landscape, this preview highlights the levers that will determine winners and laggards without disclosing the full, granular segmentation tables reserved for the full report.
Worldwide Fencing Lame Market
Why this market matters in 2026
The fencing lame market has moved from a niche, equipment-focused category toward a regulated, performance-sensitive and brand-differentiated segment. Our analysis shows the total market increasing from approximately USD 42 million in 2020 to just over USD 52 million in the 2025 base year, with a projected compound annual growth rate (CAGR) of about 4.15% over the 2026–2032 forecast window. By 2032 the market is forecast to approach roughly USD 69 million under the baseline scenario.
Worldwide Fencing Lame Market
These headline metrics mask important structural shifts that will drive strategic choices in 2026: rising homologation and labeling costs, tougher material and safety thresholds for international competition, an industry concentration that favors a small set of established manufacturers and suppliers, and evolving supply-chain realities for conductive fabrics and technical assembly.
Worldwide Fencing Lame Market
What’s changed since 2024 — regulation, materials and supplier economics
- Regulatory tightening: Recent Fédération Internationale d'Escrime (FIE) actions — including updated material rules, new mask and uniform drawing guidance, and a supplier registration regime — are re-shaping product compliance economics. New supplier registration and labeling requirements introduce recurring per-supplier and per-item costs that will change the cost base for homologated lames and integrated jackets.
- Higher technical standards: FIE material and safety rules now emphasize conductive thread density and electrical performance (measured under standardized conditions), alongside a stricter perforation resistance threshold for competition-grade clothing. These standards raise the bar for R&D, quality control and third-party testing.
- Materials supply pressure: Conductive fabrics (silver-based or copper/tin composites) remain the critical input. Performance expectations such as balanced warp-and-weft conductivity and low electrical resistance compel specialized textile processing. Where material supply tightness appears, manufacturers face lead-time and cost risk.
Competitive landscape — concentrated, quality-driven, globally distributed
The global competitive fabric of the lame market is relatively concentrated: the top three firms account for a substantial share of the market, and the top five dominate an even larger share. This concentration creates strategic implications for pricing power, homologation influence and channel relationships.
Key players that the full report profiles in depth include heritage European manufacturers known for premium stainless INOX and silver-fiber technologies, long-established Western retailers and distributors that combine brand partnerships with broad market access, and Asian manufacturers that provide scale and competitive pricing through verticalized production of conductive fabrics and jackets. Each archetype presents a distinct risk-reward profile for 2026:
- Premium European manufacturers: strong brand equity, tight performance specs, favored by top-level athletes and federations — but higher cost bases and the need to defend technical leadership.
- Specialist Western distributors/retailers: deep channel reach and service-level advantages for clubs and schools, but dependent on supplier relationships and inventory strategies.
- Asian manufacturers: cost and scale advantages plus growing technical capabilities (including conductive fabric production) — yet exposed to regulatory credentialing and quality perception risks in key markets.
The report includes company profiles, competitor benchmarking and scenario-driven supplier-selection matrices that reflect these trade-offs without publishing proprietary revenue splits in this preview.
What the full PW Consulting report delivers — practical, ready-to-use tools
The full report is structured to enable operational decision-making across procurement, product, channel and corporate strategy. Highlights include:
- Executive playbooks for 12–24 month roadmaps: prioritized initiatives for product homologation, cost-to-serve optimization, inventory hedging and targeted channel expansion.
- Supplier assessment framework: a weighted scorecard to evaluate potential partners on technical compliance, capacity, lead times, quality systems, homologation track record and total landed cost.
- FIE compliance checklist and cost impact module: stepwise guidance on meeting material and safety standards, anticipated testing cadence and modeled cost implications of supplier registration and per-item labeling economics.
- Product development briefs: specification templates (e.g., conductive thread architecture, resistance parameters, washability, weight targets) tailored to competitive foil and sabre offerings and consistent with international rules.
- Commercial scenarios and pricing sensitivity tools: demand- and price-elasticity scenarios, channel margin models for clubs/schools versus retail/distributor routes, and promotional strategies optimized by customer segment.
- M&A and partnership playbook: due-diligence checklists, value-creation levers for consolidation, integration templates focused on manufacturing synergies and homologation asset transfer.
- Raw data appendices and modeling workbook: historical time series, baseline and alternate forecasts, and downloadable model files for custom scenario planning.
Strategic implications for 2026 decision-makers
Stakeholders must translate macro signals into concrete moves in the coming 12 months. Our analysis identifies five priority actions:
- Operationalize compliance early: Treat FIE material and labeling changes as a supply-chain and product-development issue, not just a certification checkbox. Early investment in testing infrastructure or select accredited test partners minimizes time-to-market risk for competition-grade products.
- Reprice with regulatory cost visibility: Factor supplier registration and per-item labeling fees into margin models and commercial negotiations now. These are predictable, recurring cost elements that can be allocated or passed through depending on channel and customer sophistication.
- Diversify conductive fabric sourcing: Given the technical specificity of conductive textiles, pursue a dual-sourcing strategy: retain proven specialty suppliers for high-performance SKUs while developing validated secondary suppliers to protect against lead-time shocks.
- Differentiate through product-service bundles: For clubs, schools and regional federations, combine durable lames with service offerings (fittings, wash-and-repair programs, training modules) to raise switching costs and rebalance margin mix away from low-price commoditized SKUs.
- Prioritize targeted consolidation and partnerships: Use M&A, joint ventures or exclusive distribution agreements to capture scale advantages in manufacturing or access to homologated certification pathways — particularly where top-tier competitors command market share concentrations.
Risk matrix — what could derail the baseline outlook
- Regulatory shock: Further tightening of material rules or more burdensome homologation processes could compress margins and raise product-development timelines.
- Material supply disruption: Scarcity in conductive fabrics or price spikes in silver-based threads would shift competitive advantage toward vertically integrated producers.
- Market-channel frictions: Rapid shifts in participation rates at clubs and schools, or reductions in funding from federations, could re-weight demand across product tiers and channels.
How PW Consulting’s analysis complements your 2026 planning
Our approach combines quantitative growth modeling with the qualitative judgment necessary where regulation and technical performance matter. The full report delivers the calibrated demand forecasts, cost impact analyses and supplier scorecards you will use to prioritize investments and negotiate with partners in 2026 — while preserving the commercial confidentiality of segment-level revenue and regional breakdowns.
Next steps — access the full intelligence
This editorial preview frames the strategic choices the fencing lame market will present in 2026. For procurement directors, product heads and strategic investors seeking the full datasets, proprietary segment tables, company revenue benchmarks, and downloadable scenario models, PW Consulting’s full Worldwide Fencing Lame Market report contains the operational detail required to act decisively.
Contact PW Consulting to receive the complete report, including: the full forecast model through 2032, granular segmentation and regional analyses, supplier rankings and the ready-to-use playbooks described above. Our team can also arrange a tailored briefing to apply the findings to your organization’s specific risk profile and strategic horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Fencing Lame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Classified Circuit Breaker Market Poised to Expand at a 6.0% CAGR, New Insights Reveal
By pmarketresearch, 2026-07-15
Worldwide Classified Circuit Breaker Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market study—base year 2025, forecasting 2026–2032—delivers a pragmatic, decision-focused assessment of the classified circuit breaker market designed to inform procurement, product strategy, and M&A choices in 2026. The market has evolved from roughly USD 410.5 Million in 2020 to USD 540.0 Million in 2025, with our proprietary modeling projecting continued expansion to approximately USD 578.6 Million in 2026 and reaching about USD 812.0 Million by 2032. This trajectory reflects a compound annual growth rate (CAGR) of 6.0% over the forecast horizon and underscores structural demand drivers that will shape supplier and buyer behavior in the next strategic planning cycle.
Worldwide Classified Circuit Breaker Market
Why this report matters for 2026 planning
-
Timing. With grid modernization projects, renewable integration, and retrofitting cycles accelerating, 2026 is when many corporates and utilities will need to convert strategic intent into procurement and capex allocations. Our report turns market momentum into executable choices.
Worldwide Classified Circuit Breaker Market -
Risk-aware growth. The study combines top‑down market sizing with bottom‑up supplier and channel analysis so executives can prioritize investments that balance growth potential with supply‑chain and regulatory risk.
Worldwide Classified Circuit Breaker Market -
Competitive clarity without spoilers. We provide a forward-looking view of competitive positioning and capability gaps while reserving detailed subsegment tables for licensed subscribers—ideal for organizations that want the blueprint but need to keep tactical numbers under NDA.
Market trajectory and what the headline numbers hide
The headline growth—from roughly USD 540.0 Million in 2025 to an estimated USD 578.6 Million in 2026—signals steady demand, but beneath this aggregate expansion are differentiated dynamics: substitution of legacy units, increased uptake of digitally enabled breakers, and regional modernization rhythms tied to distribution network reinvestment. Our forecast to 2032 captures nonlinear inflections driven by technology certification cycles and supply chain localization initiatives. Practically, this means procurement officers and product leaders should expect steady topline growth while preparing for episodic shifts in sourcing and product specs as smart and classified‑compatible options gain share.
Key dynamics shaping supplier and buyer strategy
-
Interchangeability and standards. UL‑classification remains a central enabler of third‑party replacement markets: compliance allows compatibility across multiple OEM loadcenters and creates a resilient aftermarket channel. For suppliers, investing in classification testing is table stakes; for buyers, it opens the opportunity to optimize total cost of ownership through validated third‑party options.
-
Product innovation and digitalization. The migration toward smart breakers with remote monitoring, trip analytics, and integration into building energy management systems is creating a premium tier of demand. Certification timelines for digitally enabled products mean that entrants who can expedite approvals will capture early adopter budgets.
-
Supply‑chain localization. Manufacturers are increasingly announcing local assembly and regional capacity expansion to reduce lead times and tariff exposure. This reduces logistics risk for large retrofit programs but raises the bar on local regulatory and quality assurance capabilities.
-
Raw‑material pressure. Copper, steel and engineering plastics remain key inputs; material cost volatility and availability affect both pricing and lead times for molded case and miniature breakers. Procurement strategies must therefore include hedging, multi‑sourcing and supplier performance metrics tied to material security.
Competitive landscape — capabilities and battlegrounds
The market displays moderate concentration: our analysis shows the top three vendors control just over half the market, while the top five approach seven in ten. That structure produces a two‑speed competitive environment—large global incumbents competing on breadth and channel access, and specialized suppliers competing on compatibility, form factor and aftermarket services.
-
Eaton Corporation (Dublin, Ireland) — Broad product line of UL‑classified breakers and deep compatibility claims across hundreds of legacy loadcenters. Eaton’s strength is its cross‑portfolio presence (arc‑fault, ground‑fault, surge, thermal magnetic) and marginal advantage in channel familiarity with electrical contractors.
-
Connecticut Electric (United States) — Niche expertise in classified replacements for residential and light commercial panels. The company’s focus on interchangeability and aftermarket reliability makes it a go‑to for retrofit projects where minimizing panel rework is critical.
-
Siemens (Munich, Germany) — Global engineering footprint and a full spectrum of breakers. Siemens leverages scale and global certification experience, making it a preferred supplier in projects that demand integrated solutions beyond single‑panel replacements.
-
ABB Ltd (Zurich, Switzerland) — Strong industrial and utility lineage, with a portfolio spanning low to high voltage. ABB competes where industrial robustness and integration into power distribution systems are decisive.
-
Schneider Electric (Rueil‑Malmaison, France) — Market influence via branded loadcenters and partner channels. Schneider’s ecosystem advantage influences compatibility dynamics and aftermarket replacement pathways.
-
GE Vernova (United States) — Legacy OEM credibility in residential and commercial panels, with product lines that accept classified replacements; this duality shapes OEM aftermarket strategies.
-
CHINT Group (China) — Rapidly expanding global footprint and recent announcements around local assembly for air circuit breakers indicate an aggressive localization play that aims to shorten lead times and compete on price for regionally scaled projects.
-
Mitsubishi Electric, LS Electric, Fuji Electric — Representing the broader pool of established global suppliers, each brings distinct strengths in molded case and industrial breakers; their competitive role is often tied to regional projects and system integration requirements.
Recent market signals that will influence 2026 decisions
-
Regional assembly initiatives. Announcements of local assembly operations for air circuit breakers underscore a deliberate shift toward on‑shoring and near‑shoring to de‑risk long lead times for large retrofit and utility programs.
-
Trade shows as innovation accelerators. Prototypes of digitally enabled breakers surfaced at leading industry exhibitions, indicating that certification and go‑to‑market timing for smart products will be a critical gating factor in 2026 purchasing windows.
-
Smart device proliferation. Increased presence of intelligent breakers at major industrial shows signals accelerating integration into factory automation and energy management stacks—buyers should factor integration and data licensing into procurement specifications.
What the PW Consulting report contains — practical, transaction‑grade deliverables
Our study is structured to be immediately usable by strategy, procurement, and product teams. It includes:
-
Proprietary market model and demand scenarios calibrated to 2020–2025 historicals and extended through 2032, with sensitivity runs for material price shocks and accelerated smart‑breaker adoption.
-
Supplier scorecards that evaluate certification breadth, form‑factor coverage, channel access, and aftermarket service capabilities to support vendor selection and sourcing consolidation.
-
Go‑to‑market playbooks for entrants and incumbents, including pricing frameworks, distributor incentive structures, and retrofit program engagement templates.
-
M&A and partnership heatmap identifying strategic targets across capability gaps (digital, local assembly, certification breadth) and geographic presence.
-
Regulatory and standards tracker focused on interchangeability and UL classification developments, plus a compliance checklist for product managers.
-
Supply‑chain risk matrix and mitigation strategies addressing raw material constraints, lead time variability and localization trade‑offs.
Note: to preserve the utility of this briefing and in line with our "trailer" approach, detailed subsegment-level tables (regional splits, application‑level shares, and price/volume matrices) are available exclusively in the licensed document. These granular datasets enable precise tender-level budgeting and competitive benchmarking—requests for bespoke extracts are supported under subscription.
Strategic recommendations for 2026
-
For buyers and system integrators: prioritize classified‑compliant products with proven interoperability and insist on data integration capabilities to future‑proof asset management.
-
For suppliers: accelerate classification testing and target regional assembly partnerships to shorten delivery times for retrofit projects; concurrently, develop software and services around breaker data to capture higher gross margins.
-
For investors and M&A teams: focus on targets that combine certification breadth with digital capabilities or local assembly footprints—these attributes unlock premium valuations as buyers internalize total cost and reliability concerns.
Concluding perspective
The classified circuit breaker market is neither a simple replacement market nor purely a high‑growth, high‑margin technology race—it is a hybrid arena where standards, physical interchangeability and emerging digital capabilities intersect. The market’s steady compound growth—anchored by clear structural drivers—creates multiple levers for value creation: supply‑chain resilience, certification leadership, and digital monetization. PW Consulting’s report converts these levers into prioritized actions, practical vendor scorecards, and transaction-ready intelligence that will be essential for corporate decisions in 2026.
Accessing the full intelligence
For procurement teams, strategy leads, and investors seeking the full dataset, including detailed regional and application splits, price/volume matrices, and bespoke modelling, the complete report and licensed data extracts are available through PW Consulting. Contact our market research team to schedule a briefing and receive sample extract options tailored to your decision agenda.
For detailed analysis of this topic, please visit the official page: Worldwide Classified Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Steady Rise in Worldwide Oxcarbazepine Market — 3.15% CAGR Forecast to 2032
By pmarketresearch, 2026-07-15
Worldwide Oxcarbazepine Market: Strategic Imperatives for 2026 Decision Makers
Executive summary
PW Consulting’s latest Worldwide Oxcarbazepine Market report (base year 2025, forecast period 2026–2032) equips executives with the strategic intelligence required to make high-consequence decisions in 2026. The global market measured USD 310.0 Million in 2025 and is projected to grow to approximately USD 385.17 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 3.15% across the forecast window. Historical performance between 2020 and 2025 shows moderate expansion with periodic volatility driven by supply disruptions and episodic demand swings—conditions that will shape investment, sourcing and commercial strategies in the coming 18–36 months.
Worldwide Oxcarbazepine Market
Why this report matters for 2026 planning
- Data-driven foresight: The report translates a multi-year time series (2020–2025) and scenario forecasts (2026–2032) into operational KPIs that CFOs, head of manufacturing, BD leads and market access teams can act on in 2026.
- Market structure clarity: With a measured market concentration (CR3 ≈ 38.5%; CR5 ≈ 52.2%), the competitive landscape is sufficiently consolidated to support targeted M&A and alliance plays, yet still offers openings for agile midsize players and new entrants focused on differentiated formulations and supply assurance.
- Operational urgency: Recent regulatory and supply events have created transient windows where capacity investments, API security and alternative formulation launches can deliver outsized commercial returns.
Market overview — headline metrics and observed dynamics
Our analysis shows the worldwide Oxcarbazepine market following a steady, albeit unspectacular, growth path: from USD 265.47 Million in 2020 to USD 310.0 Million in 2025. The 2026 projection moves the market to USD 325.98 Million, with expected incremental expansion through 2032 to USD 385.17 Million under a central-case CAGR of 3.15% (2026–2032). This trajectory is influenced by three persistent dynamics:
Worldwide Oxcarbazepine Market
- Demand stability tied to epilepsy and related neurological indications (Oxcarbazepine remains on the WHO Model List of Essential Medicines), which underpins baseline volume.
- Periodic supply shocks—documented shortages in 2022–2023—have elevated the strategic value of manufacturing redundancy and API sourcing diversification.
- Regulatory and reimbursement backdrops in major markets (example: Medicare Part D coverage dynamics) drive list-price pressure and shape formulary access strategies.
What the report contains — practical, execution-focused deliverables
PW Consulting’s report was designed as a practitioner’s toolkit rather than an academic survey. Key deliverables include:
Worldwide Oxcarbazepine Market
- Comprehensive market sizing and trajectory models (by year, 2020–2032) in USD Million with scenario-variant outputs for stress-testing investment cases.
- Segment and channel frameworks (formulation, application, and geography) with interactive dashboards — core segmentation methodologies are described in detail while granular segment-level datapoints are reserved for the full dataset.
- Competitive benchmarking and risk-scored company profiles for every active supplier, including capability maps across regulatory approvals, manufacturing footprint, and distribution reach.
- Supply chain and API risk matrix, including DMF counts and geographic concentration analysis of API sources.
- Practical playbooks: launch sequencing for XR and pediatric suspensions, supplier negotiation templates, capacity investment decision-support, and M&A screening criteria tuned to mid-market consolidation opportunities.
- Policy and reimbursement impact assessment with payer-engagement templates tailored to the U.S. Medicare Part D environment and major EMEA markets.
Competitive landscape — practical implications for market players
The Oxcarbazepine sector is dominated by established generic manufacturers and specialty generics arms of large pharmas. Key players included in our competitive analysis are Teva Pharmaceutical Industries Ltd., Viatris Inc., Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Lupin Ltd., Aurobindo Pharma Ltd., Zydus Lifesciences Ltd., Cipla Ltd., Sandoz International GmbH, Apotex Inc., MSN Laboratories Pvt. Ltd., and Alembic Pharmaceuticals Ltd.
- Teva Pharmaceutical Industries Ltd. (Petah Tikva, Israel) — Strength: Global manufacturing scale and well-entrenched distribution networks for multiple oxcarbazepine presentations. Strategic consideration: leverage scale to defend share but monitor cost-of-goods sensitivity.
- Viatris Inc. (Canonsburg, PA, USA) — Strength: Portfolio breadth including immediate- and extended-release formats; strong commercial infrastructure in regulated markets. Strategic consideration: prioritize differentiation through lifecycle and packaging innovations.
- Sun Pharmaceutical Industries Ltd. (Mumbai, India) — Strength: ANDA and EMA capabilities supporting both regulated and emerging market supply. Strategic consideration: target high-volume branded generics replacement opportunities.
- Dr. Reddy’s Laboratories Ltd. (Hyderabad, India) — Strength: USFDA-approved exports and established supply routes into North America. Strategic consideration: capitalize on tender and wholesaler channels to mitigate margin compression.
- Lupin Ltd. (Mumbai, India) — Strength: Pediatric suspension capability and recent product launches in the U.S. Strategic consideration: pediatric formulations serve as defensive niches with lower price elasticity.
- Aurobindo Pharma Ltd. (Hyderabad, India) — Strength: Multi-strength tablet manufacturing approvals for North America. Strategic consideration: consider capacity partnerships or tolling agreements to capture short-term demand surges.
- Zydus Lifesciences Ltd. (Ahmedabad, India) — Strength: Extended-release offerings. Strategic consideration: differentiated XR products can command more stable reimbursement positioning.
- Cipla Ltd. (Mumbai, India) — Strength: Regulated market exports and established brand presence. Strategic consideration: leverage global commercial channels for lifecycle variations.
- Sandoz International GmbH (Basel, Switzerland) — Strength: Large generics division with robust EU footing. Strategic consideration: interplay with parent Novartis capabilities for supply continuity.
- Apotex Inc. (Toronto, Canada) — Strength: North American manufacturing presence; strategic for regional procurement. Strategic consideration: focus on tender responsiveness and distributor relationships.
- MSN Laboratories Pvt. Ltd. (Hyderabad, India) — Strength: Recent USFDA approval for extended-release tablets (Sep 2023). Strategic consideration: first-mover advantage in specific XR niches — watch launch timing and scale-up risk.
- Alembic Pharmaceuticals Ltd. (Vadodara, India) — Strength: US wholesale supply footprints for multiple strengths. Strategic consideration: pursue scale agreements with large wholesaler networks.
Recent developments shaping the 2026 agenda
- MSN Laboratories received final USFDA approval for an extended-release oxcarbazepine ANDA (Sep 2023), creating fresh supply competition for XR segments.
- The US FDA officially noted shortage resolution for 300 mg oxcarbazepine tablets in mid-2023, an event that temporarily elevated market prices and strategic value of redundant capacity.
- Product introductions, such as Lupin’s USFDA-approved oral suspension launch (July 2022), highlight the commercial potential of pediatric formulations as a differentiation vector.
- Fundamental drivers: original patents expired well over a decade ago; the API base is concentrated in India and China with more than 20 manufacturers holding DMFs—an operational reality that increases geopolitical and quality risk profiles.
Strategic playbook for 2026 — recommended actions
- Supply chain resilience: secure dual-sourced API contracts with at least one manufacturer holding an active DMF and one geographically diversified supplier. Consider private-label API stockpiling for critical strengths.
- Manufacturing flexibility: invest selectively in modular production or CMO arrangements that can be ramped in 3–6 months to respond to shortages and tender opportunities.
- Product differentiation: prioritize extended-release and pediatric suspensions in commercial plans—these formats reduce pure-price competition and can attract premium formulary positioning.
- M&A and partnerships: target bolt-on acquisitions or co-manufacturing deals with mid-tier players to consolidate local distribution channels and improve CR5 positioning.
- Reimbursement engagement: build targeted payer dossiers (especially for Medicare Part D in the U.S.) that articulate adherence and health-economics benefits of XR and suspension formulations.
- Regulatory playbook: accelerate ANDA filings where market openings are forecasted in 2026, and maintain active DMF filings to facilitate rapid market entry.
Risk scenarios to monitor
We model three principal downside scenarios that should be integrated into board-level risk registers for 2026: (1) a supply shock from a major API site closure leading to short-term price spikes; (2) accelerated price erosion driven by aggressive tendering in a major geography; and (3) reimbursement pressure from formulary reclassification. Each scenario has quantified P&L and working-capital impacts in the full report.
How PW Consulting supports execution
Beyond the published dossier, PW Consulting offers tailored engagement options for companies that want to operationalize the findings:
- Custom due diligence for M&A targets with supplier audits and integration roadmaps.
- Supplier risk assessments and API diversification programs, including contract templates and contingency plans.
- Value-based pricing models and payer engagement playbooks for the U.S. Medicare Part D and major European reimbursement agencies.
- Commercial launch sequencing and sales-force targeting matrices for XR and pediatric products.
Next steps
This executive overview highlights the strategic value of granular insights contained in the full Worldwide Oxcarbazepine Market report. For decision-makers preparing 2026 budgets, the report converts market-level forecasts (USD Million), concentration metrics (CR3/CR5), and supply/regulatory dynamics into actionable investment and commercialization plans. To access the complete dataset, segment-level analytics, and the suite of operational playbooks referenced above, please consult the full PW Consulting report page where the underlying models and proprietary attachments are available for licensed download.
For detailed analysis of this topic, please visit the official page: Worldwide Oxcarbazepine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Insect Repellent Supplies Market to Reach USD 7,438.32 Million by 2032 at a 6.3% CAGR — Asia Pacific Leads with USD 1,842.48M
By pmarketresearch, 2026-07-15
Worldwide Insect Repellent Supplies Market: Strategic Lens for 2026 — PW Consulting Insights
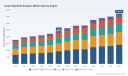
As businesses prepare strategy roadmaps for 2026, understanding the evolving economics of insect repellent supplies is no longer ancillary — it is central to risk management, product innovation, and route-to-market choices across consumer, industrial, and public-health channels. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) shows a market that reached approximately USD 4.85 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.3%, reaching roughly USD 7.44 billion by 2032. This growth trajectory masks important inflection points driven by ingredient innovation, regulation, channel shifts and concentrated competitive dynamics — all of which matter for boardroom decisions in 2026.
Worldwide Insect Repellent Supplies Market
Why this matters to executives in 2026
- Capital allocation and portfolio prioritization: A mid-single-digit CAGR hides uneven upside pockets — categories tied to travel and outdoor recreation, premium topical formulations, and spatial protection devices are accelerating differently. Firms must prioritize investments that align with consumer willingness to pay for efficacy, convenience and perceived safety.
- Regulatory risk and product lifecycle planning: Tighter efficacy and labeling requirements in major jurisdictions mean time-to-market and dossier readiness are as decisive as R&D. Regulatory lead times can materially affect NPD scheduling and commercial launches in 2026 and beyond.
- Supply-chain resilience: Dependence on specific active ingredients — both synthetic and botanical — requires dual-sourcing strategies and procurement hedging to avoid price and availability shocks that could compress margins.
Market snapshot (strategic highlights)
Key macro takeaways for 2026 planning: global demand has rebounded strongly since 2020 and the market scale in 2025 provides a solid base for future expansion. Growth at a 6.3% CAGR through 2032 indicates sustained consumer and institutional spending on personal protection and household/area products. Market concentration metrics (CR3 ~42.5%; CR5 ~58.8%) tell a clear story: leading manufacturers retain meaningful share — enough to shape distribution and innovation dynamics — while space remains for focused challengers and regional specialists to scale.
Worldwide Insect Repellent Supplies Market
What the PW Consulting report delivers to decision-makers
- Robust scenario models that translate macro growth into revenue and margin outcomes under varying regulatory, raw-material and channel assumptions (conservative / base / growth scenarios).
- Actionable playbooks for R&D prioritization: formulation roadmaps, active-ingredient substitution decision trees, and accelerated stability/regulatory testing pathways that reduce time-to-shelf risk.
- Commercial blueprints for channel strategies across direct retail, e-commerce, professional pest control, and institutional procurement — including retailer negotiation levers and promotional elasticities.
- Supply-chain stress tests and procurement playbooks addressing single-source raw materials and botanical supply seasonality, with tactical contingency options for 2026 disruptions.
- Competitive benchmark matrices and capability gap analyses (product, manufacturing, regulatory, go-to-market) enabling M&A or partnership screening.
Competitive landscape — implications for strategic positioning
The competitive field comprises large multinational consumer-goods firms, specialized outdoor and technical players, ingredient suppliers, and regional champions. Major brand owners continue to leverage scale in manufacturing, marketing, and distribution, while niche players compete on formulation performance, actives, and channel intimacy.
Worldwide Insect Repellent Supplies Market
- Global consumer-goods leaders: Firms with broad household portfolios possess advantages in cross-category promotions and trade terms, and they continue to invest in manufacturing capacity in growth markets. Expect continued deployment of platform investments (high-speed lines, flexible fill formats) in 2026 to reduce per-unit costs and accelerate new SKU introductions.
- Specialized performance brands: Suppliers focused on outdoor, travel, and professional markets differentiate through high-efficacy actives, controlled-release technologies and durable formulations for clothing treatment. These players will be attractive partners or acquisition targets for firms seeking credibility in performance segments.
- Ingredient and active-ingredient suppliers: Control of key actives (synthetic and botanical) confers a strategic edge. Companies that can guarantee supply and regulatory dossiers bring value beyond commodity pricing — they enable faster market entry for formulators across jurisdictions.
For executives evaluating competitive moves in 2026, the report’s benchmarking reveals where to invest to widen capability gaps — e.g., area-device mechanics, battery performance for rechargeable devices, or patent-protected controlled-release systems. It also quantifies the premium consumers consistently pay for perceived safety and longer protection durations, which should inform pricing and claims strategy.
Regulatory and ingredient dynamics shaping 2026 choices
- Efficacy and testing expectations: Major regulators are clarifying efficacy testing requirements for skin-applied products against vector species commonly linked to disease transmission. New or updated guidelines are increasing validation burdens for entrants and established brands alike.
- Botanical actives and age labeling: Specific use-conditions and age considerations for certain botanical actives are influencing formulation strategy, packaging claims and marketing positioning. This creates both marketable differentiation and complexity for global launches.
- EU dossier regimes and compliance: The need for comprehensive active-substance dossiers in key markets is raising the bar for formulators. Access to product-dossier license schemes or partnerships with dossier-holding suppliers can materially shorten market access timelines.
- Key actives: Market demand continues for both synthetic (e.g., low-odor, high-efficacy molecules deployed for topical repellent products) and plant-derived options (e.g., citrus-derivative actives used in premium “natural” claims). Procurement and formulation teams should align on multi-ingredient roadmaps to balance efficacy, cost and regulatory risk.
M&A, innovation and recent market developments
Deal activity and product launches in 2025–2026 demonstrate two concurrent trends: (1) incumbents acquiring biologically-oriented capabilities to broaden vector-control offerings, and (2) smaller innovators bringing DEET-free and battery-optimized devices to market. Strategic implications for 2026:
- Acquisitions that augment biological control or active-ingredient portfolios can accelerate entry into professional and institutional segments, where long-term contracts and service bundles increase lifetime value.
- Product innovations that reduce user friction — improved rechargeable devices, fast-charging batteries, and sustained-release formulations — unlock new premium segments and recurring-replacement economics.
- Capacity expansions in growth regions signal where supply constraints and cost efficiencies will tighten or relax over the next 12–24 months.
Go-to-market plays — what winning looks like in 2026
Based on our analysis, winning commercial strategies will combine three elements:
- Precision segmentation: Targeting by consumer behavior and channel (not just geography) — e.g., urban families seeking “gentle” formulations vs. outdoor enthusiasts prioritizing long-duration efficacy — allows for focused marketing and SKU rationalization.
- Claims and compliance architecture: Investing in robust efficacy dossiers and harmonized labeling to reduce launch friction across major jurisdictions. This pays dividends in retailer acceptance and institutional procurement.
- Manufacturing and sourcing agility: Modular production lines and multi-origin sourcing for key actives reduce time-to-react during supply shocks and support test-and-learn NPD cycles.
Pocket playbook — five actions for 2026
- Run a 90-day audit of active-ingredient exposure and regulatory dossier ownership across your portfolio; prioritize remedies where single-supplier dependence exists.
- Reallocate a portion of R&D budget to controlled-release and device-integrated solutions that extend protection duration and create repeat purchase dynamics.
- Negotiate product-dossier or licensing partnerships with active suppliers to accelerate entry into regulated markets with high barriers to entry.
- Design premium “safety-forward” SKUs that leverage botanical actives — but validate claims with third-party efficacy testing to avoid post-launch relabeling risk.
- Build M&A filters that value supply security and formulation IP (not just revenue), focusing on owners of dossier libraries, patented actives or device mechanics.
What PW Consulting’s report intentionally withholds — and why
To preserve competitive value and adhere to the “trailer” principle, this overview omits detailed regional and application-level splits and precise SKU-level revenue tables. The full report contains granular segmentation (regional, product-type, formulation, channel), proprietary elasticity matrices, and downloadable models that power the scenario outputs summarized above. Access to those datasets will enable teams to run bespoke simulations and produce go/no-go investment memos tailored to 2026 capital plans.
Next steps
For executive teams preparing 2026 strategies — whether prioritizing organic innovation, M&A, or supply-chain fortification — PW Consulting’s full Worldwide Insect Repellent Supplies Market report provides the data, tools and playbooks needed to translate the sector’s 6.3% CAGR and market-scale trajectory into defensible commercial decisions. Contact our practice to schedule a strategy workshop that converts the report’s insights into a 12–24 month action roadmap customized to your capabilities and risk appetite.
For detailed analysis of this topic, please visit the official page: Worldwide Insect Repellent Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polylactic Acid Straw Market Set to Surge at a 12% CAGR as Sustainability Fuels Rapid Expansion
By pmarketresearch, 2026-07-15
Worldwide Polylactic Acid (PLA) Straw Market — Strategic Preview for 2026 Decision-Makers
As Senior Strategy Consultant and Chief Industry Analyst at PW Consulting, I am pleased to present a forward-looking executive preview of our new Worldwide Polylactic Acid (PLA) Straw Market report. The overview that follows synthesizes the report’s most consequential insights for corporate leaders planning capital, procurement, product and regulatory strategies in 2026. We anchor our analysis in the market’s demonstrated momentum — from roughly half a billion USD in 2020 to approximately USD 1.15 billion in 2025 — and a robust mid-teens expansion trajectory, with a projected compound annual growth rate of 12% through the 2026–2032 forecast window.
Worldwide Polylactic Acid Straw Market
Why 2026 Is a Pivotal Year
-
Regulatory acceleration. Policy instruments that restrict single-use plastics have moved from novelty to mainstream. Enforcement and certification regimes in major jurisdictions have raised the bar for compostability and end-of-life claims, increasing the value of certified PLA formulations and creating barriers for commodity entrants that cannot demonstrate compliance.
Worldwide Polylactic Acid Straw Market -
Supply-side evolution. Producers of PLA resin are scaling capacity and launching grades optimized for straw extrusion. These moves materially alter supply negotiation dynamics — where previously buyers could treat PLA as a commodity, they must now evaluate grade-specific performance (clarity, tensile strength, heat resistance) and secure long-term supply pathways aligned with product specs.
Worldwide Polylactic Acid Straw Market -
Commodity volatility and feedstock risk. Agricultural feedstock and intermediate inputs for PLA have shown meaningful price swings in recent periods. This volatility constrains margin predictability for manufacturers and elevates the strategic importance of feedstock hedging, vertical integration and supplier risk management.
-
Trade and tariff friction. Import duties and trade remedies on PLA-origin inputs and finished goods are reshaping sourcing calculus for global buyers, prompting many to reassess nearshoring, regional manufacturing footprints and tariff engineering opportunities.
What the Report Delivers — Practical, Executable Outputs
PW Consulting’s report was designed as a decision tool for executives, not an academic exercise. Its deliverables are oriented around executable choices and include:
-
A validated market-sizing model and forward-looking projections (top-line and scenario-based) that translate macro demand into volume and revenue implications across realistic adoption pathways.
-
Actionable supplier and resin-sourcing playbooks, including a benchmarked supplier risk matrix and contract structures that lock desirable resin grades while mitigating price exposure.
-
Product development and manufacturing checklists covering extrusion parameters, grade selection, compostability certification, and testing protocols for foodservice and retail applications.
-
Regulatory compliance roadmaps for key jurisdictions, with a prioritized checklist of certification steps and consumer-claims guidance to avoid greenwashing risks.
-
Commercial go-to-market strategies and pricing sensitivity models that map margin impacts under alternative feedstock and tariff assumptions.
-
M&A and partnership screening criteria, together with a short-list of strategic moves for incumbents and new entrants (JV templates, licensing approaches, and contract-manufacturing options).
To preserve the strategic value of the report for our clients, detailed regional and application-level splits are published only in the full report and the accompanying Excel model. This preview highlights the analytical thrust and decision levers without reproducing the fine-grained data tables.
Competitive Landscape — How Leading Players Are Shaping the Market
The PLA straw ecosystem is characterized by an upstream layer of resin producers and a downstream layer of converters, brand owners and foodservice suppliers. Several players warrant close attention for the strategic signals they send to the market:
-
TotalEnergies Corbion — With Luminy PLA grades tailored for straw extrusion, the company is pushing performance differentiation (improved clarity and strength). The strategic implication: buyers will increasingly source by grade characteristics, not just by supplier name, creating opportunities for long-term grade-specific supply agreements.
-
NatureWorks — Capacity expansion initiatives (notably at its North American sites) signal confidence in sustained demand for compostable products. For buyers, timing of offtake contracts and access to expanded capacity will be a negotiation lever in 2026.
-
Biome Bioplastics , Biopac India , Ecor Products , Green Straw and Vegware — These converters and branded suppliers emphasize certification, end-use performance, and route-to-market specialization (foodservice vs retail). Their presence underscores an increasingly bifurcated market: one axis focused on performance/industrial compostability, the other on cost-led, mass-market alternatives.
Our competitive analysis shows a market where no single group dominates; instead, competitive advantage is earned through grade ownership, certification credentials, and integrated supply solutions. In practice, this means consolidation pressure in the middle of the value chain and strategic partnerships between resin makers and converters to deliver end-to-end validated product claims.
Strategic Implications for 2026
-
Procurement and hedging: Firms should move from spot-buying to multi-year offtakes with performance clauses. Consider feedstock-linked pricing or blended purchasing to smooth volatility and protect margins.
-
Product differentiation: Invest in grades that deliver clear advantages in mechanical performance and thermal stability. For foodservice customers, certification to recognized industrial composting standards is table stakes; for retail, durability and sensory parity with legacy plastic are differentiators.
-
Manufacturing footprint strategy: Reassess regional footprints in light of tariffs and logistics. Where duties materially raise landed costs, nearshoring or regional tolling arrangements can preserve competitiveness.
-
Regulatory posture and claims: Establish an audit-ready certification pipeline to avoid consumer and regulator pushback. Transparent labelling, third-party verification and conservative environmental claims reduce litigation and reputation risks.
-
M&A and partnerships: Buyers should prioritize deals that secure grade access, proprietary formulations or certified supply chains. Conversely, investors should prefer targets with validated performance claims and diversified end markets.
Scenario Framework — Preparing for Three Plausible Paths
For pragmatic planning, our model uses three scenarios driven by policy enforcement intensity, feedstock price trajectories and adoption rates among foodservice/retail customers. Under the base scenario — consistent with the 12% CAGR outlook — the market supports sustained premiumization of high-performance grades and a widening gap between certified suppliers and low-cost commodity peers. In an upside regulatory acceleration scenario, premium certified grades capture an outsized share of demand and vertical integration becomes a priority. Under a downside scenario with slower policy enforcement and prolonged feedstock inflation, cost competition intensifies and nearterm consolidation among converters accelerates.
Each scenario in the full report is paired with trigger points and recommended strategic moves (e.g., when to sign long-term resin contracts, when to accelerate CAPEX, when to pursue partnerships vs M&A). This enables leaders to convert observables (policy announcements, feedstock price inflection, capacity online dates) into actionable decisions.
How to Use the Full Report to Execute in 2026
-
Run the included Excel model in-house with your procurement and finance teams to stress-test price and volume assumptions against your product mix.
-
Use our supplier scorecard to shortlist partners for strategic offtakes and co-development projects; the scorecard ranks suppliers on grade availability, capacity timelines, certification footprint and contractual flexibility.
-
Adopt the compliance playbook to align product claims, packaging and end-of-life instructions with jurisdictional requirements, minimizing market access friction.
-
Leverage our M&A screening criteria to evaluate targets that provide immediate access to differentiated grades or certification credentials.
Note: the full PW Consulting report contains the granular regional and application-level splits, price-sensitivity worksheets, supplier-level benchmarking and downloadable decision dashboards that underpin the recommendations summarized here. We intentionally reserve those detailed tables for the full publication to preserve their strategic utility for subscribers and clients.
Concluding Recommendation
2026 will be a year of execution for firms in the PLA straw value chain. Companies that lock access to performance-differentiated grades, adopt robust feedstock risk mitigations, and align certification and claims with evolving regulatory expectations will secure durable competitive advantage. The market’s projected mid-term growth trajectory provides attractive value for investors and incumbents who move decisively — but success will hinge on the quality of execution, not simply on participation.
For decision-makers seeking to convert insight into action, PW Consulting’s full report supplies the quantitative models, supplier analytics and tactical playbooks necessary to set 2026 strategy with confidence. Visit our report page to download the complete study and receive the companion Excel model and implementation guide.
For detailed analysis of this topic, please visit the official page: Worldwide Polylactic Acid Straw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Palatal Expander Market Poised to Reach USD 1.29 Billion by 2032, Driven by an 8.15% CAGR
By pmarketresearch, 2026-07-15
Worldwide Palatal Expander Market — 2026 Strategic Preview
As palatal expansion transitions from a largely analog, appliance-driven therapy to a digitally enabled, multi-modal clinical pathway, executive teams must recalibrate product roadmaps, commercial models, and regulatory playbooks for 2026 and beyond. PW Consulting’s new market study (base year 2025; historical window 2020–2025; forecast 2026–2032) quantifies this transition and translates it into decision-grade guidance. At the macro level, the global palatal expander market is estimated at USD 745.5 Million in 2025 and is projected to reach approximately USD 1,290.13 Million by 2032, growing at a compound annual growth rate (CAGR) of 8.15% over the forecast period. These headline figures reflect accelerating adoption of digital workflows, emergence of removable 3D‑printed expanders, and expanding indications across age cohorts.
Worldwide Palatal Expander Market
Why this report matters for 2026 corporate decisions
-
Prioritize R&D investments with confidence — our scenario-driven forecasts identify where incremental product innovation (e.g., removable 3D-printed devices, miniscrew-assisted solutions, hybrid implant-supported systems) will deliver outsized commercial returns versus incremental engineering effort.
Worldwide Palatal Expander Market -
Shape regulatory and market-entry sequencing — by mapping country-level approval timelines and class determinations, the report helps firms time filings, clinical studies, and pilot launches while minimizing time-to-revenue risk.
Worldwide Palatal Expander Market -
Refine commercialization and channel strategy — we evaluate direct-to-clinic, lab-enabled, and distributor models against product types and practitioner preferences to guide salesforce sizing and partner selection for 2026 rollouts.
-
Design reimbursement and coding strategies — the study synthesizes billing pathways and CDT coding implications that materially affect adoption economics for orthodontists and payers.
-
Underpin M&A and investment decisions — a transparent market-concentration analysis, competitive mapping, and identified target archetypes enable rapid screening of acquisition candidates and bolt-on opportunities.
What the PW Consulting study contains (practical, executable content)
-
Market sizing and trajectory: an audited topline from 2020–2025 with a 2026–2032 forecast, sensitivity cases (conservative, base, accelerated) and embedded breakouts by product architecture, clinical workflow, and end-user cohort.
-
Competitive intelligence dossier: strategic profiles for major OEMs, labs, and digital entrants including product roadmaps, manufacturing footprints, channel footprints, and patent/clearing activity.
-
Regulatory playbooks: country-specific submission strategies, classification risk matrices, and pre-submission checklists designed to shorten regulatory cycles while safeguarding claims and labeling.
-
Reimbursement & economic models: practice-level cost/benefit models, payer negotiation outlines, and coding pathways (including how orthodontic appliance services are commonly billed under CDT frameworks) to accelerate uptake.
-
Go-to-market toolkits: package-level pricing playbooks, lab partnership term sheets, pilot design templates for clinical validation, and salesforce deployment models calibrated to different market scenarios.
-
M&A & partnership playbooks: valuation benchmarks, earn-out structuring options, integration checklists for digital dentistry assets, and prioritized target lists by strategic archetype.
Key dynamics shaping 2026 adoption
-
Digital disruption: the migration to intraoral scanning, CAD/CAM and direct 3D printing is not theoretical — it is now a commercial reality. New removable 3D‑printed expanders, integrated with scanner-enabled workflows and aligner treatment streams, are shifting clinical preference away from exclusively screw-centered fixed devices in certain patient segments.
-
Regulatory inflection points: recent device clearances and certifications are reducing regulatory friction for digitally manufactured expanders and modular systems. Notably, devices of this class are being handled under established orthodontic device classifications in mature markets; manufacturers should expect dossier requirements to emphasize biocompatibility, mechanical performance and, increasingly, software validation for CAD/CAM processes.
-
Clinical paradigm expansion: miniscrew-assisted solutions and hybrid implant‑supported approaches are enabling treatment of older adolescent and adult skeletal constriction cases with improved skeletal effects, changing both indication sets and average procedure economics.
-
Economics & reimbursement: billing pathways for expansion therapy are well established within orthodontic coding frameworks, but reimbursement variability across payers and geographies materially impacts case acceptance and pricing strategies — practices factor these dynamics into treatment planning and supplier choice.
-
Fragmentation with consolidation signals: while a substantial portion of the market remains distributed among regional suppliers and labs, leading manufacturers are leveraging platform advantages and regulatory clearances to consolidate share. Our concentration metrics confirm a market that is consolidating but not yet highly concentrated, implying continued white-space for focused innovators.
Competitive panorama — strategic takeaways
The competitive set is diverse: traditional orthodontic device manufacturers, specialized labs, and digitally native platform players each bring distinct strengths and go-to-market implications.
-
Align Technology — strategic implication: the commercialization of removable 3D‑printed palatal expanders integrated with intraoral scanners and aligner ecosystems changes the adoption calculus for clinicians who already use digital aligner workflows. Firms competing with or partnering to complement this model must demonstrate seamless digital integration and clear clinical differentiators.
-
Leone S.p.A. and Dentaurum — strategic implication: deep mechanical expertise and MARPE-capable components position these firms as go-to suppliers for clinicians prioritizing screw-based strength and modularity. Opportunity exists for collaboration on hybrid systems combining mechanical robustness with digital manufacturing efficiencies.
-
Regional OEMs and labs (DynaFlex, Forestadent, Ortho Technology, Great Lakes, ODL, RMO, American Orthodontics, Lancer, Ormco) — strategic implication: many established suppliers retain strong lab and clinician relationships. Their strengths in custom fabrication and distribution represent acquisition targets for digital entrants seeking scale or for OEMs seeking a service-enabled distribution layer.
-
Market structure note: our concentration analysis shows the top three players capture a mid-single-digit share concentration while the top five approach a near-majority influence in certain product niches. This configuration favors entrants that can rapidly scale partner networks or control differentiated IP.
Implications for core stakeholders
-
Manufacturers — prioritize modular product architectures that allow incremental feature upgrades (e.g., digital fittings, implant anchorage compatibility), and prepare global regulatory strategies that de-risk three market entry paths: EU/MDR, China (NMPA), and the U.S. FDA.
-
Investors & PE — the mid-market shows attractive tuck-in opportunities: diagnostics-to-therapy platform plays, digital lab networks, and component specialists with defensible supply relationships. Use the report’s valuation range bands and go/no-go triggers to expedite diligence.
-
Orthodontic labs — invest in ISO‑certified digital workflows to stay relevant as clinicians demand faster turnaround and digitally integrated appliances. Labs that combine precision fabrication with clinical services (trial fittings, hybrid solutions) capture higher per-case value.
-
Payers & health systems — the growing clinical differentiation among expansion modalities warrants targeted medical policy updates and pilot payment programs to capture long-term benefits where skeletal outcomes are demonstrably improved.
-
Clinicians — treatment planning must now balance mechanical efficacy, patient comfort, treatment duration, and billing pathways. Early adoption of digitally integrated expanders can improve workflow efficiency and patient experience where reimbursement aligns.
How to use this intelligence in 90/180/365-day plans
-
90 days: validate product claims and complete gap analysis against recognized regulatory predicates; initiate payer engagement in target geographies and finalize digital integration partners.
-
180 days: pilot in selected clinics using the report’s clinical trial templates; refine pricing and contractual terms with labs and distributors; prioritize capital allocation to manufacturing upgrades or strategic acquisitions.
-
365 days: scale commercialization in line with forecast scenarios; execute on M&A or partnership moves identified in the report; align global regulatory submissions to the sequenced launch plan that maximizes near-term revenue while protecting IP and clinical differentiation.
Next steps & how to access full intelligence
This executive preview outlines the strategic value of the full PW Consulting Worldwide Palatal Expander Market report for decisions you will make in 2026. The complete study contains granular segmentations, country-level regulatory timelines, product-level unit economics, and an actionable M&A pipeline tailored to different strategic objectives. For teams evaluating launches, acquisitions, or clinical partnerships, the full report functions as both a quantitative roadmap and a practical execution guide. Visit PW Consulting’s report page to access the full dataset, appendices, and downloadable toolkits that convert insight into repeatable action.
For detailed analysis of this topic, please visit the official page: Worldwide Palatal Expander Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Micronized Silica Market Reaches USD 680.58 Million in 2025, Poised to Expand at a 6.8% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Micronized Silica Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest market study positions micronized silica as a steadily expanding, strategically significant specialty chemical market. With the market valued at approximately USD 680.6 Million in the 2025 base year and a compound annual growth rate (CAGR) of 6.8% projected across the 2026–2032 forecast window, the sector presents a mix of near‑term operational risks and medium‑term commercial opportunities. By 2032, our topline projection points toward a market north of USD 1.0 billion—evidence that functional fillers and performance additives will remain core inputs across coatings, polymers, personal care, and adjacent industrial applications.
Worldwide Micronized Silica Market
Why this report matters for 2026 planning
- Actionable risk intelligence: The period ahead will be defined by cost volatility in feedstocks and logistics, evolving regulatory constraints on particle size in consumer sprays, and shifting trade policy — factors that materially affect sourcing, pricing, and product compliance strategies.
- Investment timing: The market data show a brief near‑term adjustment followed by resumed acceleration; this window is critical for calibrating CAPEX and contract timing for capacity expansions or brownfield upgrades.
- Commercial differentiation: Demand is moving toward specialty functional grades (hydrophobic, optical, low‑VOC, pharma‑grade). Differentiation through product formulation and certification is becoming the primary lever to capture premium margins.
Key macro takeaways (report highlights)
- The base‑year market (2025) is estimated at ~USD 680.6 Million (revenue units in Million USD). Forecasting to 2032, the market grows at a 6.8% CAGR to exceed USD 1 billion, underscoring persistent end‑use demand across industrial and consumer segments.
- Market concentration is moderate: the top three players account for a material share while the top five consolidate a majority portion of industry revenue—an environment that supports both scale advantages and niche specialist opportunities.
- Price and supply shocks have real operational impact. Sodium silicate feedstock prices rose materially late in 2025, ocean freight surcharges spiked following global disruptions, and trade tariff adjustments have altered the economics of import‑dependent supply chains.
What the full PW Consulting report delivers (practical, decision‑ready assets)
- Market sizing and forecasting (2020–2032), with scenario models that isolate demand drivers and price elasticity under alternate raw‑material and logistics stressors.
- Supply‑side diagnostics: capacity maps, utilization curves, cost‑of‑production benchmarking, and a supplier scorecard that captures technical capability, geographic exposure, and certifications.
- Regulatory and compliance playbook: implications of recent EU limits on ultrafine particles in consumer sprays, classification guidance for transport and handling, and a step‑by‑step certification checklist for pharma/food contact applications.
- Commercial tools: product portfolio matrices, go‑to‑market playbooks for premium vs. volume segments, customer segmentation, and negotiation templates for long‑term offtake and indexation clauses.
- Strategic M&A and partnership pipeline: target screening criteria, valuation sensitivities, and integration risks for bolt‑on acquisitions or technology partnerships.
- Data deliverables: interactive excel models, sensitivity dashboards, and anonymized transaction comps—designed so executives can stress‑test investment cases in under one week.
Competitive landscape — who matters and why
The market is a mix of global chemical majors and specialized mineral suppliers. Leading names in the competitive set include producers of fumed and precipitated micronized silicas, and companies that supply tailored grades for coatings, adhesives, pharmaceuticals, electronics, and polymer reinforcement. PW Consulting’s report includes deep profiles of leading manufacturers and technology players; below are capsule summaries of firms that will influence 2026 strategy:
Worldwide Micronized Silica Market
- Evonik Industries AG (Essen, Germany) — A global leader in fumed and precipitated silica, with recent capacity expansion to serve battery and pharma demand. Scale and technical R&D position Evonik to set performance benchmarks for high‑value grades.
- W.R. Grace & Co. (Columbia, MD, USA) — Known for specialty grades utilized in anti‑blocking, matting, and powder flow control. Certification efforts make Grace a preferred supplier for food and pharma formulations.
- PPG Industries (Pittsburgh, PA, USA) — Brings coatings know‑how and an emphasis on low‑VOC, performance matting grades; valuable for customers seeking integrated coating systems.
- Cabot Corporation (Boston, MA, USA) — Strong in rheology control and optical applications; recent hydrophobic grade launches signal a push into LED and optics markets.
- PQ Corporation, Innospec, Sibelco, Quarzwerke, Arkema, Imerys — Collectively these players round out a competitive ecosystem comprised of specialty silica producers, mineral integrators, and chemical formulators, each with differentiated channel access and industrial strengths.
Recent disclosed activities underline two concurrent dynamics: (1) capacity and product innovation to capture higher‑margin, high‑growth end uses (e.g., batteries, pharma, optics), and (2) certification and portfolio refresh to meet sustainability and regulatory demands.
Worldwide Micronized Silica Market
Operational headwinds and regulatory dynamics
- Raw‑material inflation: Sodium silicate feedstock prices rose notably in Q4 2025 — a cost input that passes through to many grades of micronized silica and compresses margins where pass‑through is limited.
- Logistics stress: Global ocean freight and shipping route disruptions added per‑ton surcharges in early 2025, materially affecting landed cost for export‑intensive suppliers.
- Trade policy shifts: Tariff changes on certain import routes have altered arbitrage economics for manufacturers with cross‑border supply chains.
- Health & safety regulation: Authorities have tightened rules on ultrafine particles in consumer spray products; manufacturers and formulators must align particle‑size distributions and label claims to remain compliant.
- Transport classification: Micronized silica is broadly classified as non‑hazardous for standard road/rail transport (with dust suppression expectations), but handling protocols must be enforced to meet downstream customer requirements.
Technology and application trends shaping winners
- Functional surface treatments and hydrophobization are driving uptake in electronics, optics, and specialty coatings.
- Particle engineering—balancing micronization with controlled agglomeration—enables better dispersion, rheology control, and tactile properties in consumer formulations.
- Cross‑industry migration: grades developed for industrial applications (e.g., matting in coatings) are being reformulated for personal care and pharmaceutical excipients, contingent on certification.
- Environmental performance: demand for low‑VOC, lifecycle‑verified additives is rising among OEMs and formulators seeking to meet sustainability KPIs.
How to act in 2026 — a pragmatic playbook
- Hedge and negotiate: Secure multi‑year contracts with feedstock suppliers, incorporate freight indexation clauses, and build optionality into procurement to blunt near‑term price shocks.
- Focus portfolio on margin density: Reallocate commercial efforts toward specialty grades where technical differentiation and certification create premium pricing power.
- Localize strategically: Assess near‑market capacity options or tolling partnerships to avoid tariff and freight penalties and support just‑in‑time supply to critical customers.
- Invest selectively in certification: Halal/Kosher, pharma‑grade, and low‑VOC validation can unlock new channels and higher mile‑per‑customer economics.
- Pursue bolt‑ons and partnerships: M&A can quickly fill technology gaps (e.g., surface treatments) and extend channel reach; use the report’s M&A filters to prioritize targets.
- Operationalize compliance: Implement particle‑size monitoring and labeling processes to mitigate regulatory risk in consumer spray products and related applications.
What we withhold here — and why you should download the full study
This briefing emphasizes strategic conclusions and practical next steps while deliberately withholding granular segment tables and confidential revenue splits that underpin our forecasting engine. The full PW Consulting report contains those confidential datasets—region‑by‑region and application‑level breakdowns, per‑grade pricing matrices, and supplier revenue estimates—presented in our interactive models so that commercial teams can run bespoke scenarios.
Next steps for executives
- Download the full report to access the interactive models and supplier dossiers required for detailed sourcing and investment decisions in 2026.
- Schedule a tailored briefing with PW Consulting’s micronized silica practice to translate market scenarios into a 90‑day tactical plan and a 36‑month strategic roadmap.
PW Consulting’s Worldwide Micronized Silica Market report is built to convert market intelligence into executable plans: from hedging and sourcing to product innovation and M&A. For 2026, companies that combine disciplined operational risk management with targeted product and certification investments will capture disproportionate share of the growth available in this evolving specialty‑chemical market.
For detailed analysis of this topic, please visit the official page: Worldwide Micronized Silica Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Sulfonated Polyethersulfone Market Set to Expand at an 8.51% CAGR Through 2032
By pmarketresearch, 2026-07-15
Sulfonated Polyethersulfone Market 2026 Strategic Brief: What Boardrooms Need to Know
PW Consulting’s latest market research — the Sulfonated Polyethersulfone (S‑PES) Market Report (base year 2025, forecast 2026–2032) — translates granular chemical‑polymer dynamics into board‑level decision levers for 2026. This briefing highlights the report’s strategic value to corporate leaders planning investment, product development, supply‑chain resilience, and M&A in the next 12–36 months. It intentionally demonstrates our analytical depth while reserving proprietary segment tables and unit‑level forecasts for subscribers who access the full report.
Sulfonated Polyethersulfone Market
Why this market matters in 2026
Sulfonated polyethersulfone has moved beyond a niche polymer curiosity to a commercially relevant hydrocarbon alternative in multiple membrane and ion‑exchange applications. Between 2020 and 2025 the global market expanded materially, and our modelling projects continued acceleration through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 8.51%. The market size grew from roughly USD 390 million in 2020 to USD 585.5 million by 2025, with our base scenario pointing toward a market that surpasses the USD 1 billion mark during the 2026–2032 forecast period.
Sulfonated Polyethersulfone Market
For leaders evaluating capital allocation in 2026, the message is clear: S‑PES is a growth polymer that sits at the intersection of membrane technology, industrial separations, and decarbonisation agendas. The macro trajectory justifies targeted pilots and selective upstream investments, but optimal timing and partner selection require more granular commercial and technical due diligence than public disclosures provide.
Sulfonated Polyethersulfone Market
Core market dynamics — distilled
- Demand drivers: accelerating demand for hydrocarbon‑based ion exchange membranes, intensified requirements for wastewater and industrial separations, and growing R&D activity in battery and electrochemical applications.
- Supply dynamics: a modest but rising production footprint, with industry indicators showing production volumes that remain constrained relative to conventional fluorinated counterparts, supporting favourable pricing dynamics and supplier leverage in early expansion phases.
- Regulatory and sustainability pressures: stricter environmental rules on polymer production and disposal are reshaping procurement preferences; S‑PES’s positioning as an alternative to perfluorinated sulfonic acid polymers is a strategic selling point for companies prioritising lower‑impact chemistries.
- Raw material and cost context: upstream intermediates such as diphenyl sulfone remain critical to feedstock security. Industry data suggest global S‑PES production was limited in 2024, with market participants transacting at premium per‑kilogram levels relative to mainstream engineering polymers — an important factor for price modelling and margin planning.
Competitive landscape: who’s shaping technology and supply
The S‑PES value chain is characterised by a mix of technology‑centric innovators and regional producers scaling product portfolios. Market concentration metrics indicate that the leading three players capture a meaningful but not dominant share of the market (CR3 ≈ 42.15%), while the top five firms together account for a larger portion (CR5 ≈ 58.8%). This structure creates space for differentiated technology plays, niche leadership, and strategic consolidation.
- Konishi Chemical Ind. Co., Ltd. (Japan) — technology‑led player advancing novel sulfonation chemistry. Konishi’s approach prioritises molecular weight retention during sulfonation (patented routes) and has delivered pilot‑scale material with a mid‑range sulfonation degree and high molecular weight characteristics. Their focus on antifouling membrane blends and ion‑exchange membranes for redox flow batteries positions them at the technology frontier; strategic partners should evaluate licensing, co‑development, or early off‑take to secure differentiated membrane feedstock.
- Monapoli Technology Co., Ltd. (China) — industrialised producer emphasising direct polymerisation routes to control both sulfonation degree and molecular weight, with processes claiming lower carbon intensity. For buyers seeking supply scale coupled with sustainability claims, Monapoli merits supplier qualification and process‑audit due diligence.
- SINKEN (Shanghai), Linyi Dechi, Shandong Jinlan — a cluster of Chinese firms supplying application‑focused S‑PES grades for antibacterial membranes, electrodialysis, and cation exchange membranes. These suppliers offer pragmatic access to product variants and are important tactical partners for regional manufacturers and membrane converters. Their presence also indicates a maturing domestic supply base that can compress lead times and enable aggressive product trials.
What PW Consulting’s report provides — practical, executable content
The full Sulfonated Polyethersulfone Market Report is structured to convert market intelligence into executable workstreams. Executives and strategy teams will find:
- Integrated demand scenarios (base, downside, upside) that model end‑market adoption across membranes, energy storage, and specialty separations — with sensitivity levers for feedstock price, environmental regulation, and technology substitution.
- Supply‑chain mapping and supplier scorecards designed for procurement — including audit checklists, carbon‑intensity indicators, and capacity ramp timelines for candidate suppliers.
- Technology risk matrices comparing sulfonation routes, molecular‑weight retention approaches, and process emissions — useful for R&D prioritisation and partner selection.
- Commercial playbooks for market entry and expansion: pilot design templates, sample contract terms (offtake, tolling), and go‑to‑market sequencing for membrane OEMs and chemical converters.
- Regulatory and lifecycle analysis (LCA) frameworks that translate environmental rules into compliance costs and product differentiation strategies.
- M&A and JV heatmaps that identify strategic targets and integration pitfalls, with valuation sensitivity to scale‑up CapEx and technology transfer risks.
To preserve the report’s value as a decision instrument, we present detailed segment tables, regional demand models, and supplier unit economics exclusively in the subscriber edition. The briefing here intentionally omits those raw segment figures while summarising their strategic implications.
Strategic imperatives for 2026
Based on our analysis, we recommend the following priority actions for executive teams considering exposure to S‑PES in 2026:
- Lock early access to differentiated feedstock. Prioritise partnerships or off‑take agreements with technology‑led suppliers for grades that retain high molecular weight after sulfonation — a material performance differentiator for membranes.
- De‑risk scale via staged capex and tolling. Use tolling agreements or co‑investment structures for initial production scale‑up to defer full capital commitment until clear product‑market fit is proven in targeted membrane applications.
- Embed sustainability claims into product roadmaps. Validate lifecycle assessments for low‑carbon polymer production and integrate these findings into supplier scoring and customer value propositions.
- Design pilots that focus on system‑level outcomes. Evaluate S‑PES not as a drop‑in polymer but as an enabler of membrane system performance (fouling resistance, ionic conductivity, lifetime). Pilot metrics should be aligned with end‑customer TCO, not only material properties.
- Monitor regulatory signals and position for substitution opportunities. Track jurisdictional moves away from perfluorinated chemistries; these create timing windows for S‑PES adoption, particularly where cost and environmental profiles align.
- Prepare an M&A playbook. Given the still‑moderate concentration profile, a deliberate acquisition or JV strategy can secure technology, capacity, or market access at attractive multiples relative to later consolidation phases.
Risks and mitigation
Key risks we highlight — and how to mitigate them:
- Feedstock volatility: secure dual sourcing and consider vertical integration for critical intermediates such as diphenyl sulfone.
- Technical scale‑up risk: validate sulfonation routes under production‑representative conditions and include acceptance criteria for molecular weight and sulfonation uniformity in supplier contracts.
- Regulatory reversal or alternative chemistries: maintain technology optionality by co‑investing in modular processing and by tracking competing ion‑exchange materials.
- Competitive price pressure: protect margin via differentiated grade development, service‑based contracts, and integrated membrane system offerings rather than commodity sales alone.
Data snapshot (macro figures)
Our modelling shows the global S‑PES market expanded from approximately USD 390 million in 2020 to USD 585.5 million in 2025, with an 8.51% CAGR projected across the 2026–2032 forecast window. Industry production volumes remain relatively limited at present, and market participants have transacted at elevated per‑kilogram levels consistent with constrained supply and specialised use‑cases. The top‑tier firms collectively account for a significant share of market sales, but fragmentation beyond the top five suggests opportunities for technology differentiation and strategic consolidation.
Next steps — how to convert insight into action
For companies planning board approvals, capital allocation, or partnership mandates in 2026, the full PW Consulting Sulfonated Polyethersulfone Market Report provides the executable intelligence you will need: segmented demand tables, supplier cost stacks, techno‑economic models, and negotiation playbooks. The report is deliberately designed to be used in commercial planning cycles and investment committees to shorten decision timelines while reducing execution risk.
Access the full report for comprehensive data, downloadable modelling templates, and supplier dossiers that include traceable sources and due diligence checklists. PW Consulting stands ready to support bespoke scenario modelling, supplier due diligence, and M&A execution planning informed by the dataset behind this briefing.
Contact PW Consulting to arrange a briefing, request the subscriber edition, or commission tailored strategic workstreams aligned with your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Sulfonated Polyethersulfone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com