

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Industrial Wiping Cloth Market to Reach USD 4,520.0 Million in 2025, Growing at 5.15% CAGR (2026–2032) as Asia‑Pacific and Non‑woven Segments Lead
By pmarketresearch, 2026-07-15
Worldwide Industrial Wiping Cloth Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s newly completed Worldwide Industrial Wiping Cloth Market report (base year 2025; historical 2020–2025; forecast 2026–2032) furnishes senior executives, procurement leaders, and strategic investors with an actionable view of a market that is simultaneously mature in its core use cases and dynamic at the technology, sustainability, and service-model edges. Our analysis shows the industry transitioning from commodity-driven volume play toward differentiated value streams—driven by materials innovation, circular-economy practices, and service-led models. This preview explains why the report is essential to shaping 2026 strategies without disclosing the granular segment tables reserved for the full publication.
Worldwide Industrial Wiping Cloth Market
Market at a Glance: Macro Trajectory and Structural Signal
The global industrial wiping cloth market was valued at approximately USD 4,520.0 Million in 2025. Under PW Consulting’s base-case forecast, the market expands at a compound annual growth rate (CAGR) of 5.15% over the 2026–2032 forecast horizon, reaching an estimated USD 6,423.97 Million by 2032. The immediate step-up into 2026 is visible—reflecting ongoing recovery in key end-use industries and the layered impact of sustainable-material uptake and service innovations.
Worldwide Industrial Wiping Cloth Market
Two structural signals underpin our outlook. First, market concentration is low: the three-largest suppliers account for roughly 18.4% of revenue and the five-largest about 26.5%, indicating a fragmented competitive landscape. Second, the mix of raw materials and channels is evolving—nonwoven technologies, recycled textile streams, and service-based rental/managed-supply models are redefining value capture.
Worldwide Industrial Wiping Cloth Market
Why this report matters to 2026 corporate agendas
- Procurement optimization: Buyers face margin pressure and supply volatility in fiber and polymer markets. Our report quantifies sensitivity of supplier cost models to shifts in raw-material inputs and provides tactics (contracting levers, dual-sourcing templates, vendor scorecards) to protect margins and continuity.
- Product & manufacturing strategy: The transition from cotton rags to engineered nonwovens and microfiber blends is not just technical—it reshapes capital intensity, yield, and environmental reporting. We map technology-readiness, CAPEX implications, and regulatory exposure so manufacturers can prioritize retrofit versus greenfield investments.
- Commercial differentiation: Service models—rental, managed wiper programs, and certified recycled-product lines—create recurring revenue and higher gross margins. The report evaluates go-to-market frameworks and partner ecosystems required to operationalize those models at scale.
- M&A and portfolio planning: With a fragmented base and concentrated pockets of technical capability, there are clear roll-up targets and bolt-on opportunities to create capabilities in engineered wipes, contamination control, and rental services. Our target-screening framework and valuation overlays are tuned to 2026 transaction dynamics.
What PW Consulting’s report delivers (practical, implementable content)
- Transparent market-sizing and scenario-based forecasts (2026–2032) with sensitivity testing for raw-material price shocks and end-market demand shifts.
- Go-to-market playbooks for four archetypal suppliers: commodity-volume distributors, engineered-wipe specialists, rental/managed-service providers, and low-cost exporters.
- Procurement toolkit: RFx templates, supplier segmentation heatmaps (by reliability, cost, sustainability), and a three-step rapid supplier-audit protocol.
- Cost-to-serve and margin model templates that connect fabric type, processing route, and logistics to unit economics—enabling quick scenario testing in board-level discussions.
- Sustainability roadmap: pathways for integrating post-consumer recycled textiles, manufacturing-efficiency KPIs, and third-party certification implications for public tenders and enterprise buyers.
- Regulatory and standards primer reflecting industry discussions at recent trade fora (World of Wipes, Clean Show), and implications for manufacturing controls and labeling.
- Competitive benchmarking, including vendor strengths, channel positions, and service portfolios—designed to support vendor selection and partnership decisions.
Competitive landscape: strategic takeaways on core players
The market is populated by a mix of long-established regional manufacturers, technical specialists, family-owned distribution groups, and export-oriented OEMs. A selective read on several influential players presents the shape of competition and partnership opportunity:
- Carolina Textiles (United States) — A Southeast U.S. incumbent with depth in manufacturing and wholesale distribution across automotive, marine, and janitorial channels. Strengths: distribution density, established OEM and maintenance accounts, and inventory scale. Strategic implication: acquisition of regional distributors or investments in traceability systems could expand service-led offerings.
- Berkshire Corporation (United States) — Positioned in engineered wipes and controlled-environment applications. Strengths: technical product development, high-value customers in critical manufacturing. Strategic implication: an attractive partner or acquisition target for buyers seeking contamination-control capabilities.
- U.S. Wiping Company, A&A Wiping Cloth, Wi-Supply, Wipeco, Anchor Wiping Cloth (United States) — A cluster of resilient regional players focused on absorbent, durable wipes and rapid fulfillment. Strengths: customer intimacy, flexible production, and legacy supplier relationships. Strategic implication: these firms are prime candidates for digital-commerce upgrades and managed-supply platform integration.
- Kleenrags, JEENOR, SYSBEL (China) — Export-focused manufacturers leveraging cost-efficient production and scale in nonwoven and heavy-duty wiping products. Strengths: price competitiveness and engineering for heavy-grease or high-absorbency applications. Strategic implication: Western buyers will balance cost benefits with nearshoring, quality assurance, and carbon/traceability considerations.
- Lindstrom Group (Finland) — Differentiated through a rental/managed-service model with regular pickup and replacement. Strengths: strong service-oriented value proposition and ESG credentials via reuse and centralized laundering. Strategic implication: rental-as-a-service is an increasingly defensible margin pool for suppliers willing to invest in logistics and textile-care infrastructure.
Market dynamics shaping winners and losers in 2026
- Raw-material evolution: The basket of commonly used fibers—cotton rags, polyester, spunlace nonwovens, airlay, and meltblown polypropylene—remains core. However, suppliers that secure low-cost, certified post-consumer recycled feedstocks or that can demonstrate higher-performance nonwoven blends will command premium placement.
- Sustainability and circularity: Recycled textiles are increasingly cascaded into wiping applications. Buyers are demanding traceability and life-cycle assessments as part of procurement. Suppliers who can offer validated recycled-content products and closed-loop service models will win large enterprise contracts.
- Standards and technical differentiation: The industry’s technical axis—from engineered wipes for semiconductors to heavy-duty rags for metalworking—creates distinct procurement bands. Participation and thought leadership at industry conferences (e.g., World of Wipes, Clean Show) is becoming a competitive necessity for firms that compete on specification.
- Fragmentation-led M&A: Low top-line concentration suggests consolidation upside. Buyers should expect opportunistic bolt-ons in 2026–2027 as acquirers pursue scale, geographic coverage, and technical niches.
Actionable strategic recommendations for 2026
- For buyers/procurement heads: Execute a two-track sourcing strategy—secure tactical cost relief via diversified sourcing while piloting managed-supply or rental programs with providers that can demonstrate LCA improvements.
- For manufacturers: Prioritize modular investments that enable flexible switching between cotton, recycled fibers, and engineered nonwovens; add small-scale pilot lines for high-margin engineered wipes rather than wholesale capital expansion.
- For investors/M&A teams: Target vertical scopes that add contamination-control expertise, service logistics, or recycled-textile feedstocks. Use PW Consulting’s valuation templates to stress-test synergies under raw-material price volatility.
- For service innovators: Double down on rental and managed-supply operations in de-risked verticals (food & beverage, healthcare laundry) and pair with certification programs to penetrate enterprise procurement frameworks.
Methodology and confidence framework
The report synthesizes primary interviews with industry participants, supply-side manufacturing audits, trade-show intelligence (including insights from World of Wipes and Clean Show events), and bottom-up costing models calibrated to publicly available financials and supplier data. We provide probabilistic scenario bands to reflect macroeconomic variance, raw-material shocks, and technology-adoption curves so executives can stress-test capital and commercial plans.
Next steps: how to use the full report in your 2026 planning cycle
- Download the executive summary to validate headline forecasts and concentration metrics, then book a PW Consulting briefing to walk through the segment-level tables and supplier scorecards (these are intentionally excluded from this public preview).
- Commission a 12-week readiness assessment if you are contemplating a managed-supply launch, nearshoring initiative, or targeted acquisition—PW Consulting’s implementation teams will translate the report’s strategic findings into an operational roadmap.
- Use the procurement toolkit and cost models included in the full report to run three supplier-sourcing scenarios and present board-ready outcomes by Q3 2026.
PW Consulting’s Worldwide Industrial Wiping Cloth Market report is calibrated for leaders who require both market visibility and practical execution plans. The market’s macro trajectory—from roughly USD 4.5 billion in 2025 toward more than USD 6.4 billion by 2032 at a 5.15% CAGR—creates multiple strategic inflection points in 2026. If your 2026 planning includes supply-chain redesign, product differentiation, sustainability commitments, or M&A, this report is structured to convert insight into measurable action. For the complete data tables, supplier-level benchmarks, and proprietary scenario models, please visit our report page or contact our industry practice to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.85% CAGR for Worldwide External Power Supplies Market (2026–2032) Amid Robust Asia Pacific Demand
By pmarketresearch, 2026-07-15
Worldwide External Power Supplies (EPS) Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide External Power Supplies (EPS) synthesizes five years of historical performance (2020–2025) and a seven‑year forecast (2026–2032) into a pragmatic roadmap for commercial, product and policy decisions in 2026. With the EPS market estimated at USD 12,200 Million in the base year (2025) and projected to expand at a compound annual growth rate (CAGR) of 5.85% through 2032—reaching just over USD 18.16 Billion—our analysis pairs quantitative modelling with hands‑on commercial playbooks. This press briefing highlights why the research is strategically essential for boardrooms, procurement teams, product planners, and M&A specialists, while preserving the report’s proprietary subsegment tables and granular datapoints for subscribers.
Worldwide External Power Supplies (EPS) Market
Why this report matters in 2026
- Macro clarity in an uncertain year: The EPS market has rebounded materially since 2020 and is on a multi‑year growth trajectory. That trajectory is uneven across channels and applications, and navigating it requires more than headline growth rates—it requires operational scenarios, component risk scoring, and supplier capability maps that our report provides.
- Regulatory inflection points: New and updated energy‑efficiency and ecodesign requirements in major jurisdictions are changing product compliance roadmaps. Our work translates regulatory timelines into product release and inventory decisions to avoid market access disruptions.
- Actionable vendor intelligence: With a moderately fragmented supplier landscape (CR3 ≈ 28.5%; CR5 ≈ 38.2%), selecting partners or acquisition targets depends on a nuanced understanding of technological differentiation, certification breadth, and manufacturing footprint—precisely the dimensions the report benchmarks.
Market trajectory and what is driving growth
At the aggregate level, the EPS market demonstrates steady expansion: the 2025 market size (USD 12,200 Million) is projected to rise to roughly USD 13,546 Million in 2026 and to exceed USD 18.16 Billion by 2032 under our central case. The 5.85% CAGR through the forecast window masks several structural forces that are shaping opportunity and risk.
Worldwide External Power Supplies (EPS) Market
- Efficiency and standards: Global energy‑efficiency standards remain a primary demand driver. Compliance with established DOE requirements and recently adopted EU ecodesign rules is prompting OEMs to accelerate design upgrades and certification programs.
- Product complexity and new topologies: Adoption of GaN and other advanced power semiconductors is enabling higher power density and lower system losses, shifting design win dynamics toward suppliers who can commercialize these technologies at scale.
- Channel and application shifts: Demand patterns are evolving across consumer, networking, medical and industrial end markets. Each channel has distinct purchasing cadences, warranty expectations and certification burdens that change supplier selection criteria.
- Supply chain and geopolitics: Component lead times and allocation volatility persist, and geopolitical tensions continue to inject uncertainty into sourcing strategies—making dual‑sourcing, regional buffer inventory, and inventory hedging operational imperatives.
Regulatory and policy developments that change the playbook
- United States: In April 2026, the U.S. Department of Energy issued revisions that relax certain reporting requirements for exempt consumer EPS under the EPS Service Parts Act. Although the change simplifies compliance burden for specific legacy product categories, DOE energy‑efficiency standards remain binding for most modern EPS designs. Manufacturers and OEM purchasers must reconcile reporting simplifications with continuing efficiency obligations.
- European Union: The EU’s Regulation 2025/2052, adopted in late 2025 and coming into force in December 2028, tightens ecodesign requirements for external power supplies and portable chargers. Firms targeting EU markets should calibrate product roadmaps and certification timelines now to avoid costly redesigns or delayed listings in Q4 2028 and beyond.
Strategic implications for 2026 — what boards and functional leaders should do now
- Product and R&D leaders: Prioritize modular architectures and semiconductor roadmaps that allow platform upgrades for efficiency and safety certifications without full redesigns. Use the report’s technology adoption curves and certification lead‑time models to schedule development sprints that align with EU and DOE deadlines.
- Procurement and supply chain: Translate the report’s supplier capability maps into dual‑source strategies for critical components, and implement dynamic safety stock models based on our component risk scoring. Shorten lead‑time exposure by qualifying local assembly partners in priority markets where trade tensions may affect logistics.
- Commercial and pricing: Reassess product portfolios for margin dilution risks from higher certification and compliance costs. Our report includes price elasticity scenarios and channel mix sensitivity analysis that help pinpoint where premium pricing for efficient EPS is acceptable and where cost absorption is unavoidable.
- M&A and partnerships: Given the market’s moderate concentration, acquisitions and strategic alliances remain viable routes to obtaining technology or capacity quickly. Use our proprietary target screening framework to prioritize candidates by certification portfolio, GaN capability, and regional manufacturing resilience.
Competitive landscape — who matters and why
The market is characterized by a mix of global OEMs, niche specialists, and vertically integrated suppliers. Our competitive analysis benchmarks companies on product breadth, certification reach, advanced topology adoption, manufacturing footprint and channel strength. Highlights from the vendor universe include:
Worldwide External Power Supplies (EPS) Market
- Delta Electronics (Taiwan): A broad global manufacturer with strengths in high‑efficiency AC‑DC EPS for IT, industrial and medical applications. Delta’s emphasis on DOE Level VI and EU ecodesign compliance positions it strongly where regulatory requirements are most exacting.
- Lite‑On Technology (Taiwan): Known for compact, high‑efficiency designs that serve computing and communications markets; Lite‑On’s engineering focus on density and thermal performance is a competitive differentiator where space and weight matter.
- Mean Well Enterprises (Taiwan): A specialist in switching power supplies, with an extensive EPS portfolio for industrial and medical segments; Mean Well’s depth in open‑frame and enclosed adapters makes it a go‑to for project engineering teams.
- XP Power (UK): Focused on medical and industrial high‑reliability EPS; recent product introductions in 2026 (new PGW/PGD series) underline XP Power’s strategy of targeted product launches to capture high‑margin subsegments.
- CUI Inc. (US), Phihong (Taiwan), Chicony, Acbel, Salcomp, TDK‑Lambda (Japan), Artesyn (Emerson), FSP Group, Adapter Technology, and UNIFIVE (Japan): Each brings complementary strengths—global certification networks, PoE and networking‑focused EPS, mobile charger expertise, and emerging GaN implementations. Adapter Technology’s explicit work on GaN and high‑density designs is notable for customers seeking next‑generation solutions.
Collectively, these suppliers form a landscape where specialization and certification depth often win design‑ins, rather than scale alone. That dynamic is reflected in the market’s concentration metrics: while a number of large players exist, a significant portion of demand is served by smaller or specialized vendors—creating avenues for targeted partnerships or bolt‑on acquisitions.
What’s inside the full PW Consulting report (practical deliverables)
Beyond the headline growth figures, the report delivers operational tools and datasets designed for immediate action:
- Market model and scenarios: A transparent spreadsheet model covering base, upside and downside cases for 2026–2032, sensitive to price, component availability and regulatory shocks.
- Supplier scorecards: Comparative matrices that grade manufacturers by certification portfolio, GaN readiness, production flexibility and lead‑time performance.
- Regulatory timeline and gap analysis: Practical checklists and Gantt charts for compliance programs tied to DOE and EU implementation dates.
- Channel and pricing playbooks: Recommended commercial strategies for consumer, networking, medical and industrial routes‑to‑market with sample P&L impacts under different pricing strategies.
- Component risk register: Prioritized list of critical components, alternate sources, and suggested inventory buffers to mitigate allocation risks.
- M&A screening and valuation templates: Criteria and valuation sensitivities tailored to EPS targets and technology acquisitions.
- Executive presentations and board‑ready one‑pagers: Condensed decision materials to accelerate approval processes and resource allocation.
How senior leaders should use this intelligence in 2026
- Turn growth into strategically aligned investments: Use the market model to allocate R&D budget toward platforms that will remain compliant and competitive through 2028–2030 regulatory windows.
- Mitigate supply risk proactively: Implement the report’s dual‑sourcing and inventory playbooks to maintain production continuity amid component allocation volatility and geopolitical pressure.
- Prioritize certification-leading suppliers: Wherever market access and safety liability matter—medical, industrial and networking—choose partners with demonstrable certification pipelines and testing capacity.
- Use targeted M&A to acquire capability fast: For companies missing GaN expertise or specialized medical compliance, an acquisition can compress time‑to‑market; our M&A toolkit shows how to size and value such deals.
Trailer principle — what we’re not publishing here
This briefing intentionally refrains from publishing the report’s granular subsegment tables—regional splits, output‑power band revenues, and application‑level figures are omitted to preserve the proprietary value of the dataset and to encourage informed engagement. The full report contains detailed time‑series for each subsegment, scenario spreadsheets, and supplier transaction histories that are essential for transaction diligence and product roadmap planning.
Next steps and how to obtain the full analysis
For executive teams preparing budgets, procurement cycles or M&A agendas in 2026, this study is designed to convert market insight into actionable decisions. PW Consulting offers tailored briefings, supplier workshops, and scenario modelling sessions based on the report. To access the complete dataset, proprietary subsegment breakdowns, and the operational toolkits described above, please visit our report page or contact our advisory team to schedule a strategy session.
PW Consulting remains available to support boards, product leaders and deal teams in converting EPS market growth—estimated at a 5.85% CAGR through 2032—into defensible, revenue‑generating decisions while managing the compliance, technology and supply‑chain risks that define the next phase of industry competition.
For detailed analysis of this topic, please visit the official page: Worldwide External Power Supplies (EPS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 7.58% CAGR for Worldwide Canine Mammary Tumor Treatment Market in 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Canine Mammary Tumor Treatment Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Canine Mammary Tumor Treatment Market delivers a focused, practice-oriented assessment designed to inform board-level strategy, R&D prioritization, and commercial execution through 2032. This briefing offers an executive synthesis of the report’s most consequential findings—highlighting growth trajectories, competitive dynamics, technology inflection points, and pragmatic actions that animal health and veterinary service leaders should consider in 2026. To preserve the investigative depth that underpins our recommendations, detailed segment-level tables and proprietary financial models are intentionally reserved for the full report.
Worldwide Canine Mammary Tumor Treatment Market
Macro snapshot: a market on a sustained expansion path
Our baseline, anchored to 2025 as the base year, shows a market that has expanded materially over the past half‑decade and is set for continued, mid‑single‑digit to high‑single‑digit growth through the next planning cycle. Specifically, the global market for canine mammary tumor treatment rose from under USD 600 million in 2020 to roughly USD 845.5 million in 2025. Under our central scenario the market grows at a compound annual growth rate (CAGR) of approximately 7.58% over the 2026–2032 forecast window, reaching just over USD 1.4 billion by 2032.
Worldwide Canine Mammary Tumor Treatment Market
Drivers behind this trajectory include demographic trends in pet ownership, higher owner willingness to invest in advanced care, accelerating adoption of precision diagnostics and targeted therapies in veterinary oncology, and the growing availability of high‑end radiotherapy and interventional services in specialty centers. These dynamics are complemented by translational research that leverages canine mammary tumors as comparative models for human breast cancer—creating a two‑way flow of innovation that benefits both industries.
Worldwide Canine Mammary Tumor Treatment Market
What the 2026 strategic agenda should prioritize
- Evidence generation as commercial foundation: With surgery remaining the gold standard for most presentations and adjuvant systemic options largely used off‑label or in high‑risk cases, the single most valuable investment for product teams and service providers is robust, veterinary‑specific clinical evidence. Expect regulatory advantage for companies that can pair clinical efficacy with well‑documented quality‑of‑life and recurrence outcomes.
- Precision diagnostics and targeted deployment: Genomic and biomarker‑driven approaches are moving from academic curiosity to clinical utility—enabling more targeted use of tyrosine kinase inhibitors, immunomodulators, and other systemic options. Companies that integrate testing, consultative services, and outcome tracking will capture disproportionate value.
- Service model diversification for veterinary practices: Referral networks, hub‑and‑spoke radiotherapy offerings, and capital‑light service partnerships (e.g., mobile or visiting specialist models) will be important for clinics seeking to retain complex cases locally while controlling investment risk.
- Regulatory strategy tuned to veterinary realities: Recent regulatory pathways such as Minor Use in Major Species (MUMS) designations are materially impactful. Firms that align trial designs with veterinary endpoints and pursue regulatory incentives can convert promising molecules into commercially differentiated products faster and with greater uptake.
Report contents: practical tools for immediate action
PW Consulting’s full study provides hands‑on assets that leadership teams can implement in 90–180 day cycles, including:
- Demand models and scenario‑based revenue projections to support R&D and investment prioritization across the 2026–2032 forecast period.
- Clinical evidence roadmaps—trial designs, endpoint recommendations, and sample-size guidance—to accelerate label expansion or veterinary indication claims.
- Pricing and reimbursement playbooks benchmarked to clinic economics, including procedure cost ranges and sensitivity analyses for owner affordability versus clinic margin.
- Technology adoption frameworks for imaging, precision radiotherapy, and molecular diagnostics that translate capital investments into utilization and revenue metrics.
- Competitive intelligence dossiers with actionable M&A target screening criteria and partner selection matrices focused on biotech, device, and service businesses.
Competitive landscape — who matters and why
The competitive environment combines established animal health leaders, oncology‑focused biotechs advancing veterinary indications, device manufacturers supplying precision radiotherapy, and a growing cohort of specialty service providers. Market concentration is moderate: the top three competitors account for a meaningful share of market value while the top five capture a clear majority—indicative of an industry where scale, distribution, and clinical footprint matter.
- Zoetis Inc. remains a strategic bellwether due to its portfolio depth and the clinical role of established targeted therapies in multi‑modal protocols. Its distribution network and veterinary relationships make Zoetis a first mover for commercialization programs tied to companion diagnostics and supportive care bundles.
- Boehringer Ingelheim Animal Health and Elanco bring legacy animal health capabilities and inorganic growth playbooks; their scale supports broad outreach and potential rollup strategies for oncology assets and services.
- Specialist biotechs (AB Science, Karyopharm, VetDC, CureLab) are advancing novel mechanisms—tyrosine kinase inhibitors, nuclear export inhibitors, and p62‑based immunotherapies—that could reshape systemic treatment choices if supported by veterinary trial data and favorable regulatory outcomes.
- Precision medicine and service players (FidoCure, PetCure Oncology) are shifting the delivery model: genomic testing and centralized radiosurgery services reduce the barrier to advanced care and create recurring revenue streams through service subscriptions or case‑by‑case referrals.
- Device vendors (Accuray, Varian/Siemens Healthineers) are important partners for specialty hospitals and referral centers investing in high‑precision radiotherapy; their technology decisions influence case mix and referral patterns.
Recent industry moves with strategic implications
- Regulatory momentum: AB Science’s recent MUMS designation for masitinib (early 2026) illustrates how targeted regulatory pathways can de‑risk veterinary oncology approvals and expand on‑label opportunities. Companies should assess MUMS and similar incentives as a core element of product development strategy.
- Surgical and imaging innovation: Ongoing work on intraoperative Optical Coherence Tomography (OCT) highlights a step‑change opportunity to improve surgical margins and reduce recurrence—this has direct implications for equipment suppliers, surgical training programs, and perioperative service bundles.
- Cost and access signals: Clinic‑level treatment costs remain a key constraint on uptake for advanced therapies; surgical procedures typically dominate immediate expenditures, and owner willingness to pay is strongly influenced by perceived survival benefit and quality‑of‑life outcomes.
Strategic recommendations for 2026 corporate plans
- Prioritize veterinary evidence for translational candidates: If your pipeline includes molecules with cross‑species oncology potential, invest early in veterinary trial infrastructure and KOL engagement. Veterinary‑specific endpoints and owner‑centric outcomes materially accelerate commercial uptake.
- Bundle diagnostics and therapy: Create integrated offerings where genomic testing or intraoperative imaging is sold together with therapy or service‑level agreements. Bundling reduces owner friction and increases lifetime value per patient.
- Consider asset transactions and partnerships: Given moderate market concentration and the high cost of building specialty services, acquisitive moves or strategic alliances with service providers (e.g., radiation networks, genomic platforms) offer faster access to established referral pipelines.
- Adopt a differentiated go‑to‑market for clinics: Tailor sales and training programs to the economic realities of primary veterinary hospitals versus specialty referral centers; different packaging and financing options will drive higher conversion.
- Monitor regulatory incentives closely: Align registrational programs with mechanisms like MUMS to accelerate market entry and capture premium pricing for hard‑to‑treat indications.
What PW Consulting delivers beyond this preview
This preview synthesizes the strategic implications of the market’s macro growth and competitive shifts. The full PW Consulting report is a working tool for commercial leaders and investors—it includes the complete dataset, segmented demand curves, product‑level uptake models, clinic economics dashboards, competitor heatmaps, and executable 12–36 month roadmaps. It also offers bespoke scenario modeling support tailored to M&A diligence, investor presentations, or board strategy sessions.
To preserve the commercial value of our primary research and modeling, detailed segment breakouts and company‑level financial estimates are available exclusively in the full report. We intentionally limit the granularity shown here to stimulate action and direct interested parties to the complete deliverable.
Next steps
- Schedule a briefing with PW Consulting to review the interactive models and discuss custom scenarios for your organization.
- Commission targeted diligence if you are evaluating acquisitions, licensing, or pilot partnerships in veterinary oncology.
- Request the full report for access to proprietary segmentation, clinic‑level pricing modules, and competitor valuations that underpin our recommendations.
For organizations positioning for growth in the evolving canine mammary tumor treatment landscape, 2026 is a pivotal year to convert scientific promise into commercially viable solutions. PW Consulting’s full report equips decision‑makers with the evidence, economic clarity, and strategic roadmaps necessary to capitalize on the market’s projected expansion. Visit our report page to obtain the comprehensive analysis and data packages required to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide IR Carbon Sulphur Analyzers Market to Expand at 4.85% CAGR Through 2032, Report Finds
By pmarketresearch, 2026-07-15
Worldwide IR Carbon Sulphur Analyzers Market: Strategic Insights for 2026 Decision‑Makers
Executive Preview — PW Consulting Market Brief
The IR Carbon Sulphur (C/S) analyzers market is entering a decisive phase where product differentiation, consumables control, and targeted application strategies will determine competitive winners. PW Consulting’s latest market study synthesizes historical performance (2020–2025) and a robust forecast (2026–2032) to equip senior executives, corporate development teams, and product leaders with the context and strategic options necessary to act in 2026.
Worldwide IR Carbon Sulphur Analyzers Market
Market Trajectory and Forecast
Key macro dynamics are clear: demand for infrared combustion-based carbon and sulfur analyzers has shown steady expansion through the first half of the decade. The global market grew from USD 383.12 Million in 2020 to USD 485.50 Million in 2025. As technologies mature and addressable applications broaden beyond traditional metallurgy into adjacent industries, our model projects continued expansion — with the market forecast to reach USD 676.36 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. Early forecast years show incremental growth (USD 502.83 Million in 2026), accelerating as new application pull and after‑sales revenues scale.
Worldwide IR Carbon Sulphur Analyzers Market
For decision-makers, these topline dynamics matter because they signal a market that is neither hyper‑disruptive nor saturated: predictable demand with pockets of high strategic upside. That combination favors targeted investment and disciplined go‑to‑market plays rather than broad, undifferentiated expansion.
Worldwide IR Carbon Sulphur Analyzers Market
Why This Report Matters for 2026 Strategy
- Actionable forecasting calibrated to execution timelines: our 2026–2032 forecast aligns with typical product development and commercialization cycles, allowing companies to plan R&D, manufacturing capacity, and channel investments with confidence.
- Commercial levers prioritized: the report connects hardware sales to higher-margin recurring revenue streams (consumables, accelerators, crucibles, service contracts) and quantifies the potential uplift from service-centric business models.
- Risk-adjusted scenario planning: we present alternative market paths under different adoption and raw-material scenarios, enabling finance and strategy teams to stress-test capital allocation decisions.
Competitive Landscape and Technology Differentiators
The IR C/S analyzer sector remains anchored by established instrument vendors and a spectrum of regional players. The competitive set can be grouped by technology approach and go‑to‑market focus:
- High-frequency induction furnace specialists with NDIR (infrared) detection — focused on speed, throughput, and inorganic solids performance. Notable vendors emphasize high-temperature induction combustion and fast cycle times for metals, alloys, and refractory materials.
- Dual‑mode and resistance furnace providers — targeting versatility across organic and inorganic matrices via combined furnace architectures and tailored detection chains.
- Value-oriented regional suppliers — competing on cost, local service, and customization for captive industrial buyers in regions with strong manufacturing bases.
Representative competitor positioning (high‑level):
- HORIBA, Ltd. (Kyoto, Japan): Known for the EMIA series spanning entry to flagship models, HORIBA emphasizes reliability, user ergonomics, and upgrades for handling challenging, moisture‑bearing samples. Recent documentation updates reinforce throughput and operator experience advantages.
- ELTRA GmbH (Haan, Germany): Differentiates with hybrid furnace designs (induction + resistance) enabling broad sample compatibility. The ELEMENTRAC portfolio expansion signals a push into adjacent elemental analytics and laboratory consolidation plays.
- LECO Corporation (St. Joseph, Michigan, USA): A long-established vendor with a wide application remit; recent communications highlight application optimization for cement and process control, underlining an execution focus on industrial process analytics beyond metallurgical labs.
- Elementar, Bruker, Labtron, Torontech, BIOBASE, JIEBO: Each brings positional strengths—speed, detector specialization, low‑concentration accuracy, regional service networks, or cost leadership—that shape segment dynamics.
Notable recent moves underscore evolution in competitive tactics: LECO’s early‑2026 emphasis on cement applications reflects a play to capture process analytics in high‑volume industrial settings; HORIBA’s 2025 EMIA refresh reinforces product usability and sample‑handling reliability; ELTRA’s portfolio extension in 2025 signals continued platform diversification. These activities show a market balancing incremental product improvement with targeted application expansion rather than radical technology substitution.
Supply Chain, Consumables and Operational Risks
Beyond analyzer hardware, consumables and sample preparation inputs represent a meaningful and often under‑appreciated profit pool — and a strategic vulnerability. Ceramic crucibles and tungsten or tungsten‑tin blend accelerators remain standard consumables across major instrument families. High‑purity tungsten accelerators (commonly specified at particular grain sizes) are critical to guaranteeing complete combustion in high‑frequency induction systems. Our supply‑chain analysis highlights three implications for 2026 planning:
- Consumables as lock-in: service and consumables programs are a reliable margin driver and a defense against pure hardware commoditization. Firms that design proprietary consumable formats or tight service bundles can capture recurring revenue and improve customer retention.
- Supply concentration risk: key raw materials (tungsten alloys, high‑grade ceramics) have geographically concentrated supply and are exposed to trade policy and price volatility. Procurement teams should consider multi‑sourcing, strategic inventory, or vertical partnerships for critical accelerators and crucibles.
- Cost pass‑through sensitivity: OEMs with thin hardware margins must model scenarios where consumable cost increases cannot be fully absorbed, and plan commercial tactics (multi‑year contracts, hedging) accordingly.
Regulatory and Substitution Considerations
The IR combustion analyzer market faces both regulatory and technological headwinds/opportunities. Environmental monitoring and emissions testing requirements can expand demand for robust sulfur analysis, whereas innovations in non‑combustion elemental techniques (e.g., advanced XRF, laser‑based analyzers) present substitution threats in niche use cases. The net effect through 2032 is gradual growth with pockets of accelerated adoption where combustion IR retains clear accuracy or throughput advantages.
Report Contents — What You’ll Find Inside
PW Consulting’s full market report is structured for decision-making and immediate operational use. Key components include:
- Detailed market model (2020–2032) with scenario sensitivity and topline drivers mapped to commercial KPIs.
- Methodology appendix describing demand drivers, addressable applications, and model assumptions — enabling reproducibility and internal re‑calibration.
- Competitive profiles and product benchmarking that compare furnace architectures, detection subsystems, sample throughput, and typical TCO components.
- Consumables and supply‑chain risk analysis, supplier mapping, and a supplier‑risk heatmap focused on tungsten and ceramic inputs.
- Go‑to‑market playbooks for OEMs, distributors, and service providers covering pricing strategies, channel design, after‑sales programs, and OEM vs. third‑party consumable economics.
- M&A and partnership opportunities: screening criteria, target archetypes, and valuation sensitivity for bolt‑on acquisitions or strategic alliances.
Note: In keeping with our “trailer” approach, the executive preview intentionally highlights the report’s structure and the strategic questions it answers while reserving proprietary segmentation depth and granular revenue splits for the full report.
Strategic Recommendations for 2026
Based on our analysis, we advise companies to prioritize three pragmatic moves in 2026:
- Double down on consumables and services: launch or harden multi‑year consumable contracts and service plans. Capture more of the installed base’s lifetime value rather than competing solely on hardware price.
- Target adjacent industrial applications with tailored value propositions: adapt existing combustion platforms for process analytics in high‑volume industries (e.g., cement, specialty chemicals, battery materials) where throughput and ruggedness justify premium positioning.
- Hedge supply risk and rationalize sourcing: secure long‑lead purchases for tungsten accelerators and high‑performance crucibles, and evaluate vertical integration or strategic supply partnerships for critical inputs.
For R&D and product teams, incremental innovation that improves sample throughput, moisture tolerance, and low‑concentration detection will yield outsized commercial returns. For commercial teams, bundling analytics software, diagnostics, and remote monitoring into service packages will raise switching costs and stabilize margins.
How PW Consulting Can Support Your Investment and Execution
PW Consulting offers tailored advisory services to convert the report’s insights into executable plans. Our engagements typically include:
- Targeted due diligence for M&A, including complementary product fit and consumables revenue accretion analysis.
- Go‑to‑market redesigns for tiered channel strategies, pricing frameworks, and industrial vertical plays.
- Supply‑chain resilience programs focused on critical consumables and component sourcing optimization.
- Commercial pilots and value‑capture roadmaps to convert installed‑base customers into subscription and service revenues.
Concluding Thought
The IR Carbon Sulphur analyzer market in 2026 presents a strategic choice: pursue scale through low‑margin hardware competition, or build differentiated, service‑anchored positions that leverage consumables and application specialization. PW Consulting’s Worldwide IR Carbon Sulphur Analyzers Market report provides the numbers, scenario tools, and competitive intelligence needed to make that choice with conviction. For access to the full data set, granular segmentation, and actionable financial models, consult the complete report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide IR Carbon Sulphur Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wood Briquettes Market to Surge from USD 925.4 Million in 2025 to USD 1.52 Billion by 2032 at a 7.35% CAGR — Europe Leads with USD 431.3M
By pmarketresearch, 2026-07-15
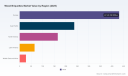
Worldwide Wood Briquettes Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As the global energy transition continues to elevate low-carbon solid fuels, wood briquettes are emerging as a strategically important commodity for industrial heat, residential heating, and decentralized power applications. Our latest market model shows the Worldwide Wood Briquettes Market expanding from USD 634.82 Million in 2020 to USD 925.4 Million in 2025, and tracking toward USD 1,520.34 Million by 2032, at a compound annual growth rate (CAGR) of 7.35% across the 2026–2032 forecast window. For 2026 specifically, the market is set to pass the USD 1,000 Million threshold, presenting an inflection point for producers, buyers and investors.
Worldwide Wood Briquettes Market
Why this preview matters for 2026 strategy
- Timing: 2026 is a pivotal year where capex cycles, policy windows and supply constraints align. Firms that move in 2026 set capacity, offtake and sourcing patterns that will determine competitiveness across the rest of the decade.
- Risk-reward horizon: Moderate near-term growth, driven by demand for cleaner heating solutions, masks structural opportunities in logistics optimization, feedstock aggregation and premium fuel positioning.
- Decision clarity: The dataset behind this preview isolates the macro trajectories you need to validate plant expansions, M&A targets, and commercial partnerships — while preserving granular segment detail for subscribers to our full report.
Market dynamics shaping strategic options
Three dynamics will disproportionately influence outcomes in 2026 and beyond:
Worldwide Wood Briquettes Market
- Feedstock economics and availability.
Feedstock cost volatility is a practical constraint for producers. For example, sawmill residues and wood chips averaged around €28 per cubic meter in parts of Europe in Q4 2023 — a signal that local raw-material arbitrage will remain a core margin lever. Firms that secure long-term supply agreements, vertical integrate with sawmills, or develop multi-feedstock processing capability will be best positioned to protect margins if raw-materials tighten.
Worldwide Wood Briquettes Market - Policy and standards as market multipliers.
Regulatory regimes are bifurcating markets. The EU’s renewable energy framework now requires solid biomass to demonstrate substantial greenhouse gas savings versus fossil alternatives — a material eligibility criterion for many industrial buyers. Simultaneously, standards such as DIN 51731 (limits on ash and fines) and market certifications (ENplus A1 pricing benchmarks) are shifting procurement toward higher-quality, traceable briquettes. Producers who invest in certification and demonstrable lifecycle GHG performance unlock premium channels and public-sector tenders.
- Commercialization and pricing dynamics.
Retail reference prices for premium briquettes (ENplus A1) ranged in the low hundreds of euros per tonne during recent heating seasons, underlining clear consumer willingness to pay for quality and consistency. Combined with subsidy programs in mature markets (for example, grants for biomass boiler upgrades), demand elasticity for certified products is improving — but so are expectations on delivery, carbon accounting and product consistency.
Competitive landscape — what the leading players signal
The wood briquettes sector remains structurally fragmented, with a mix of regional champions and specialized exporters. Several corporate archetypes stand out and are relevant to 2026 strategy:
- Premium residential specialists — Companies focused on high-density briquettes for stoves and fireplaces are capitalizing on brand, retail reach and product certification. These players are the natural owners of premium retail channels.
- Sawmill-integrated producers — Firms with upstream access to sawmill residues achieve lower feedstock cost and higher margin resilience. They are also better placed to scale capacity quickly, as illustrated by European capacity expansions announced in recent annual reports.
- Export-oriented commodity suppliers — Some manufacturers emphasize volume and logistics efficiency to serve industrial boilers and export markets; their playbook centers on price competitiveness and supply chain reliability.
Key industry participants exemplify these archetypes. Several market-leading manufacturers have invested in capacity expansions, product certification and niche product lines in the past two years. Recent movements include facility capacity increases to meet regional demand surges and updated certifications for new product lines — both actions demonstrate the dual importance of scale and quality credentials.
Supply chain, cost structure and operational levers
Operational competitiveness in 2026 will be decided by three executional levers:
- Feedstock aggregation and logistics optimization. Centralizing feedstock sourcing across multiple mills and investing in blended-feedstock dryers reduces margin exposure. Companies that piloted hub-and-spoke collection models in 2023–2025 now report smoother kilning schedules and lower per-ton transport cost.
- Certification and product specification control. Meeting standards on ash content and fines is not just compliance — it is a commercial asset. Certification opens access to institutional buyers and subsidized boiler programs, improving both price and contract stability.
- Asset flexibility and modular capacity additions. Given feedstock variability and demand seasonality, modular presses and mobile briquetting lines provide attractive payback profiles for firms targeting multiple markets or pilot product lines.
Regulatory and commercial headwinds — what to watch in 2026
- Implementation rules under climate legislation (including lifecycle GHG thresholds) will directly affect eligibility of briquettes in renewable energy portfolios. Companies must prepare robust lifecycle analyses to defend product claims.
- Subsidy programs that support biomass heating create localized demand spikes; firms should map incentive timelines into commercial forecasts and tender pipelines.
- Standards enforcement — such as ash and fines limits — will compress the viable supplier pool for premium channels, raising the bar for quality control across the supply chain.
Strategic playbook for executives — actionable recommendations for 2026
Below are prioritized actions that translate the market view into executable strategies. Each is anchored to the timelines and scenarios most likely across 2026.
- For producers planning capacity expansion:
- Adopt a staged-capacity approach: prioritize modular expansion that can be scaled as offtake contracts crystallize.
- Secure multi-year feedstock contracts with price collars to mitigate raw-material swings and ensure continuity during heating seasons.
- Design product lines with certification pathways in mind; earn those certificates early to attach price premiums and long-term contracts.
- For buyers and industrial consumers:
- Waterfall procurement: segment suppliers by certification, delivery reliability and carbon disclosure rather than price alone.
- Lock in multi-year supply with flexibility clauses for quality tolerance and seasonal storage to reduce logistics risk.
- For investors and M&A teams:
- Target bolt-on acquisitions that add feedstock control or certifications; prioritize assets in logistics-constrained geographies where scale leads to durable cost advantages.
- Value optionality: invest in firms with modular capacity and established retail channels to capture both B2B and B2C margin pools.
What PW Consulting’s full report delivers (high-level)
This strategic brief distills macro trends and actionable guidance. The full Worldwide Wood Briquettes Market report — built from a bottom-up modeling approach, expert interviews, primary supplier surveys and scenario stress-tests — provides the operational detail needed for a 2026 go/no-go decision, including:
- Proprietary demand forecasts by market and application through 2032, with sensitivity scenarios tied to policy and feedstock shocks.
- Financial model templates (unit economics, break-even, and build vs. buy cases) that you can adapt to specific plant sizes and feedstock mixes.
- Detailed competitive benchmarking and supplier scorecards, with vetted profiles and recent commercial developments to support target screening.
- Regulatory mapping, certification pathways and checklists for meeting lifecycle carbon thresholds required in major markets.
- Practical go-to-market playbooks for premium retail channels, industrial offtake sales, and export logistics optimization.
To preserve the "trailer" value of this release, we have intentionally withheld the granular regional and application splits from this preview. Those core segmentation tables, along with downloadable datasets and model files, are available in the full report.
Concluding perspective — the 2026 opportunity window
With the market poised to exceed the USD 1,000 Million mark in 2026 and maintain a mid-single-digit annual expansion into the next decade, executives have both time and urgency. Timing matters: decisions made in 2026 will determine access to premium channels, shape feedstock arrangements, and lock in cost structures for years. Companies that move on certification, feedstock integration, and flexible capacity now are best placed to capture the majority of upside as demand matures and regulatory clarity firms.
Next steps
- Download the full Worldwide Wood Briquettes Market report to access the complete segmentation, downloadable financial models and supplier scorecards.
- Schedule a strategic briefing with PW Consulting’s biomass practice to translate the findings into a bespoke 90-day implementation plan.
As the report’s lead analyst and your strategic advisor, I welcome the opportunity to walk your team through the scenarios and operational templates designed specifically for 2026 decision cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Wood Briquettes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Nuclear-Grade LED Lighting Market Valued at USD 385.5 Million in 2025, Poised for Robust Expansion Through 2032
By pmarketresearch, 2026-07-15
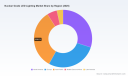
Worldwide Nuclear Grade LED Lighting Market — Strategic Preview from PW Consulting
PW Consulting today releases a strategic preview of its new market research report, Worldwide Nuclear Grade LED Lighting Market (Base year 2025). The report synthesizes proprietary data, supplier discovery, regulatory mapping and scenario modelling to equip C-suite and procurement leaders for higher-confidence decisions in 2026 and beyond. This press release highlights the report’s strategic value and selected directional findings while preserving the detailed segmentation tables and model outputs for report subscribers.
Worldwide Nuclear Grade LED Lighting Market
Market trajectory at a glance
-
Market context: The global nuclear-grade LED lighting market has moved into a steady-growth phase following infrastructure refresh cycles in the early 2020s. Our analysis shows a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast horizon.
Worldwide Nuclear Grade LED Lighting Market -
Scale: Using 2025 as the base year, the market is sized in the mid-hundreds (USD Million). Under our central scenario the market expands materially by 2032, reflecting a mix of new-build nuclear projects, life-extension retrofits, and regulatory-driven emergency-lighting upgrades.
Worldwide Nuclear Grade LED Lighting Market -
Structure: Competitive concentration is moderate — the top three suppliers account for roughly 39% of industry revenue while the top five approach the low-50s percent range — indicating that specialist vendors maintain strong domain positions while meaningful share remains available to agile entrants and regional suppliers.
Why this report matters for 2026 decision-making
2026 will be a pivotal year for organizations that must align capital plans, safety upgrades and supply-chain resilience. The report is intentionally designed as a practical decision tool rather than an academic compendium. Key strategic utilities for stakeholders include:
-
Procurement clarity — our interactive TCO models reconcile capital costs, radiation-side failure modes, maintenance cycles, and decontamination logistics so buyers can compare lifecycle cost outcomes across solution architectures (integrated-driver, LOCA-compatible, pool-rated, etc.).
-
Regulatory alignment — consolidated certification matrices map IEEE-344 seismic requirements, 10CFR50 Appendix B quality-program implications, IEC 62954 environmental-control interfaces and gamma-dose endurance thresholds so engineering teams can accelerate compliance planning for retrofit scopes and new-build specifications.
-
Risk-tested scenarios — scenario analysis incorporates supply-chain stress-tests (component lead times, specialized stainless-steel housings, and radiation-tolerant semiconductors), helping asset owners quantify schedule risk and buffer inventory needs under alternative project-timing assumptions.
-
Vendor selection playbook — procurement playbooks and scoring templates in the report convert technical and regulatory requirements into procurement-ready RFP language and vendor evaluation checklists tailored to containment, pool, hot-cell and waste-management environments.
What the report contains (practical deliverables)
-
Market sizing and forward financial models with sensitivity ranges for pace of nuclear new-build, SMR deployments, and life-extension projects.
-
Regulatory and testing compendium summarising gamma testing protocols, LOCA compatibility methods, seismic qualification practices and NRC-aligned quality-program requirements—all cross-referenced to product design implications.
-
Competitive intelligence dossiers for leading vendors, including capability maps, manufacturing footprints, certification pedigrees and recent product developments.
-
Procurement instruments: RFP templates, technical acceptance tests (TATs), inspection checklists and spare-parts optimization models that materially reduce specification ambiguity and change-order risk.
-
Operational playbooks that link lighting choices to maintenance windows, ALARA (As Low As Reasonably Achievable) practice, and decontamination procedures to minimize dose exposure during interventions.
Competitive landscape — who matters and why
The nuclear lighting sector remains specialist-driven; longevity in the market is strongly correlated with in-country testing credentials, documented radiation-tolerance history, and the ability to deliver purpose-built housings and driver solutions. Our report profiles a curated set of industry players and assesses their strategic posture.
-
DITO Lighting d.o.o. — Slovenian specialist known for ultra radiation-resistant H-, N- and L-series luminaires with integrated drivers and LOCA compatibility. Recent product upgrades (notably the U-50 evolution and an L-series technology unification) demonstrate a focus on mechanical robustness, thermal management and safety-mode features that matter in containment applications.
-
Luminos Nuclear (Nanocut d.o.o.) — strong testing pedigree, including high-dose gamma validation, and in-house production of mechanical, LED and driver subsystems. Their stainless-steel and emergency-variant offerings are engineered for environments where component-level traceability is required.
-
Ahlberg Cameras — Swedish provider of radiation-tolerant LED lighting with proven products for pool and hot-cell illumination, suited to surveillance and maintenance-focused lighting needs.
-
BIRNS, Inc. — US-headquartered supplier with high-ceiling floodlights and seismically qualified emergency fixtures; demonstrates the integration of high-dose component selection with structural qualification to IEEE-344.
-
AO Sosny R&D Company — Russian specialist producing radiation-resistant lighting for hot cells and canyons; notable where hot-cell specific power envelopes and form factors are required.
-
G&G Industrial Lighting — US manufacturer of accelerator-tolerant compact fixtures featuring zero-maintenance design, highlighting a market niche where long mean-time-between-maintenance (MTBM) is a procurement priority.
-
Homewood Energy Services — offers nuclear-grade emergency lighting under NRC-aligned quality programs, emphasising battery chemistry choices and seismic resilience for US market compliance.
-
Martek Lighting and LED Lighting Supply — provide customized and lifecycle-focused solutions that bridge nuclear and broader power-generation requirements, focusing on regulatory conformity and maintenance reduction.
Regulatory and technical dynamics shaping supplier selection
Engineering teams must orient product choices to a tightly-coupled set of performance criteria. Our report collates these into practical decision levers:
-
Radiation tolerance — validated gamma-dose endurance and component selection for driver-less architectures or driver-internal designs to avoid external shielding complexities.
-
LOCA compatibility and decontamination — enclosure finishes, gasketing strategies and drain/vent designs that preserve performance while permitting rapid cleaning and dose-control procedures.
-
Seismic and emergency illumination performance — compliance with IEEE-344 and emergency illumination duration expectations (commonly specified in the field between 24–40 hours) drive fixture mounting and battery strategy decisions.
-
Quality-program credentials — for US projects, adherence to 10CFR50 Appendix B-aligned quality systems materially reduces procurement friction and schedule risk.
Strategic implications and recommendations for 2026
For vendors
-
Invest in certified gamma-testing and LOCA validation paths. Demonstrable test data accelerates qualification windows for utilities and research facilities.
-
Differentiate with service models: extended spares pools, vendor-managed inventory near major sites, and on-call dose-reduction maintenance crews can win retrofit contracts where outage time is the key constraint.
-
Expand modularity: configurable optics and sealed-driver options reduce variant proliferation for buyers and compress acceptance testing cycles.
For asset owners and system integrators
-
Prioritise lifecycle-cost RFPs over simple unit-price procurement. The report’s TCO templates show how small up-front premiums for radiation-hardened components and maintenance-free batteries can yield multi-year service-cost savings.
-
Map lighting upgrades to planned outages and life-extension programs to capitalize on existing mobilization efforts and reduce incremental outage days.
-
Harmonize procurement specifications with regulatory expectations—explicitly call out seismic and emergency-illumination performance, LOCA compatibility and EMC requirements to avoid rework during qualification.
How to use this preview
This document is a strategic preview that highlights the report’s practical applicability for 2026 planning cycles. PW Consulting’s full report contains the detailed financial models, segmentation matrices, vendor scorecards and procurement artifacts that are intentionally withheld here to preserve commercial value and to drive direct engagement with subscribing organizations.
To access the complete dataset, including downloadable vendor dossiers, certification evidence maps and the interactive TCO model, visit the PW Consulting report page or contact our research team. Subscribing organizations receive onboarding support to tailor the report’s tools to their engineering specifications and procurement calendars.
Closing perspective
The nuclear-grade LED lighting market is maturing from bespoke, site-by-site procurements to a more standardized market where proven testing, documented quality systems and lifecycle service propositions are decisive. For decision-makers in 2026, the ability to translate regulatory nuance and radiation-testing results into procurement-ready specifications will separate successful programs from costly delays. PW Consulting’s report is constructed to be the operational bridge between regulatory compliance, technical validation and procurement efficiency — enabling smarter, faster decisions during the next critical phase of industry investment.
For detailed analysis of this topic, please visit the official page: Worldwide Nuclear Grade LED Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Waterproof Phone Pouch Market Set to Grow at a 5.8% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-07-15
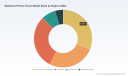
Worldwide Waterproof Phone Pouch Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new Worldwide Waterproof Phone Pouch Market report (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the market-level intelligence and executable frameworks needed to set strategy in 2026. The market is on a moderate expansion path, sustaining a compound annual growth rate of 5.8% across the forecast horizon. In revenue terms, the global market measures in the mid‑hundreds of USD Million in 2025 and is projected to approach the high‑six‑hundreds USD Million by 2032. These topline dynamics, when combined with fragmentation metrics and supply‑side pressures, create a rich set of strategic inflection points for product, pricing, sourcing and M&A decisions in the coming 12–18 months.
Worldwide Waterproof Phone Pouch Market
Market trajectory and what it means for 2026 planning
The waterproof phone pouch category is moving beyond episodic, weather‑driven demand to more consistent, multifunctional adoption. While the market’s near‑term growth is steady rather than explosive, the underlying quality of demand is improving as consumers and professional users prioritize device protection, integrated services (e.g., power integration), and certified performance. For strategy teams, the key numeric anchors are: a stable CAGR ~5.8% through 2032 and a clear upward revenue path from the 2025 base. These anchors should be used as conservative planning bases for 2026 budgets—supporting targeted R&D, select product line investments, and supply‑chain hedging rather than broad, high‑risk expansion.
Worldwide Waterproof Phone Pouch Market
Why this market matters to product, commercial and corporate strategy in 2026
-
Product roadmaps: The category is maturing around technical certifications and integrated features (e.g., battery integration, higher IP ratings). R&D roadmaps should prioritize certification readiness, ergonomics and multi‑use functionality rather than trivial aesthetics.
Worldwide Waterproof Phone Pouch Market -
Channel and GTM: Growth is uneven across channels and occasions. 2026 GTM plans should favor channel mixes that combine mass retail for price entry points with specialist outdoor and professional channels for premium, higher‑margin SKUs.
-
Sourcing & cost management: Material and labor inflation are active tail risks. Immediate sourcing strategies should include multi‑sourcing, longer hedging windows for polymer inputs, and near‑term cost pass‑through playbooks.
-
M&A and partnerships: With industry concentration low (the three‑firm and five‑firm concentration ratios indicate a fragmented field), M&A can be used to buy capability—certified design, channel access or manufacturing scale—rather than pure market share. Small, targeted acquisitions are likely to deliver strategic upside in 2026.
Competitive landscape — what to watch in 2026
The category remains fragmented. Our concentration metrics show a low top‑tier concentration, indicating numerous regional and niche players. For 2026, firms with strong certification track records, integrated product capabilities, and resilient supply chains will outpace peers.
-
Pelican Products (Torrance, CA) — recognized for heavy‑duty Protector and Vault series pouches with high IP ratings and recent buoyancy‑focused product extensions. Pelican’s focus on marine & professional use cases positions it to capture premium segments where certification and durability carry price premiums.
-
OtterBox (Fort Collins, CO) — continues to leverage channel strength and brand equity. Recent product showcases signal intent to remain compatible with leading smartphone launches and to emphasize premium design in mainstream retail.
-
Lifeproof (Costa Mesa, CA) — with recent certification gains on advanced product variants (e.g., integrated battery pouches), Lifeproof is pushing into value‑added device protection that blends power and protection—an area ripe for premium monetization.
-
Catalyst — pursues IP68 performance and time‑limited submersion guarantees, offering a proposition that appeals to safety‑conscious buyers and professional users requiring documented performance.
-
China‑based OEMs (examples include Syncwire, Miady, Hiearcool) — continue to supply high‑value, price‑sensitive channels and white‑label opportunities. Their strengths are cost competitiveness and rapid SKU turnover—critical levers for retailers and private‑label manufacturers.
Taken together, incumbent premium brands and agile OEM suppliers form two distinct competitive playbooks: brand‑driven premiumization versus cost‑driven scale. 2026 winners will combine selective premium bets with disciplined cost-to-serve controls.
Supply‑side dynamics and regulatory risk
Three supply‑side pressures deserve immediate attention:
-
Raw material volatility: Polymer price shocks have raised baseline input cost for typical pouch materials. Procurement teams should assume a higher price floor and implement staged hedging or indexing arrangements to lock predictable margins into 2026.
-
Regulatory constraints: EU chemical rules now require phthalate‑free PVC for consumer pouches. This forces product reformulation and potential SKU rationalization for Europe‑facing lines. Regulatory compliance timelines should be integrated into 2026 product launch calendars and cost models.
-
Labor cost and on‑shoring tradeoffs: Rising manufacturing wages in key coastal manufacturing hubs have increased the landed cost of assembly. Companies should evaluate near‑shoring, automation, and value‑engineering to protect gross margins without sacrificing product quality.
In addition, the safety recall history for zipper seal failures under standard testing underlines the commercial and reputational risk of quality lapses. Product teams must embed third‑party testing and traceable QC into every SKU introduced in 2026.
Practical contents of the report — what PW Consulting delivers (preview)
The report is structured to be immediately operational for 2026 planning cycles. Highlights include:
- Market model with historicals (2020–2025) and a bottom‑up forecast (2026–2032) that isolates demand drivers and sensitivity to price, weather patterns and device replacement cycles.
- Fragmentation and concentration analysis with CR metrics, competitive positioning maps and capability heatmaps for incumbent and emerging players.
- Cost‑to‑serve and input cost model incorporating polymer pricing scenarios, labor cost trajectories and freight assumptions to stress‑test margin scenarios.
- Regulatory impact assessment and compliance timelines (including EU chemical regulation implications) with downstream cost and reformulation playbooks.
- Channel and pricing playbooks for mass retail, specialist outdoor, professional OEM and direct‑to‑consumer strategies, including sample KPIs and near‑term test & learn experiments.
- Actionable M&A screening: target archetypes, valuation multipliers by capability, and a stepwise integration checklist for 100–300 SKU bolt‑on deals.
- Risk register and contingency options (supplier disruption, certification failures, sudden raw material spikes), with sample contractual clauses and inventory buffers.
Note: While this press preview outlines themes and topline market metrics, the report contains granular regional, application and SKU‑level forecasts and a competitor benchmarking matrix that are intentionally not disclosed here. Access to the full dataset and models is available via the report landing page.
How to use the report in 2026 strategic cycles
-
Board and investor briefings: Use our topline revenue trajectory and concentration metrics to justify capital allocation and to set realistic top‑line assumptions in 2026 budgets.
-
Product and R&D planning: Map product roadmaps to certification and regulatory timelines in the report to avoid costly last‑minute redesigns.
-
Sourcing decisions: Apply the input cost scenarios to select a mix of multi‑sourcing, longer‑term contracts and near‑shoring pilots to hedge against polymer and wage inflation.
-
M&A screening and JV negotiation: Use the provided target archetypes and valuation guide to prioritize bolt‑on acquisitions that accelerate certification capability, channel access, or manufacturing adjacency rather than stand‑alone market share buys.
-
Commercial pilots: Implement split‑tests across channel partners using the playbooks and KPIs in the report to validate pricing elasticity and cross‑sell opportunities in 90‑day sprints.
Conclusion — a 2026 playbook in preview
The waterproof phone pouch market presents a pragmatic growth opportunity: predictable topline expansion coupled with meaningful margin and regulatory complexity. For 2026, the strategic imperative is not to chase scale alone but to align product certification, supply resiliency, and channel specialization. Brands that act early on compliance reformulation, embed third‑party testing, and adopt disciplined procurement hedges will convert steady market growth into sustainable margin improvement.
Next steps
PW Consulting’s full report contains the confidential segmentation tables, regional and application forecasts, and downloadable financial models that underpin the recommendations summarized here. To obtain the complete dataset, competitor benchmarking, and actionable templates for 2026 implementation, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Waterproof Phone Pouch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Niraparib Market Poised for Rapid Expansion — Forecasted 12.43% CAGR Through 2032
By pmarketresearch, 2026-07-15
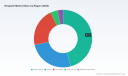
Worldwide Niraparib Market — Strategic Briefing for 2026 Decision‑Makers
As healthcare systems, biopharma leaders, and investors plan for an accelerated oncology landscape in 2026, niraparib occupies a strategic nexus: an established PARP inhibitor with expanding clinical footprints, concentrated commercial control, and an evolving regulatory and diagnostic ecosystem. PW Consulting’s latest Worldwide Niraparib Market report synthesizes historical performance, forward‑looking scenarios, and operational playbooks to convert market intelligence into executable decisions. This press briefing outlines the report’s strategic value while preserving the granular segment-level data that subscribers access in the full deliverable.
Worldwide Niraparib Market
Why niraparib matters for 2026 strategy
-
Clinical momentum: Niraparib has moved beyond its origins in ovarian cancer into prostate and other solid tumor settings through regulatory approvals, combination regimens, and companion diagnostics. These clinical extensions materially alter addressable populations and payer conversations.
Worldwide Niraparib Market -
Commercial maturity with growth runway: The niraparib market demonstrates both established revenues and robust forecast expansion—PW Consulting’s model estimates the global market at USD 1,180.5 Million (base year 2025) and projects sustained growth at a compound annual growth rate (CAGR) of 12.43% over the 2026–2032 forecast window.
Worldwide Niraparib Market -
High concentration, high impact: The market’s competitive structure is tightly concentrated, creating strategic implications for pricing, access, and partnership maneuvers by new entrants and existing incumbents.
Market trajectory at a glance
Our market model traces rapid expansion from a documented historical base (noting strong compound growth between 2020 and 2025) to a near‑doubling of total market value across the 2026–2032 forecast horizon. This trajectory is driven by three structural forces: regulatory broadenings of labeled indications, companion diagnostic adoption improving patient selection, and combination therapy approvals that increase per‑patient treatment value.
PW Consulting’s integrated forecasting framework combines epidemiology, treatment adoption curves, pricing scenarios, and reimbursement modeling to produce forward estimates. The model is fully auditable and scenario‑ready—enabling decision‑makers to stress test market outcomes under alternative regulatory, payer, and competitive assumptions.
What the full report delivers (practical, actionable content)
-
Dynamic market model: A downloadable financial model (USD, revenue unit: Million) with transparent assumptions and adjustable levers for indication mix, penetration rates, price erosion, and diagnostic uptake. The model supports scenario runs for conservative, base, and upside forecasts aligned to the 2026–2032 horizon.
-
Commercial playbooks: Region‑agnostic tactics for market access, formulary negotiations, and launch sequencing tailored to different payer archetypes. These are paired with templated economic arguments and health‑economics briefings to accelerate reimbursement submissions.
-
Competitive and partner maps: Strategic assessments of originators, licensees, API suppliers, and potential biosimilar entrants. Each profile includes go‑to‑market strengths, potential vulnerabilities, and suggested engagement strategies for licensors, partners, and contract manufacturers.
-
Manufacturing & supply chain playbook: Practical guidance on API sourcing, GMP qualification priorities, dual‑sourcing strategies, and contingency planning for capacity bottlenecks—critical in a high‑value oral oncology market.
-
IP and regulatory timeline analysis: Integrated timelines for primary composition and formulation protections, anticipated generic entry windows, and strategic options around lifecycle management and patent settlements.
-
Investment & M&A intelligence: Deal screening matrices, valuation sensitivities (to pricing, uptake, and patent lifespan), and prioritized opportunity lists for bolt‑on acquisitions or licensing to accelerate geographic expansion.
-
Diagnostic & companion test strategy: Practical frameworks for co‑development, lab network rollout, pricing, and payer positioning of companion diagnostics that materially affect niraparib adoption and value capture.
Competitive landscape — what to watch
The niraparib ecosystem is shaped by a small number of strategic owners, diversified licensees, and a global set of API manufacturers. Key players profiled in the report include:
-
GlaxoSmithKline plc (GSK) — Originator of ZEJULA (niraparib): Holds primary global commercialization rights across multiple indications and remains the central commercial force. Strategic focus areas include lifecycle management, label optimization, and diagnostic co‑promotion.
-
Janssen Biotech, Inc. (Johnson & Johnson) — Prostate cancer commercialization: Holds rights (outside Japan) to niraparib in prostate cancer and is advancing combination regimens that expand the addressable population and per‑patient treatment duration.
-
Zai Lab Limited — Regional commercialization partner: Represents a localization pathway in Greater China through licensure, signaling preferred routes for market entry in complex access environments.
-
Takeda Pharmaceutical Company Limited — Japan rights holder: Demonstrates the importance of legacy licensing arrangements and the need for tailored local strategies in markets with distinct regulatory and reimbursement dynamics.
-
API and contract suppliers (e.g., Biophore, Teva/TAPI, Dr. Reddy’s, and selected Chinese manufacturers): Their capabilities influence pricing, supply security, and the feasibility of aggressive launch scenarios—especially for generic or locally manufactured versions.
Notably, market concentration metrics indicate that the top three and top five players control an overwhelming share of commercial activity. This concentrated structure creates both barriers and opportunities: barriers for late entrants seeking broad coverage, but opportunities for focused partnership strategies, niche indication plays, and differentiated diagnostic linkages.
Recent regulatory and market developments that reshape 2026 choices
-
Regulatory expansion in prostate cancer: Recent agency decisions broaden the labeled use of niraparib combination regimens, materially increasing the marketable population and shifting payer negotiation dynamics.
-
Companion diagnostic approvals: The authorization of companion diagnostics for niraparib in targeted ovarian cancer populations enhances value‑based contracting potential but demands integrated diagnostic commercialization plans.
-
Label and lifecycle updates: Originator label revisions and lifecycle actions influence clinician adoption, patient selection, and comparative value positioning versus other PARP inhibitors.
-
Commercial performance signals: Public reporting from originators provides revenue benchmarks that inform valuation and competitive benchmarking—information fully contextualized in the report’s financial overlays.
-
IP timelines: Core patents extend into the late 2030s for several jurisdictions; the timing and scope of patent expiries remain a critical strategic input for licensing, generics planning, and targeted investments.
Strategic implications and decision points for 2026
-
Market access & pricing strategies: With growing indication breadth and diagnostic‑driven patient selection, companies must balance list pricing with innovative risk‑sharing and outcomes‑based contracting to secure reimbursement and preserve margins.
-
Partnerships versus in‑house expansion: For companies lacking regional reach or diagnostic capabilities, licensing or co‑promotion deals remain the fastest route to scale. The report’s decision trees quantify trade‑offs between revenue splits, speed‑to‑market, and control.
-
Supply chain resilience: The record of API supplier participation highlights the importance of multi‑tier qualification and commercial backup agreements—especially for markets where single‑supplier dynamics could disrupt launches.
-
R&D and label expansion: Sponsors should prioritize indication sequencing that maximizes early payer wins and diagnostic synergy; our scenario analysis identifies which clinical paths deliver the highest NPV under different access regimes.
-
M&A and portfolio optimization: Acquirers must calibrate valuations to account for patent life, potential generic entry, and the probability distribution of regulatory expansions—elements quantified in our valuation sensitivity models.
How PW Consulting’s report accelerates decision-making
PW Consulting frames strategic choices with executable outputs: a fully transparent market model, tactical negotiation scripts, supplier qualification checklists, and a sequence of prioritized strategic initiatives for 12–36 month horizons. The report is designed for C‑suite strategists, business development teams, market access leads, and private equity investors looking to translate market momentum into measurable outcomes in 2026.
To preserve competitive value, this briefing intentionally omits detailed region‑ and indication‑level splits and other granular tables that form part of the subscriber deliverable. Subscribers gain access to the complete set of disaggregated data, downloadable models, and an appendix of primary sources and regulatory filings that support every assumption.
Next steps
-
For executives planning portfolio moves in 2026: Request the full report package to run your organization’s preferred scenarios on our model and receive a customized strategic memo.
-
For BD/M&A teams: Commission a targeted diligence module that overlays the PW Consulting niraparib model on candidate assets or licensing targets to quantify synergies and downside risks.
-
For manufacturers and API suppliers: Use our supply chain playbook to benchmark capacities, identify white‑space opportunities, and de‑risk commercial commitments.
PW Consulting’s Worldwide Niraparib Market report converts a complex, rapidly evolving therapeutic market into a set of prioritized, high‑confidence decisions for 2026. For the complete dataset, disaggregated segmentation, and customizable forecast model, please visit the PW Consulting report portal and contact our Niraparib market team to arrange access and a bespoke briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Niraparib Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com