

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Waterproof Phone Pouch Market Set to Grow at a 5.8% CAGR Through 2032, New Report Finds

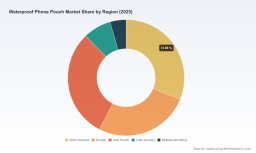
Worldwide Waterproof Phone Pouch Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new Worldwide Waterproof Phone Pouch Market report (base year 2025; historical 2020–2025; forecast 2026–2032) equips executives with the market-level intelligence and executable frameworks needed to set strategy in 2026. The market is on a moderate expansion path, sustaining a compound annual growth rate of 5.8% across the forecast horizon. In revenue terms, the global market measures in the mid‑hundreds of USD Million in 2025 and is projected to approach the high‑six‑hundreds USD Million by 2032. These topline dynamics, when combined with fragmentation metrics and supply‑side pressures, create a rich set of strategic inflection points for product, pricing, sourcing and M&A decisions in the coming 12–18 months.
Worldwide Waterproof Phone Pouch Market
Market trajectory and what it means for 2026 planning
The waterproof phone pouch category is moving beyond episodic, weather‑driven demand to more consistent, multifunctional adoption. While the market’s near‑term growth is steady rather than explosive, the underlying quality of demand is improving as consumers and professional users prioritize device protection, integrated services (e.g., power integration), and certified performance. For strategy teams, the key numeric anchors are: a stable CAGR ~5.8% through 2032 and a clear upward revenue path from the 2025 base. These anchors should be used as conservative planning bases for 2026 budgets—supporting targeted R&D, select product line investments, and supply‑chain hedging rather than broad, high‑risk expansion.
Worldwide Waterproof Phone Pouch Market
Why this market matters to product, commercial and corporate strategy in 2026
-
Product roadmaps: The category is maturing around technical certifications and integrated features (e.g., battery integration, higher IP ratings). R&D roadmaps should prioritize certification readiness, ergonomics and multi‑use functionality rather than trivial aesthetics.
Worldwide Waterproof Phone Pouch Market -
Channel and GTM: Growth is uneven across channels and occasions. 2026 GTM plans should favor channel mixes that combine mass retail for price entry points with specialist outdoor and professional channels for premium, higher‑margin SKUs.
-
Sourcing & cost management: Material and labor inflation are active tail risks. Immediate sourcing strategies should include multi‑sourcing, longer hedging windows for polymer inputs, and near‑term cost pass‑through playbooks.
-
M&A and partnerships: With industry concentration low (the three‑firm and five‑firm concentration ratios indicate a fragmented field), M&A can be used to buy capability—certified design, channel access or manufacturing scale—rather than pure market share. Small, targeted acquisitions are likely to deliver strategic upside in 2026.
Competitive landscape — what to watch in 2026
The category remains fragmented. Our concentration metrics show a low top‑tier concentration, indicating numerous regional and niche players. For 2026, firms with strong certification track records, integrated product capabilities, and resilient supply chains will outpace peers.
-
Pelican Products (Torrance, CA) — recognized for heavy‑duty Protector and Vault series pouches with high IP ratings and recent buoyancy‑focused product extensions. Pelican’s focus on marine & professional use cases positions it to capture premium segments where certification and durability carry price premiums.
-
OtterBox (Fort Collins, CO) — continues to leverage channel strength and brand equity. Recent product showcases signal intent to remain compatible with leading smartphone launches and to emphasize premium design in mainstream retail.
-
Lifeproof (Costa Mesa, CA) — with recent certification gains on advanced product variants (e.g., integrated battery pouches), Lifeproof is pushing into value‑added device protection that blends power and protection—an area ripe for premium monetization.
-
Catalyst — pursues IP68 performance and time‑limited submersion guarantees, offering a proposition that appeals to safety‑conscious buyers and professional users requiring documented performance.
-
China‑based OEMs (examples include Syncwire, Miady, Hiearcool) — continue to supply high‑value, price‑sensitive channels and white‑label opportunities. Their strengths are cost competitiveness and rapid SKU turnover—critical levers for retailers and private‑label manufacturers.
Taken together, incumbent premium brands and agile OEM suppliers form two distinct competitive playbooks: brand‑driven premiumization versus cost‑driven scale. 2026 winners will combine selective premium bets with disciplined cost-to-serve controls.
Supply‑side dynamics and regulatory risk
Three supply‑side pressures deserve immediate attention:
-
Raw material volatility: Polymer price shocks have raised baseline input cost for typical pouch materials. Procurement teams should assume a higher price floor and implement staged hedging or indexing arrangements to lock predictable margins into 2026.
-
Regulatory constraints: EU chemical rules now require phthalate‑free PVC for consumer pouches. This forces product reformulation and potential SKU rationalization for Europe‑facing lines. Regulatory compliance timelines should be integrated into 2026 product launch calendars and cost models.
-
Labor cost and on‑shoring tradeoffs: Rising manufacturing wages in key coastal manufacturing hubs have increased the landed cost of assembly. Companies should evaluate near‑shoring, automation, and value‑engineering to protect gross margins without sacrificing product quality.
In addition, the safety recall history for zipper seal failures under standard testing underlines the commercial and reputational risk of quality lapses. Product teams must embed third‑party testing and traceable QC into every SKU introduced in 2026.
Practical contents of the report — what PW Consulting delivers (preview)
The report is structured to be immediately operational for 2026 planning cycles. Highlights include:
- Market model with historicals (2020–2025) and a bottom‑up forecast (2026–2032) that isolates demand drivers and sensitivity to price, weather patterns and device replacement cycles.
- Fragmentation and concentration analysis with CR metrics, competitive positioning maps and capability heatmaps for incumbent and emerging players.
- Cost‑to‑serve and input cost model incorporating polymer pricing scenarios, labor cost trajectories and freight assumptions to stress‑test margin scenarios.
- Regulatory impact assessment and compliance timelines (including EU chemical regulation implications) with downstream cost and reformulation playbooks.
- Channel and pricing playbooks for mass retail, specialist outdoor, professional OEM and direct‑to‑consumer strategies, including sample KPIs and near‑term test & learn experiments.
- Actionable M&A screening: target archetypes, valuation multipliers by capability, and a stepwise integration checklist for 100–300 SKU bolt‑on deals.
- Risk register and contingency options (supplier disruption, certification failures, sudden raw material spikes), with sample contractual clauses and inventory buffers.
Note: While this press preview outlines themes and topline market metrics, the report contains granular regional, application and SKU‑level forecasts and a competitor benchmarking matrix that are intentionally not disclosed here. Access to the full dataset and models is available via the report landing page.
How to use the report in 2026 strategic cycles
-
Board and investor briefings: Use our topline revenue trajectory and concentration metrics to justify capital allocation and to set realistic top‑line assumptions in 2026 budgets.
-
Product and R&D planning: Map product roadmaps to certification and regulatory timelines in the report to avoid costly last‑minute redesigns.
-
Sourcing decisions: Apply the input cost scenarios to select a mix of multi‑sourcing, longer‑term contracts and near‑shoring pilots to hedge against polymer and wage inflation.
-
M&A screening and JV negotiation: Use the provided target archetypes and valuation guide to prioritize bolt‑on acquisitions that accelerate certification capability, channel access, or manufacturing adjacency rather than stand‑alone market share buys.
-
Commercial pilots: Implement split‑tests across channel partners using the playbooks and KPIs in the report to validate pricing elasticity and cross‑sell opportunities in 90‑day sprints.
Conclusion — a 2026 playbook in preview
The waterproof phone pouch market presents a pragmatic growth opportunity: predictable topline expansion coupled with meaningful margin and regulatory complexity. For 2026, the strategic imperative is not to chase scale alone but to align product certification, supply resiliency, and channel specialization. Brands that act early on compliance reformulation, embed third‑party testing, and adopt disciplined procurement hedges will convert steady market growth into sustainable margin improvement.
Next steps
PW Consulting’s full report contains the confidential segmentation tables, regional and application forecasts, and downloadable financial models that underpin the recommendations summarized here. To obtain the complete dataset, competitor benchmarking, and actionable templates for 2026 implementation, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Waterproof Phone Pouch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com