

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 7.58% CAGR for Worldwide Canine Mammary Tumor Treatment Market in 2026–2032

Worldwide Canine Mammary Tumor Treatment Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Canine Mammary Tumor Treatment Market delivers a focused, practice-oriented assessment designed to inform board-level strategy, R&D prioritization, and commercial execution through 2032. This briefing offers an executive synthesis of the report’s most consequential findings—highlighting growth trajectories, competitive dynamics, technology inflection points, and pragmatic actions that animal health and veterinary service leaders should consider in 2026. To preserve the investigative depth that underpins our recommendations, detailed segment-level tables and proprietary financial models are intentionally reserved for the full report.
Worldwide Canine Mammary Tumor Treatment Market
Macro snapshot: a market on a sustained expansion path
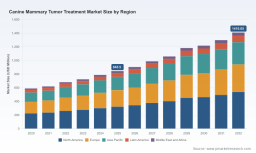
Our baseline, anchored to 2025 as the base year, shows a market that has expanded materially over the past half‑decade and is set for continued, mid‑single‑digit to high‑single‑digit growth through the next planning cycle. Specifically, the global market for canine mammary tumor treatment rose from under USD 600 million in 2020 to roughly USD 845.5 million in 2025. Under our central scenario the market grows at a compound annual growth rate (CAGR) of approximately 7.58% over the 2026–2032 forecast window, reaching just over USD 1.4 billion by 2032.
Worldwide Canine Mammary Tumor Treatment Market
Drivers behind this trajectory include demographic trends in pet ownership, higher owner willingness to invest in advanced care, accelerating adoption of precision diagnostics and targeted therapies in veterinary oncology, and the growing availability of high‑end radiotherapy and interventional services in specialty centers. These dynamics are complemented by translational research that leverages canine mammary tumors as comparative models for human breast cancer—creating a two‑way flow of innovation that benefits both industries.
Worldwide Canine Mammary Tumor Treatment Market
What the 2026 strategic agenda should prioritize
- Evidence generation as commercial foundation: With surgery remaining the gold standard for most presentations and adjuvant systemic options largely used off‑label or in high‑risk cases, the single most valuable investment for product teams and service providers is robust, veterinary‑specific clinical evidence. Expect regulatory advantage for companies that can pair clinical efficacy with well‑documented quality‑of‑life and recurrence outcomes.
- Precision diagnostics and targeted deployment: Genomic and biomarker‑driven approaches are moving from academic curiosity to clinical utility—enabling more targeted use of tyrosine kinase inhibitors, immunomodulators, and other systemic options. Companies that integrate testing, consultative services, and outcome tracking will capture disproportionate value.
- Service model diversification for veterinary practices: Referral networks, hub‑and‑spoke radiotherapy offerings, and capital‑light service partnerships (e.g., mobile or visiting specialist models) will be important for clinics seeking to retain complex cases locally while controlling investment risk.
- Regulatory strategy tuned to veterinary realities: Recent regulatory pathways such as Minor Use in Major Species (MUMS) designations are materially impactful. Firms that align trial designs with veterinary endpoints and pursue regulatory incentives can convert promising molecules into commercially differentiated products faster and with greater uptake.
Report contents: practical tools for immediate action
PW Consulting’s full study provides hands‑on assets that leadership teams can implement in 90–180 day cycles, including:
- Demand models and scenario‑based revenue projections to support R&D and investment prioritization across the 2026–2032 forecast period.
- Clinical evidence roadmaps—trial designs, endpoint recommendations, and sample-size guidance—to accelerate label expansion or veterinary indication claims.
- Pricing and reimbursement playbooks benchmarked to clinic economics, including procedure cost ranges and sensitivity analyses for owner affordability versus clinic margin.
- Technology adoption frameworks for imaging, precision radiotherapy, and molecular diagnostics that translate capital investments into utilization and revenue metrics.
- Competitive intelligence dossiers with actionable M&A target screening criteria and partner selection matrices focused on biotech, device, and service businesses.
Competitive landscape — who matters and why
The competitive environment combines established animal health leaders, oncology‑focused biotechs advancing veterinary indications, device manufacturers supplying precision radiotherapy, and a growing cohort of specialty service providers. Market concentration is moderate: the top three competitors account for a meaningful share of market value while the top five capture a clear majority—indicative of an industry where scale, distribution, and clinical footprint matter.
- Zoetis Inc. remains a strategic bellwether due to its portfolio depth and the clinical role of established targeted therapies in multi‑modal protocols. Its distribution network and veterinary relationships make Zoetis a first mover for commercialization programs tied to companion diagnostics and supportive care bundles.
- Boehringer Ingelheim Animal Health and Elanco bring legacy animal health capabilities and inorganic growth playbooks; their scale supports broad outreach and potential rollup strategies for oncology assets and services.
- Specialist biotechs (AB Science, Karyopharm, VetDC, CureLab) are advancing novel mechanisms—tyrosine kinase inhibitors, nuclear export inhibitors, and p62‑based immunotherapies—that could reshape systemic treatment choices if supported by veterinary trial data and favorable regulatory outcomes.
- Precision medicine and service players (FidoCure, PetCure Oncology) are shifting the delivery model: genomic testing and centralized radiosurgery services reduce the barrier to advanced care and create recurring revenue streams through service subscriptions or case‑by‑case referrals.
- Device vendors (Accuray, Varian/Siemens Healthineers) are important partners for specialty hospitals and referral centers investing in high‑precision radiotherapy; their technology decisions influence case mix and referral patterns.
Recent industry moves with strategic implications
- Regulatory momentum: AB Science’s recent MUMS designation for masitinib (early 2026) illustrates how targeted regulatory pathways can de‑risk veterinary oncology approvals and expand on‑label opportunities. Companies should assess MUMS and similar incentives as a core element of product development strategy.
- Surgical and imaging innovation: Ongoing work on intraoperative Optical Coherence Tomography (OCT) highlights a step‑change opportunity to improve surgical margins and reduce recurrence—this has direct implications for equipment suppliers, surgical training programs, and perioperative service bundles.
- Cost and access signals: Clinic‑level treatment costs remain a key constraint on uptake for advanced therapies; surgical procedures typically dominate immediate expenditures, and owner willingness to pay is strongly influenced by perceived survival benefit and quality‑of‑life outcomes.
Strategic recommendations for 2026 corporate plans
- Prioritize veterinary evidence for translational candidates: If your pipeline includes molecules with cross‑species oncology potential, invest early in veterinary trial infrastructure and KOL engagement. Veterinary‑specific endpoints and owner‑centric outcomes materially accelerate commercial uptake.
- Bundle diagnostics and therapy: Create integrated offerings where genomic testing or intraoperative imaging is sold together with therapy or service‑level agreements. Bundling reduces owner friction and increases lifetime value per patient.
- Consider asset transactions and partnerships: Given moderate market concentration and the high cost of building specialty services, acquisitive moves or strategic alliances with service providers (e.g., radiation networks, genomic platforms) offer faster access to established referral pipelines.
- Adopt a differentiated go‑to‑market for clinics: Tailor sales and training programs to the economic realities of primary veterinary hospitals versus specialty referral centers; different packaging and financing options will drive higher conversion.
- Monitor regulatory incentives closely: Align registrational programs with mechanisms like MUMS to accelerate market entry and capture premium pricing for hard‑to‑treat indications.
What PW Consulting delivers beyond this preview
This preview synthesizes the strategic implications of the market’s macro growth and competitive shifts. The full PW Consulting report is a working tool for commercial leaders and investors—it includes the complete dataset, segmented demand curves, product‑level uptake models, clinic economics dashboards, competitor heatmaps, and executable 12–36 month roadmaps. It also offers bespoke scenario modeling support tailored to M&A diligence, investor presentations, or board strategy sessions.
To preserve the commercial value of our primary research and modeling, detailed segment breakouts and company‑level financial estimates are available exclusively in the full report. We intentionally limit the granularity shown here to stimulate action and direct interested parties to the complete deliverable.
Next steps
- Schedule a briefing with PW Consulting to review the interactive models and discuss custom scenarios for your organization.
- Commission targeted diligence if you are evaluating acquisitions, licensing, or pilot partnerships in veterinary oncology.
- Request the full report for access to proprietary segmentation, clinic‑level pricing modules, and competitor valuations that underpin our recommendations.
For organizations positioning for growth in the evolving canine mammary tumor treatment landscape, 2026 is a pivotal year to convert scientific promise into commercially viable solutions. PW Consulting’s full report equips decision‑makers with the evidence, economic clarity, and strategic roadmaps necessary to capitalize on the market’s projected expansion. Visit our report page to obtain the comprehensive analysis and data packages required to move from insight to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Canine Mammary Tumor Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com