

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Industrial Wiping Cloth Market to Reach USD 4,520.0 Million in 2025, Growing at 5.15% CAGR (2026–2032) as Asia‑Pacific and Non‑woven Segments Lead

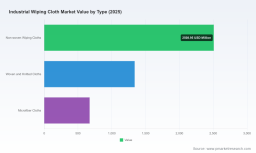
Worldwide Industrial Wiping Cloth Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s newly completed Worldwide Industrial Wiping Cloth Market report (base year 2025; historical 2020–2025; forecast 2026–2032) furnishes senior executives, procurement leaders, and strategic investors with an actionable view of a market that is simultaneously mature in its core use cases and dynamic at the technology, sustainability, and service-model edges. Our analysis shows the industry transitioning from commodity-driven volume play toward differentiated value streams—driven by materials innovation, circular-economy practices, and service-led models. This preview explains why the report is essential to shaping 2026 strategies without disclosing the granular segment tables reserved for the full publication.
Worldwide Industrial Wiping Cloth Market
Market at a Glance: Macro Trajectory and Structural Signal
The global industrial wiping cloth market was valued at approximately USD 4,520.0 Million in 2025. Under PW Consulting’s base-case forecast, the market expands at a compound annual growth rate (CAGR) of 5.15% over the 2026–2032 forecast horizon, reaching an estimated USD 6,423.97 Million by 2032. The immediate step-up into 2026 is visible—reflecting ongoing recovery in key end-use industries and the layered impact of sustainable-material uptake and service innovations.
Worldwide Industrial Wiping Cloth Market
Two structural signals underpin our outlook. First, market concentration is low: the three-largest suppliers account for roughly 18.4% of revenue and the five-largest about 26.5%, indicating a fragmented competitive landscape. Second, the mix of raw materials and channels is evolving—nonwoven technologies, recycled textile streams, and service-based rental/managed-supply models are redefining value capture.
Worldwide Industrial Wiping Cloth Market
Why this report matters to 2026 corporate agendas
- Procurement optimization: Buyers face margin pressure and supply volatility in fiber and polymer markets. Our report quantifies sensitivity of supplier cost models to shifts in raw-material inputs and provides tactics (contracting levers, dual-sourcing templates, vendor scorecards) to protect margins and continuity.
- Product & manufacturing strategy: The transition from cotton rags to engineered nonwovens and microfiber blends is not just technical—it reshapes capital intensity, yield, and environmental reporting. We map technology-readiness, CAPEX implications, and regulatory exposure so manufacturers can prioritize retrofit versus greenfield investments.
- Commercial differentiation: Service models—rental, managed wiper programs, and certified recycled-product lines—create recurring revenue and higher gross margins. The report evaluates go-to-market frameworks and partner ecosystems required to operationalize those models at scale.
- M&A and portfolio planning: With a fragmented base and concentrated pockets of technical capability, there are clear roll-up targets and bolt-on opportunities to create capabilities in engineered wipes, contamination control, and rental services. Our target-screening framework and valuation overlays are tuned to 2026 transaction dynamics.
What PW Consulting’s report delivers (practical, implementable content)
- Transparent market-sizing and scenario-based forecasts (2026–2032) with sensitivity testing for raw-material price shocks and end-market demand shifts.
- Go-to-market playbooks for four archetypal suppliers: commodity-volume distributors, engineered-wipe specialists, rental/managed-service providers, and low-cost exporters.
- Procurement toolkit: RFx templates, supplier segmentation heatmaps (by reliability, cost, sustainability), and a three-step rapid supplier-audit protocol.
- Cost-to-serve and margin model templates that connect fabric type, processing route, and logistics to unit economics—enabling quick scenario testing in board-level discussions.
- Sustainability roadmap: pathways for integrating post-consumer recycled textiles, manufacturing-efficiency KPIs, and third-party certification implications for public tenders and enterprise buyers.
- Regulatory and standards primer reflecting industry discussions at recent trade fora (World of Wipes, Clean Show), and implications for manufacturing controls and labeling.
- Competitive benchmarking, including vendor strengths, channel positions, and service portfolios—designed to support vendor selection and partnership decisions.
Competitive landscape: strategic takeaways on core players
The market is populated by a mix of long-established regional manufacturers, technical specialists, family-owned distribution groups, and export-oriented OEMs. A selective read on several influential players presents the shape of competition and partnership opportunity:
- Carolina Textiles (United States) — A Southeast U.S. incumbent with depth in manufacturing and wholesale distribution across automotive, marine, and janitorial channels. Strengths: distribution density, established OEM and maintenance accounts, and inventory scale. Strategic implication: acquisition of regional distributors or investments in traceability systems could expand service-led offerings.
- Berkshire Corporation (United States) — Positioned in engineered wipes and controlled-environment applications. Strengths: technical product development, high-value customers in critical manufacturing. Strategic implication: an attractive partner or acquisition target for buyers seeking contamination-control capabilities.
- U.S. Wiping Company, A&A Wiping Cloth, Wi-Supply, Wipeco, Anchor Wiping Cloth (United States) — A cluster of resilient regional players focused on absorbent, durable wipes and rapid fulfillment. Strengths: customer intimacy, flexible production, and legacy supplier relationships. Strategic implication: these firms are prime candidates for digital-commerce upgrades and managed-supply platform integration.
- Kleenrags, JEENOR, SYSBEL (China) — Export-focused manufacturers leveraging cost-efficient production and scale in nonwoven and heavy-duty wiping products. Strengths: price competitiveness and engineering for heavy-grease or high-absorbency applications. Strategic implication: Western buyers will balance cost benefits with nearshoring, quality assurance, and carbon/traceability considerations.
- Lindstrom Group (Finland) — Differentiated through a rental/managed-service model with regular pickup and replacement. Strengths: strong service-oriented value proposition and ESG credentials via reuse and centralized laundering. Strategic implication: rental-as-a-service is an increasingly defensible margin pool for suppliers willing to invest in logistics and textile-care infrastructure.
Market dynamics shaping winners and losers in 2026
- Raw-material evolution: The basket of commonly used fibers—cotton rags, polyester, spunlace nonwovens, airlay, and meltblown polypropylene—remains core. However, suppliers that secure low-cost, certified post-consumer recycled feedstocks or that can demonstrate higher-performance nonwoven blends will command premium placement.
- Sustainability and circularity: Recycled textiles are increasingly cascaded into wiping applications. Buyers are demanding traceability and life-cycle assessments as part of procurement. Suppliers who can offer validated recycled-content products and closed-loop service models will win large enterprise contracts.
- Standards and technical differentiation: The industry’s technical axis—from engineered wipes for semiconductors to heavy-duty rags for metalworking—creates distinct procurement bands. Participation and thought leadership at industry conferences (e.g., World of Wipes, Clean Show) is becoming a competitive necessity for firms that compete on specification.
- Fragmentation-led M&A: Low top-line concentration suggests consolidation upside. Buyers should expect opportunistic bolt-ons in 2026–2027 as acquirers pursue scale, geographic coverage, and technical niches.
Actionable strategic recommendations for 2026
- For buyers/procurement heads: Execute a two-track sourcing strategy—secure tactical cost relief via diversified sourcing while piloting managed-supply or rental programs with providers that can demonstrate LCA improvements.
- For manufacturers: Prioritize modular investments that enable flexible switching between cotton, recycled fibers, and engineered nonwovens; add small-scale pilot lines for high-margin engineered wipes rather than wholesale capital expansion.
- For investors/M&A teams: Target vertical scopes that add contamination-control expertise, service logistics, or recycled-textile feedstocks. Use PW Consulting’s valuation templates to stress-test synergies under raw-material price volatility.
- For service innovators: Double down on rental and managed-supply operations in de-risked verticals (food & beverage, healthcare laundry) and pair with certification programs to penetrate enterprise procurement frameworks.
Methodology and confidence framework
The report synthesizes primary interviews with industry participants, supply-side manufacturing audits, trade-show intelligence (including insights from World of Wipes and Clean Show events), and bottom-up costing models calibrated to publicly available financials and supplier data. We provide probabilistic scenario bands to reflect macroeconomic variance, raw-material shocks, and technology-adoption curves so executives can stress-test capital and commercial plans.
Next steps: how to use the full report in your 2026 planning cycle
- Download the executive summary to validate headline forecasts and concentration metrics, then book a PW Consulting briefing to walk through the segment-level tables and supplier scorecards (these are intentionally excluded from this public preview).
- Commission a 12-week readiness assessment if you are contemplating a managed-supply launch, nearshoring initiative, or targeted acquisition—PW Consulting’s implementation teams will translate the report’s strategic findings into an operational roadmap.
- Use the procurement toolkit and cost models included in the full report to run three supplier-sourcing scenarios and present board-ready outcomes by Q3 2026.
PW Consulting’s Worldwide Industrial Wiping Cloth Market report is calibrated for leaders who require both market visibility and practical execution plans. The market’s macro trajectory—from roughly USD 4.5 billion in 2025 toward more than USD 6.4 billion by 2032 at a 5.15% CAGR—creates multiple strategic inflection points in 2026. If your 2026 planning includes supply-chain redesign, product differentiation, sustainability commitments, or M&A, this report is structured to convert insight into measurable action. For the complete data tables, supplier-level benchmarks, and proprietary scenario models, please visit our report page or contact our industry practice to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Wiping Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com