

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide IR Carbon Sulphur Analyzers Market to Expand at 4.85% CAGR Through 2032, Report Finds

Worldwide IR Carbon Sulphur Analyzers Market: Strategic Insights for 2026 Decision‑Makers
Executive Preview — PW Consulting Market Brief
The IR Carbon Sulphur (C/S) analyzers market is entering a decisive phase where product differentiation, consumables control, and targeted application strategies will determine competitive winners. PW Consulting’s latest market study synthesizes historical performance (2020–2025) and a robust forecast (2026–2032) to equip senior executives, corporate development teams, and product leaders with the context and strategic options necessary to act in 2026.
Worldwide IR Carbon Sulphur Analyzers Market
Market Trajectory and Forecast
Key macro dynamics are clear: demand for infrared combustion-based carbon and sulfur analyzers has shown steady expansion through the first half of the decade. The global market grew from USD 383.12 Million in 2020 to USD 485.50 Million in 2025. As technologies mature and addressable applications broaden beyond traditional metallurgy into adjacent industries, our model projects continued expansion — with the market forecast to reach USD 676.36 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. Early forecast years show incremental growth (USD 502.83 Million in 2026), accelerating as new application pull and after‑sales revenues scale.
Worldwide IR Carbon Sulphur Analyzers Market
For decision-makers, these topline dynamics matter because they signal a market that is neither hyper‑disruptive nor saturated: predictable demand with pockets of high strategic upside. That combination favors targeted investment and disciplined go‑to‑market plays rather than broad, undifferentiated expansion.
Worldwide IR Carbon Sulphur Analyzers Market
Why This Report Matters for 2026 Strategy
- Actionable forecasting calibrated to execution timelines: our 2026–2032 forecast aligns with typical product development and commercialization cycles, allowing companies to plan R&D, manufacturing capacity, and channel investments with confidence.
- Commercial levers prioritized: the report connects hardware sales to higher-margin recurring revenue streams (consumables, accelerators, crucibles, service contracts) and quantifies the potential uplift from service-centric business models.
- Risk-adjusted scenario planning: we present alternative market paths under different adoption and raw-material scenarios, enabling finance and strategy teams to stress-test capital allocation decisions.
Competitive Landscape and Technology Differentiators
The IR C/S analyzer sector remains anchored by established instrument vendors and a spectrum of regional players. The competitive set can be grouped by technology approach and go‑to‑market focus:
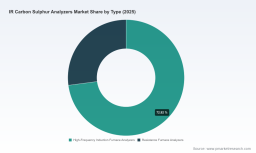
- High-frequency induction furnace specialists with NDIR (infrared) detection — focused on speed, throughput, and inorganic solids performance. Notable vendors emphasize high-temperature induction combustion and fast cycle times for metals, alloys, and refractory materials.
- Dual‑mode and resistance furnace providers — targeting versatility across organic and inorganic matrices via combined furnace architectures and tailored detection chains.
- Value-oriented regional suppliers — competing on cost, local service, and customization for captive industrial buyers in regions with strong manufacturing bases.
Representative competitor positioning (high‑level):
- HORIBA, Ltd. (Kyoto, Japan): Known for the EMIA series spanning entry to flagship models, HORIBA emphasizes reliability, user ergonomics, and upgrades for handling challenging, moisture‑bearing samples. Recent documentation updates reinforce throughput and operator experience advantages.
- ELTRA GmbH (Haan, Germany): Differentiates with hybrid furnace designs (induction + resistance) enabling broad sample compatibility. The ELEMENTRAC portfolio expansion signals a push into adjacent elemental analytics and laboratory consolidation plays.
- LECO Corporation (St. Joseph, Michigan, USA): A long-established vendor with a wide application remit; recent communications highlight application optimization for cement and process control, underlining an execution focus on industrial process analytics beyond metallurgical labs.
- Elementar, Bruker, Labtron, Torontech, BIOBASE, JIEBO: Each brings positional strengths—speed, detector specialization, low‑concentration accuracy, regional service networks, or cost leadership—that shape segment dynamics.
Notable recent moves underscore evolution in competitive tactics: LECO’s early‑2026 emphasis on cement applications reflects a play to capture process analytics in high‑volume industrial settings; HORIBA’s 2025 EMIA refresh reinforces product usability and sample‑handling reliability; ELTRA’s portfolio extension in 2025 signals continued platform diversification. These activities show a market balancing incremental product improvement with targeted application expansion rather than radical technology substitution.
Supply Chain, Consumables and Operational Risks
Beyond analyzer hardware, consumables and sample preparation inputs represent a meaningful and often under‑appreciated profit pool — and a strategic vulnerability. Ceramic crucibles and tungsten or tungsten‑tin blend accelerators remain standard consumables across major instrument families. High‑purity tungsten accelerators (commonly specified at particular grain sizes) are critical to guaranteeing complete combustion in high‑frequency induction systems. Our supply‑chain analysis highlights three implications for 2026 planning:
- Consumables as lock-in: service and consumables programs are a reliable margin driver and a defense against pure hardware commoditization. Firms that design proprietary consumable formats or tight service bundles can capture recurring revenue and improve customer retention.
- Supply concentration risk: key raw materials (tungsten alloys, high‑grade ceramics) have geographically concentrated supply and are exposed to trade policy and price volatility. Procurement teams should consider multi‑sourcing, strategic inventory, or vertical partnerships for critical accelerators and crucibles.
- Cost pass‑through sensitivity: OEMs with thin hardware margins must model scenarios where consumable cost increases cannot be fully absorbed, and plan commercial tactics (multi‑year contracts, hedging) accordingly.
Regulatory and Substitution Considerations
The IR combustion analyzer market faces both regulatory and technological headwinds/opportunities. Environmental monitoring and emissions testing requirements can expand demand for robust sulfur analysis, whereas innovations in non‑combustion elemental techniques (e.g., advanced XRF, laser‑based analyzers) present substitution threats in niche use cases. The net effect through 2032 is gradual growth with pockets of accelerated adoption where combustion IR retains clear accuracy or throughput advantages.
Report Contents — What You’ll Find Inside
PW Consulting’s full market report is structured for decision-making and immediate operational use. Key components include:
- Detailed market model (2020–2032) with scenario sensitivity and topline drivers mapped to commercial KPIs.
- Methodology appendix describing demand drivers, addressable applications, and model assumptions — enabling reproducibility and internal re‑calibration.
- Competitive profiles and product benchmarking that compare furnace architectures, detection subsystems, sample throughput, and typical TCO components.
- Consumables and supply‑chain risk analysis, supplier mapping, and a supplier‑risk heatmap focused on tungsten and ceramic inputs.
- Go‑to‑market playbooks for OEMs, distributors, and service providers covering pricing strategies, channel design, after‑sales programs, and OEM vs. third‑party consumable economics.
- M&A and partnership opportunities: screening criteria, target archetypes, and valuation sensitivity for bolt‑on acquisitions or strategic alliances.
Note: In keeping with our “trailer” approach, the executive preview intentionally highlights the report’s structure and the strategic questions it answers while reserving proprietary segmentation depth and granular revenue splits for the full report.
Strategic Recommendations for 2026
Based on our analysis, we advise companies to prioritize three pragmatic moves in 2026:
- Double down on consumables and services: launch or harden multi‑year consumable contracts and service plans. Capture more of the installed base’s lifetime value rather than competing solely on hardware price.
- Target adjacent industrial applications with tailored value propositions: adapt existing combustion platforms for process analytics in high‑volume industries (e.g., cement, specialty chemicals, battery materials) where throughput and ruggedness justify premium positioning.
- Hedge supply risk and rationalize sourcing: secure long‑lead purchases for tungsten accelerators and high‑performance crucibles, and evaluate vertical integration or strategic supply partnerships for critical inputs.
For R&D and product teams, incremental innovation that improves sample throughput, moisture tolerance, and low‑concentration detection will yield outsized commercial returns. For commercial teams, bundling analytics software, diagnostics, and remote monitoring into service packages will raise switching costs and stabilize margins.
How PW Consulting Can Support Your Investment and Execution
PW Consulting offers tailored advisory services to convert the report’s insights into executable plans. Our engagements typically include:
- Targeted due diligence for M&A, including complementary product fit and consumables revenue accretion analysis.
- Go‑to‑market redesigns for tiered channel strategies, pricing frameworks, and industrial vertical plays.
- Supply‑chain resilience programs focused on critical consumables and component sourcing optimization.
- Commercial pilots and value‑capture roadmaps to convert installed‑base customers into subscription and service revenues.
Concluding Thought
The IR Carbon Sulphur analyzer market in 2026 presents a strategic choice: pursue scale through low‑margin hardware competition, or build differentiated, service‑anchored positions that leverage consumables and application specialization. PW Consulting’s Worldwide IR Carbon Sulphur Analyzers Market report provides the numbers, scenario tools, and competitive intelligence needed to make that choice with conviction. For access to the full data set, granular segmentation, and actionable financial models, consult the complete report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide IR Carbon Sulphur Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com